Pinned · The pitch deck
The promoter deck, fifteen slides
Large print, 26 October 2026. Send the PDF; present from the PPTX.
Large print, 26 October 2026. Send the PDF; present from the PPTX.
| Rank | Your stake | Directs | Largest lineEach side | All other lines | DAO band |
|---|---|---|---|---|---|
| V1 | $500 | 3 | $10,000 | $10,000 | 5–10% |
| V2 | $1,500 | 4 | $50,000 | $50,000 | 8–15% |
| V3 | $3,000 | 5 | $150,000 | $150,000 | 10–20% |
| V4 | $5,000 | 6 | $300,000 | $300,000 | 15–25% |
The quick route: your own stake first, then the directs ($100 or more each), then two sides at once. The largest line qualifies the rank; all the other lines together are the small zone, and the small zone is the one the DAO reward is paid on, so grow it first. Bands as stated; not a promise of return.
Start with the pitch, then the seven steps into the system, then the numbers, then the depth. Ask any question and the answer appears right here with the picture that goes with it. Every file, every figure with its cap and its date, every official link. Send from here. Do not forward old copies.
Read the pitch, then do the seven steps below in order, one evening, with a small amount. Everything deeper on this page, the numbers, the official statements, the objections, the leader material, comes after, once you are in.
The project now sends every new international partner one message before it talks about mechanisms, returns or price: how Spartan OS reached 35 million USDT, with the correction and the recovery left in, and the six lines of culture the early communities took from it. Send it before the deck when the person has time to read, after the deck when they do not. The message, whole, with the short versions.
Every rate carries its cap and its date, as stated by Spartan OS on 7 and 14 September 2026. Rates float; caps are fixed at entry. Nothing here is a guarantee and nothing here is financial advice. Present the files as issued; translate with approval; never edit a number. Official links come only from anubischain.ai, and no official account will ever ask for a seed phrase.
Built for Zoom. Origin, chain, Spartan OS, the five income streams, staking, bonds, staking or the bond on $5,000, the V1 to V12 ladder and how a rank is built, O², how to start, and the official links with scan codes.
The PDF opens on any phone. The PPTX is fully editable, with speaker notes on every slide.
Large-print edition, in every language since 26 October 2026, fifteen slides: the comparison of staking and the 540-day bond on $5,000 and the two-leg rank structure added, the chain and Spartan OS figures re-read on 15 November 2026.
Click a slide to view it full size. Slide images are for screens; send the PDF, not screenshots.
Same fifteen slides, same figures, checked string by string against the English. The English edition is the reference; the others are re-issued after every change to it.
For the person who has never held a wallet. Wallet, chain, fuel, USDT, the referral link, the 540-day bond, the first claim. Each step has the written version and the Phalanx team's films for it, one per wallet. Do them in order, one evening, with a small amount first. Staking is not one of the seven: it comes after you are in and hold RM bought from your leader. Send this section to a new person instead of explaining it on a call.
Install Bitget Wallet from the official app store listing (Anubis Chain recommends it; the chain is built in, and swap and cross-chain work inside it). OKX Wallet, TokenPocket, Binance Wallet or MetaMask work too, with the network added by hand in step 2. Create a new wallet, write the seed phrase on paper, and keep the paper offline. No official account will ever ask for it.
A phone or a computer, ten minutes, a pen.
The wallet shows an address that begins with 0x. That address is the same on every EVM chain, including Anubis.
All the films, by wallet, in Tutorials.
In Bitget Wallet, Anubis is already in the network list: switch to it. In any other wallet, add a custom network with exactly these values: name Anubis, RPC https://rpc.anubispace.org, chain ID 6714, symbol DAI, explorer https://browser.anubispace.org. If the wallet's search shows several networks called Anubis, do not pick one; the chain ID 6714 is the only identifier that matters.
The five values above. Nothing else.
The wallet shows chain ID 6714 and a balance in gasDAI (0 for now). chainlist.org/chain/6714 shows the same values.
All the films, by wallet, in Tutorials.
Every transaction on Anubis costs a fraction of a cent, paid in gasDAI. A wallet with no gasDAI cannot do anything, so this comes before the first transfer. On BNB Chain, buy or swap five to ten dollars into DAI, then bridge it to Anubis: app.anubisbridge.com, galebridge.net, or the cross-chain screen inside Bitget Wallet, typed by hand, never from a link in a chat. Source BNB Chain, destination Anubis (6714). The DAI arrives as gasDAI.
Five to ten dollars of DAI on BNB Chain, and a little BNB for the withdrawal gas there.
The wallet, on Anubis, shows a gasDAI balance. Paste your address into browser.anubispace.org and the same balance appears.
All the films, by wallet, in Tutorials.
Buy USDT on any exchange and withdraw it to your wallet address on BNB Chain (BEP-20); it is the cheapest source chain to bridge from. Then bridge it to Anubis the same way as the DAI: 10 to 50 USDT first, the rest once it has arrived. Anubis Bridge is free and slower (the leaders quoted two to three hours); GaleBridge takes seconds and charges 0.5% to 1.5%, as stated on 7 September. Never send Anubis assets straight to an exchange later; bridge back first.
USDT on BNB Chain, gasDAI from step 3. The bridge shows the fee before you approve.
browser.anubispace.org shows the USDT balance on your Anubis address.
All the films, by wallet, in Tutorials.
Join the Phalanx channel first, then open the Spartan OS dApp at spartanar.org through the referral link your leader gives you in person, or enter the invitation code where the dApp asks for it. Connect the wallet on Anubis and let it synchronise. The dApp binds the referrer the first time the wallet connects and it cannot be changed later, so never use a link from a public chat. The dashboard then shows the live rates and caps for every product: those are the figures to quote, never the ones in a chat.
The link or code from the person who introduced you, and the wallet holding USDT and gasDAI.
The dashboard shows your address, your USDT balance and the name of your referrer.
All the films, by wallet, in Tutorials.
On the dashboard choose the liquidity bond, 540 days. You pay in USDT and receive RM at the bond price, which is below the market price: on 9 November 2026 the 540-day bond was 26.00% below market (1,000 USDT bought 40.44 RM against 32.10 at market), and the project states the discount is not fixed. Principal and rewards are released daily across the 540 days, with a cap of 5× the entry in USDT, fixed at entry, and the daily rewards can be compounded. This is the entry the international team recommends at this stage, and it comes before any staking: staking follows once you are in the system and hold RM bought from your leader. Read the bond price, the discount and the cap on the screen before you confirm, and run the amount through the calculator first.
USDT on Anubis, gasDAI for the fee. From one dollar; test with a small bond first.
The bond appears on the dashboard with its term, price and cap. Rates and discounts float; caps are fixed at entry. Nothing here is a promise of return.
Every release, from the bond, staking, rank rewards and level income alike, is claimed through the turbine (the turbo pool): you buy the same amount of RM on RocketSwap, one to one, wait 24 hours, and both amounts are yours. To see RM and GD in the wallet, import their contract addresses once from the Terms today section (compare the first four and last four characters). Interest compounds if left in; extra rewards do not, so claim them daily.
gasDAI for the claim and USDT for the matching purchase on RocketSwap.
The claim and the matching purchase both show on browser.anubispace.org under your address; the wallet lists RM and GD.
All the films, by wallet, in Tutorials.
Staking is not one of the seven. It comes after you are in the system and hold RM bought from your leader: from then on the staking products on the dashboard (flexible, 180, 360 and 540 days) are open to you, with the rate and the cap read from the screen on the day. The bond is the entry; staking is what follows it, with tokens that came from your leader. Lessons C4 and C5 show the staking screens.
Type addresses, do not click them: links come from anubischain.ai or the official X accounts only. Check the chain ID is 6714. Verify the first four and last four characters of every address. Test each new route with a small amount. Keep the seed phrase on paper. No official account will ever ask for it. Every rate on this page carries its cap and its date; rates float, caps are fixed at entry, and nothing here is a promise of return.
The channel, the referral link, then the seven steps. In that order, because the link binds the account to its leg the first time the wallet connects, and that cannot be undone.
The community channel on Telegram: announcements, the calls, the current material, and the people who will answer your first questions. Everything on this page is posted there first.
The Spartan OS dApp places every account under the person who invited it. Open the link, connect the wallet, and the dApp binds the referrer. It cannot be changed later, so use the link from your leader, not one from a chat.
Referral code (the wallet address in the link): 0x83659d0BDF57ac8550060E869fC5926e52E2e5Fe
Wallet, Anubis Chain, gasDAI, USDT, the referral link, the 540-day bond, the first claim. One evening, a small amount first. The Get in section walks through each with the written version and the team's films, one per wallet.
Three hundred held a pass because each one covered the next. The community works the same way: every figure carries its cap and its date, nobody promises a return, links come from this page or the official accounts only, and a question that is not answered here goes to a leader rather than to a guess. A promoter who keeps those four rules can be trusted with a team.
Open this page in Safari. Tap the share button, then Add to Home Screen, then Add. The icon opens the library full screen, without the browser bar.
Open this page in Chrome. Tap the three dots, then Add to Home screen (or Install app), then Add.
In Chrome or Edge, click the install icon at the right of the address bar, or the three dots and Install. The library opens in its own window.
Once installed, the pages you have opened stay readable when the connection drops; new editions load when you are back online. Nothing is stored beyond the page itself and the files you have viewed.
The figures a promoter is asked for every day, read from the dApp on one date and marked with it. Rates float and the dApp is the reference: if the screen in front of you differs from this page, the screen wins, and the page is updated at the next edition.
| Bond | Bond price | Below market | Cap, same as the stake |
|---|---|---|---|
| 180-day bond | $30.3089 | 2.79% | 4× |
| 360-day bond | $26.0668 | 19.52% | 4.5× |
| 540-day bond | $24.7272 | 26.00% | 5× |
Long-term stakes at 1.1%, 1.2% and 1.3% a day as stated on 7 September 2026 (14 September: over 1.0%, 1.1% and 1.2%); the dApp shows the cap, not the rate. A bond buys RM below the price and pays like the matching stake under the same cap, with no extra-reward bucket. The stability vault releases 250% of the order; minimum 500 USDT; GD reward vests linearly over 30 weeks; claims go through the turbine.
Data Analysis page on the dApp. The DAO page notes that its figures are the last rebase snapshot, not real time.
Compare the first four and the last four characters with the explorer page, and check the token name the wallet reads: Rome for RM, Gladiator for GD. RM and GD addresses as posted by Anubis Chain support on 13 September 2026 and matched to the explorer on 9 November 2026; the pegged USDT and DAI addresses as printed in the chain's 100 Questions. If an address in a chat differs from these, the chat is wrong.
| Contract | Address | On the explorer | Transactions | Token transfers | |
|---|---|---|---|---|---|
| RM token (Rome) | 0x2e045e1380f5f5b6e7550328910a7377c9fce59d | contract · source not verified · Rome | 3,206,260 | 112 | |
| GD token (Gladiator) | 0x21b6b0b3fab224921d3054d187e324a673411b4c | contract · source not verified · Gladiator | 6,104 | 6 | |
| USDT (pegged) | 0xDfb6a28BC6DC51fed17c27C880F2c66cDd040A3e | contract · source verified · HyperlaneSyntheticToken | 2,999,241 | 74 | |
| DAI (pegged) | 0x83fd06F0846d9D90B3016bF670Efe2E0B11cDe14 | contract · source verified · HyperlaneSyntheticToken | 6,391,028 | 799 | |
| Treasury | 0x4A9f64917Bd06ffcB03b2910445b451C04e3f2A1 | contract · source not verified | 43 | 31,879 | |
| Flexible staking | 0x52eAF5237522cd96cDa342C640571c34A7aA3740 | contract · source not verified | 2,007,174 | 4,107,014 | |
| 180-day staking | 0x726CD25cd37fCD2D0dcf9Fa56059CCb542f80197 | contract · source not verified | 620,974 | 1,246,412 | |
| 360-day staking | 0x84BAfF07E17E8d8563585beE533A92a193E1AfC5 | contract · source not verified | 139,503 | 204,877 | |
| 540-day staking | 0x99F715628b35E5b4FECEB26420543e3E704ad98b | contract · source not verified | 1,232,394 | 2,407,343 | |
| 180-day liquidity bond | 0x1f3553461FD62b4aedF19c5Cc7bD5d3B151cCd2D | contract · source not verified | 24,784 | 16,023 | |
| 360-day liquidity bond | 0x7F8a46274e50249E76Bd49ff819030353ee0F54D | contract · source not verified | 26,367 | 23,164 | |
| 540-day liquidity bond | 0xB2e97AC63d4ee96C68d4d769282e1fF10950Bc11 | contract · source not verified | 198,841 | 722,452 | |
| 180-day long-term fixed bond | 0xC3462e1052A4150Beb5aBe0402383111b1A878aA | contract · source not verified | 18 | 0 | |
| 360-day long-term fixed bond | 0xB1Ea4aa45DD751512F2f80F88f90A021c2842689 | contract · source not verified | 12 | 0 | |
| 540-day long-term fixed bond | 0x7E171bFb09A4A5Ec23E0C713C82Cf0BD31fcFCB0 | contract · source not verified | 10 | 0 | |
| Burn contract | 0x7bAfD7622f137Fa9cDDaf304cd58CA28c3eA758A | contract · source not verified | 25,172 | 0 | |
| Community rewards | 0xE691522f79Cf30C82DAbDadebE04F2348690f351 | contract · source not verified | 597,889 | 1,162,398 | |
| Turbo (1:1 engine) | 0xf9A76fF9AAcA29deA56B57c21de0C0E31f36C4Cd | contract · source not verified | 3,367,109 | 13,253,148 | |
| Activity score management | 0x377f3416262c4320318aC053Bd4CD2BfAED5C6da | contract · source not verified | 4 | 0 | |
| Stable vault | 0xabFe1C8b66D64Bc96645b5811aD1d2636b4473E7 | contract · source not verified | 3,426 | 3,908 | |
| Charge incentive pool | 0x0c52A0ac4c59b5144DB1E92755137138995d53Fd | Not a contract on the explorer: a plain address, no transactions of its own, 163 token transfers received. Unconfirmed; send nothing to it and ask the project. | 0 | 265 |
Twenty of the twenty-one addresses are contracts with live histories: the Turbo contract alone has passed three million transactions, the flexible pool two million. The charge incentive pool address is not a contract on the explorer and is marked above. Source code is verified on the explorer for the USDT and DAI token contracts only (Hyperlane synthetic tokens); RM, GD and every product contract are deployed with public bytecode and public transactions, and their readable source is not published. A reader can watch every transaction; they cannot yet read the rules in the code. Say so when asked, and note that the project can change it by verifying the contracts.
A member who wants to see where their stake went opens the staking contract for their term on the explorer and finds their own transaction. A member who is sent an address in a chat compares it with this table: the first four and the last four characters, then the name the explorer shows. The English list circulated on 26 September carried a stray space inside the 540-day liquidity bond address; the address above is the one on the explorer.
Spartan OS · contract addresses as published by the project's service accounts, 25 and 26 September 2026 · checked on browser.anubispace.org on 9 November 2026

RM token (Rome): 0x2e045e1380f5f5b6e7550328910a7377c9fce59d
GD token (Gladiator): 0x21b6b0b3fab224921d3054d187e324a673411b4c
USDT (pegged): 0xDfb6a28BC6DC51fed17c27C880F2c66cDd040A3e
DAI (pegged): 0x83fd06F0846d9D90B3016bF670Efe2E0B11cDe14
Treasury: 0x4A9f64917Bd06ffcB03b2910445b451C04e3f2A1
Flexible staking: 0x52eAF5237522cd96cDa342C640571c34A7aA3740
180-day staking: 0x726CD25cd37fCD2D0dcf9Fa56059CCb542f80197
360-day staking: 0x84BAfF07E17E8d8563585beE533A92a193E1AfC5
540-day staking: 0x99F715628b35E5b4FECEB26420543e3E704ad98b
180-day liquidity bond: 0x1f3553461FD62b4aedF19c5Cc7bD5d3B151cCd2D
360-day liquidity bond: 0x7F8a46274e50249E76Bd49ff819030353ee0F54D
540-day liquidity bond: 0xB2e97AC63d4ee96C68d4d769282e1fF10950Bc11
180-day long-term fixed bond: 0xC3462e1052A4150Beb5aBe0402383111b1A878aA
360-day long-term fixed bond: 0xB1Ea4aa45DD751512F2f80F88f90A021c2842689
540-day long-term fixed bond: 0x7E171bFb09A4A5Ec23E0C713C82Cf0BD31fcFCB0
Burn contract: 0x7bAfD7622f137Fa9cDDaf304cd58CA28c3eA758A
Community rewards: 0xE691522f79Cf30C82DAbDadebE04F2348690f351
Turbo (1:1 engine): 0xf9A76fF9AAcA29deA56B57c21de0C0E31f36C4Cd
Activity score management: 0x377f3416262c4320318aC053Bd4CD2BfAED5C6da
Stable vault: 0xabFe1C8b66D64Bc96645b5811aD1d2636b4473E7
Charge incentive pool: 0x0c52A0ac4c59b5144DB1E92755137138995d53Fd  (not a contract on the explorer on 9 November 2026; unconfirmed)
Two calculators. The first takes an amount and a product and shows what it pays, when it reaches its cap, and how every product compares for the same amount. The second takes your own position and your legs, finds the rank, and shows what the community pays for two, three, four, five or six legs of the same volume. Every assumption is written next to the number it changes.
Side-by-side figures use each product's rate and cap as shown on , with no compounding, claimed daily, at the assumed RM price. Days to cap counts the capital inside the cap, as confirmed on 26 September 2026. Extra rewards, energy and GD are stated where the product carries them.
Each card re-splits your current total team volume into that many equal legs and applies the same rules. The large zone qualifies; the small zone (every other leg together) is what the DAO reward is paid on. More legs put more of the same volume into the small zone, as long as the largest leg still clears the threshold.
Reference rows assume the small zone sits exactly at the requirement. Personal stake, nodes and ecosystem size as printed on page 16 of the Economic Model Analysis, except V12: 50,000 USDT as confirmed on 26 September 2026 (the 25,000 on that page is not to be used, and there is no separate governance-weight parameter). Bands are paid within the range by the AICS score. Level income and the three bonus lines are on top and depend on the team.
The Spartan OS team issued four rank models on 3 November 2026: what each rank takes, how the team lays the lines out, and what that layout pays in their example. Open an image to read it full size. The qualifications match the rank table on slide 11; the earnings are the team’s illustration, not a promise of return.
Every earnings figure in the images assumes 0.6% every twelve hours held for ninety days, the static earnings of your stake and of every line compounded into the principal, and RM fixed at $30. Rates float and the dApp is the reference; long-term positions end at their cap of 4×, 4.5× or 5×, fixed at entry. The 8% direct reward is counted on the whole volume of every line, as if each line were one person: volume deeper in a line pays 4% or 2% for the next two levels and no level income after that, so a real team of the same size earns less than the model shows. The total layout value adds your team’s assets to your own; it is not yours and it cannot be withdrawn, as the team’s own note says. Day one of each model checks out at the stated rate. Nothing here is a promise of return; actual results depend on the dApp’s rules and on-chain settlement.
The team’s layout A $10,000 · B $4,000 · C $3,000 · D $3,000 · total $20,500 with your own stake
Day one in the model: $34.90 a day, from your stake, the DAO reward on the small zone and 8% direct reward on all four lines.
The team’s layout A $50,000 · B $20,000 · C $15,000 · D $10,000 · E $5,000 · total $101,500 with your own stake
Day one in the model: $186.56 a day, from your stake, the DAO reward on the small zone and 8% direct reward on all five lines.
The team’s layout A $150,000 · B $40,000 · C $40,000 · D $35,000 · E $35,000 · total $303,000 with your own stake
Day one in the model: $595.78 a day, from your stake, the DAO reward on the small zone and 8% direct reward on all five lines.
The team’s layout A $300,000 · B to F $60,000 each · total $605,000 with your own stake
Day one in the model: $1,360.07 a day, from your stake, the DAO reward on the small zone and 8% direct reward on all six lines.
Read V4 for the qualification and the layout. Its earnings rows from day 30 do not follow the 0.6% the model states and the other three use: it shows $2,572.89 a day at day 30, where 0.6% gives about $1,924, and $345,119.16 over ninety days, where it gives about $218,700. Do not quote V4’s earnings until the team re-issues the model.
Type a question in plain words. The answer comes from the 234 cards below, with the slide or page that shows it, and the source and date. No upline needed for the first answer.
Answers repeat what Spartan OS and Anubis Chain have stated, with the cap and the date. They never promise a return. If a question is not covered, the assistant says so; leave it through the feedback button and the next edition carries it.
The same cards the assistant reads. Open a question; the answer, the detail, the source and the picture are inside. Ten topics, from the chain to the news.
The chain: who built it, what runs on it, what makes it different.
Anubis Foundation, which publishes a footprint of two years, five continents, twenty countries and more than a hundred projects. Three of them matter here: Origin (DeFi 3.0 on LGNS), WebKey and Melos (16 million users, as stated), and Anubis Chain itself. Anubis Labs is the arm that funds projects on the chain, and Spartan OS is its first.
Most projects start from nothing: no users, no assets, no track record. This one starts with millions of holders who already know the foundation's name and a chain the foundation controls. Spartan OS runs 137 smart contracts on the codebase that ran Origin and Awake; the CertiK audit has been submitted. Foundation footprint as published at anubi.pro; Origin partnership announced by Anubis Foundation on 8 July 2024.
Source: Promoter deck, 26 October 2026, slide 2
That this foundation can build a market of millions and keep it alive. At its AVE snapshot Origin (LGNS) had 2.5 million holders, a $1.4 billion circulating market cap, a $200 million pool and 91,000 transactions in one day. Two years on, about $55 million is still in the Origin pool on Polygon.
These are historical figures, not today's prices. The point is the last one: two years later the pool is still there and people can still sell. Snapshot as supplied by Anubis Foundation, checkable at ave.ai; today's pool figure as stated in the 14 September 2026 briefing.
Source: Promoter deck, 26 October 2026, slide 3
Mainnet since April 2026, chain ID 6714. As published by Anubis Chain in September 2026: over 100 million transactions, over 18 million addresses, over 16,000 smart contracts, over 1,900 tokens, about one second per block. Fees are paid in gasDAI, pegged to the dollar.
Everything is on the public explorer at browser.anubispace.org. The chain is indexed by The Graph, explored through Blockscout and connected cross-chain through LayerZero, Stargate, Anubis Bridge and GaleBridge. Earlier presentations also cite 2,400+ transactions per second, a 450 ms block time and 21 active validators of 52 nodes; those are the project's own figures.
Source: Promoter deck, 26 October 2026, slide 4; Anubis Chain periodic data report, September 2026
When a project runs on someone else's chain, the gas, the rules and the future belong to someone else. Anubis Foundation built the chain, Anubis Labs funds what runs on it, and Spartan OS is the first application. Same people, same code, new chain.
A promoter can say it in one line: most projects rent a chain; this one owns it. It also means every figure about the chain and the project can be checked on one explorer, browser.anubispace.org.
Source: Promoter deck, 26 October 2026, slides 2 and 4
The unit Anubis Chain uses for transaction fees. It is pegged one to one to DAI, a dollar stablecoin, so a transaction costs the same on a quiet day and a busy one. A wallet shows a gasDAI balance where it would show ETH on Ethereum. A transaction costs a fraction of a cent.
On most chains a user must first buy the chain's own token to pay for anything, and that token's price moves. On Anubis the fee a user sees when they approve a transaction is the fee they pay, in dollar terms, on any day. gasDAI comes through the official bridge: bridge DAI and the destination balance is your gas. Never buy gasDAI from a person.
Source: Technical guide, September 2026, Part II and Guide 09
Both, by choice. Transactions are public by default, as on Ethereum. A user can shield a transaction: the amount and type stay visible, but sender and receiver identities are protected by a PLONK zero-knowledge proof. Anubis calls it selective disclosure: private for people, transparent for the protocol, workable for regulators.
A zero-knowledge proof lets the network confirm a transaction is valid, that the sender had the funds and that the rules were followed, without publishing who sent what to whom. Shielded transactions take a little longer because the proof is generated on the user's side. Everything a promoter does day to day uses ordinary transparent transactions.
Source: Long-form explainer, September 2026, Part II; Technical guide, September 2026, Part II
Pending transactions are encrypted before validators see them. At least two thirds of validators must cooperate to decrypt one, and only after its place in a block is fixed. A block producer cannot see your swap on RocketSwap and trade ahead of it. The design rules sandwich attacks out rather than discouraging them.
Sandwich attacks are the most common way retail traders lose money on decentralised exchanges. The mechanism uses BLS12-381 threshold cryptography, as described in the Anubis Network documentation.
Source: Technical guide, September 2026, Part II (Anubis Network documentation)
A fixed set of validators takes turns proposing blocks and a block is final once two thirds or more have signed it. There is no probabilistic finality and no reorganisation: once confirmed, a block does not change. Transparent transactions confirm in about a second.
The technical documentation describes an IBFT 2.0 variant with a validator set re-elected every 100 blocks by a verifiable random function. The docs.anubispace.org pages and the chain's own 100 Questions describe a Proof of Staked Authority design with staking, governance and slashing for double signing or downtime, and a theoretical capacity of about 2,000 transactions per second. Quote whichever you can show, and say where it comes from.
Source: Technical guide, September 2026, Part II; Anubis Chain documentation (docs.anubispace.org)
Yes, unchanged. Anubis runs the Ethereum Virtual Machine. Solidity contracts deploy as they are, MetaMask and every wallet that supports custom networks connect, and Hardhat, Foundry, Remix and ethers.js work as on Ethereum. A team does not rewrite; it redeploys.
For a user with Ethereum experience the only two new things are the chain ID, 6714, and the fee unit, gasDAI.
Source: Technical guide, September 2026, Part II
RocketSwap (the native exchange, Uniswap V2 design, listed on CertiK Skynet), two official bridges (Anubis Bridge and GaleBridge, the latter audited by CertiK in October 2025), the Blockscout explorer, The Graph indexing, LayerZero and Stargate routes, Capybara Launch, and wallet support in Bitget, OKX, TokenPocket, Binance Wallet and MetaMask.
This is the difference between a chain with a roadmap and a chain with a working economy. Bridgers is a third-party route that Anubis does not operate. Named partners as published by Anubis Chain: DeBox, DappOS, xBubble, Ads3, Golden Pact, REI Network, Bitget Wallet, GoPlay.
Source: Long-form explainer, September 2026, Part II
Anubis Chain states that every officially bridged asset is minted one to one when the native asset is locked in the official asset-pegging bridge on the source chain, and burned when redeemed, so the locked reserves match the supply on Anubis. The bridge contracts are public on Etherscan.
Official Asset-Pegging Main Bridge: 0x250ba4e73a365cefdd170a2b1ff9fc03097d64f3. Official Transaction Main Bridge: 0x8932fe7726C1EE743F662f485C3e5a5D1D595F71. A reader checks it by opening the Etherscan page, reading the balances the contract holds, and comparing them with the supply of the same asset on browser.anubispace.org. The statement is reproduced in full in the Official section of this page.
Source: Anubis Chain statement, 20 September 2026
The incubation arm of Anubis Chain. It selects projects to build on the chain, funds them and supports them through launch. Spartan OS is its first consumer project, which is why the two names appear together everywhere.
Anubis Foundation has announced a $300 million commitment to the Anubis Chain ecosystem; the Labs' own FAQ describes a $100 million incubation fund with 10,000 NFT incentive assets. Both figures are the project's own. Projects Labs names: Capybara Launch, RocketSwap, GaleBridge, AstraCore, AWAKE, Spartan OS, VEST, Golden Pact.
Source: Long-form explainer, September 2026, Part II
Privacy built on zero-knowledge proofs while the chain stays verifiable. AGI and AI-agent integration. A Layer 1 built to carry applications at scale. EVM compatibility, so existing tools and contracts move over. Asset transparency through the official bridge, asset contracts and the explorer. A global ecosystem of wallets, DEXs, data platforms and developers.
Two of the six can be checked by anyone today: EVM compatibility (chain ID 6714 on chainlist.org) and asset transparency (the bridge contracts on Etherscan). The AGI integration is a direction, not a shipped feature; say so. Infographic issued 1 July 2026.
Source: SpartanOS Resource Library (t.me/SpartanOSLibrary), 1 July 2026
On eight points, in its own infographic: positioning (AGI privacy chain against a plain transaction network), privacy (zero-knowledge proofs with selective disclosure against basic transparency), intelligence, asset range (RWA and DeFi together), data trust (reserves and cross-chain records verifiable), ecosystem coordination, developer support and long-term scalability.
The table is reproduced in full in the Compared section. It is Anubis Chain describing itself and a generic competitor; quote it as the project's positioning. The chain's verifiable differences are simpler to defend: dollar-pegged gas, the encrypted mempool, selective privacy and one-to-one bridge reserves on public contracts.
Source: SpartanOS Resource Library (t.me/SpartanOSLibrary), July 2026
The 100 Questions document says the team formed in 2024 and consists of anonymous community developers around the world, maintaining the network under decentralised governance, and that anonymity protects the project's neutrality and the developers' security. Anubis Foundation and Anubis Labs are the public faces: the foundation for the chain, Labs for the projects on it.
Two descriptions exist and both are the project's own: the promoter material names Anubis Foundation and its earlier projects; the FAQ describes an anonymous developer collective. A promoter should give both and not pretend to know more. Named people: none published.
Source: Anubis Chain 100 Questions and Answers, official, July 2026, Q2 and Q3
Proof of Staked Authority: a mix of delegated proof of stake and proof of authority. Validators put up a stake, the ones with the most stake form the active set, and they take turns producing blocks and voting. Misbehaviour such as signing two blocks is punished by slashing, with an unbonding period so a validator cannot leave before a penalty lands. Blocks confirm in about a second.
Theoretical capacity is stated at about 2,000 transactions per second; real throughput depends on load. Three node types exist: fast, full and archive. Validator recruitment was not yet open in July 2026; the documented minimum self-delegation is 2,000 DAI. The client is Geth-compatible, which is why Ethereum tooling works unchanged.
Source: Anubis Chain 100 Questions and Answers, official, July 2026, Q11 to Q21
Not yet. As of July 2026 no native token has been issued; fees are paid in gasDAI, which comes from bridged DAI. The FAQ's governance answer describes a future ANB token with a 21 million supply as the chain's gas token, and names LGNS as the ecosystem's value anchor with a staking rate it puts above 87%. Treat ANB as planned, and quote nothing about it as live.
Anyone selling 'Anubis coin' today is selling something the chain says does not exist. The tokens that do exist on the chain are pegged assets (USDT, USDC, DAI, ETH, BNB, POL, LGNS) and project tokens such as RM and GD.
Source: Anubis Chain 100 Questions and Answers, official, July 2026, Q22, Q28 and Q75
Day 103 (20 July): 12.13 million addresses, 38.49 million transactions, TVL $189.91 million. 8 August: 14.10 million addresses, 57.78 million transactions. Day 137 (22 August): 15.61 million addresses, 74.73 million transactions, 1.079 million in 24 hours. Day 155 (10 September): 18.19 million addresses, 102.93 million transactions, 16,533 contracts, one-second blocks, gas below $0.01.
All figures as published by Anubis Chain on those dates; the live counters are on browser.anubispace.org. Addresses are not people: one person can hold many. Quote the transaction count and the date, and let the explorer do the rest.
Source: Announcement reproduced in the SpartanOS Resource Library, 22 July, 8 August, 22 August and 10 September 2026
On 26 July 2026 Anubis Chain cited DEXTools' hot-pairs data as ranking AnubisChain 12th among public chains by total trading volume and 10th by liquidity. Rankings move daily; open dextools.io/app/hot-pairs before quoting one.
A ranking is a snapshot taken by a third party on one day. Say the date. The DEXTools integration itself dates from 19 April 2026, according to the FAQ.
Source: Announcement reproduced in the SpartanOS Resource Library, 26 July 2026; Anubis Chain 100 Questions and Answers, official, July 2026, Q76
AVE.ai cross-chain and swap (15 June). CoinGecko listing as a public chain (23 June). The partner matrix of 26 June: CoinMarketCap, CoinGecko, DEXTools, Bitget Wallet, MyToken, Ave.ai, dappOS, RocketSwap, AuraOS, Ads3, Spartan OS, VEST. Bitget Wallet gas subsidy (7 July). AstraCore's AC Wallet (26 July). LayerZero and the OFT standard (31 July). The Graph subgraph support (15 September). Gold sponsor at TOKEN2049 Singapore, 7 to 8 October.
Each is an announcement by Anubis Chain with a link in the News section. A listing on a data site is not an endorsement; an integration is a technical fact a reader can test. LayerZero's own announcement had not been published when this page was built.
Source: Announcement reproduced in the SpartanOS Resource Library, June to September 2026
The first genesis-level ecosystem project on Anubis Chain. On 13 May 2026 it launched the DAI/LGNS pair on RocketSwap through a Capybara Launch ILO, with an initial pool the project states at about $163 million. Anubis calls that pool the liquidity anchor of the chain.
AWAKE is the precedent Spartan OS follows: a Labs project, a Capybara launch, a RocketSwap pair. Its NFT is named in the Q3 blueprint as the chain's digital identity. Figures as stated by Anubis Chain.
Source: Anubis Chain 100 Questions and Answers, official, July 2026, Q66 and Q73; Announcement reproduced in the SpartanOS Resource Library, 22 July 2026
Labs describes a $100 million ecosystem fund and 10,000 ANUBIS NFT incentive assets, three grant models (DEX liquidity, CEX listing, community growth) and a 3A structure: Accelerator, Alliance, Amplifier. Projects it names as incubated or supported: Capybara Launch, RocketSwap, GaleBridge, AstraCore, AWAKE, Spartan OS, VEST, Golden Pact. Applications go to bd@anubislabs.us.
The promoter material also cites a $300 million commitment by Anubis Foundation; the FAQ's figure is $100 million for the Labs fund. Both are the project's own. Priority sectors: privacy infrastructure, AI agents, DeFi, RWA, SocialFi and prediction, DEXs and wallets, DePIN and payments.
Source: Anubis Chain 100 Questions and Answers, official, July 2026, Q88 to Q100
Five directions in parallel: keep strengthening the infrastructure (mainnet, bridges, explorer, wallets, DEX liquidity, developer tools); integrate AGI and AI agents into on-chain applications; expand RWA and on-chain finance; grow the global developer network; form an intelligent on-chain economy. The Q3 2026 blueprint named eight areas for the quarter, from omnichain interoperability to AI and RWA integration.
A plan is a plan. None of the five carries a date, and the FAQ's roadmap answer says the same five things in different words. Say what has shipped (the chain, the bridges, the DEX, the first applications) and what is planned, separately.
Source: SpartanOS Resource Library (t.me/SpartanOSLibrary), 1 July 2026; Announcement reproduced in the SpartanOS Resource Library, 18 August 2026
Through Bitget Wallet, yes, within limits: since 7 July 2026 Anubis Chain subsidises up to three zero-gas transfers a day inside AnubisChain, at most 0.1 gasDAI each, for eligible transactions made in Bitget Wallet. Cross-chain transactions are excluded.
A subsidy campaign can end; check the wallet's campaign page. For everything else, bridge a few dollars of DAI once and the wallet holds gasDAI for thousands of transactions.
Source: Announcement reproduced in the SpartanOS Resource Library, 7 July 2026
AstraCore Wallet, an AGI-Web3 wallet that integrated AnubisChain on 26 July 2026. Spartan OS calls it the officially recommended and strategic wallet partner of AnubisChain. Official download for iOS and Android: api.astracorewallet.app/website/download, as published by Anubis Chain. Anubis has said it will build Web3 social modules with AstraCore rather than a separate app.
Two wallets are recommended in official material, then: Bitget Wallet (the chain built in, gas subsidy) and AC Wallet (strategic partner, campaign gateway). The AC Carnival airdrop of 1,000,000 DAI ran from 12 August to 11 September and has ended; a 30,000 DAI daily incentive was announced on 8 September. Do not promise any campaign; check the current one.
Source: Announcement reproduced in the SpartanOS Resource Library, 26 and 29 July, 8 September 2026
Yes. On 7 August 2026 Anubis Chain and DappOS published an AI question-and-answer page covering the mainnet, wallets, security, privacy, swap and bridge, with answers drawn from sources the project approved: anubis-ai-web-production.up.railway.app. This page's assistant does the same for Spartan OS.
Type the address rather than following it from a chat, and treat what it says as the project's view. For anything that moves money, the explorer and the official bridge pages remain the reference.
Source: Announcement reproduced in the SpartanOS Resource Library, 7 August 2026
Yes. Chain ID 202601, RPC and explorer at cheras-rpc.anubispace.org, test tokens from the faucet contract on request to an administrator. Developer documentation lives at github.com/anubis-chain/docs. Solidity 0.8.x and Vyper are supported; Remix, Hardhat and Foundry work as on Ethereum.
Source: Anubis Chain 100 Questions and Answers, official, July 2026, Q70 to Q72
Anubis Chain states that since the mainnet launch on 8 April 2026 neither the chain nor its official bridge contracts have suffered a successful breach, and that no user assets have been lost to a contract flaw or network attack. CertiK and Armor audited 137 core contracts (announced 13 July 2026).
A clean five-month record is a fact about five months. Bridges remain the most attacked component in the industry; the FAQ itself lists the bridge's defences (message verification, daily limits, allowlists, emergency pause) and still tells users to test with a small amount first.
Source: Anubis Chain 100 Questions and Answers, official, July 2026, Q78 and Q79; Announcement reproduced in the SpartanOS Resource Library, 13 July 2026
Three names, one group. Anubis Foundation is the organisation: it built Origin (LGNS), WebKey and Melos, and then its own Layer 1. Anubis Chain is that chain: mainnet since April 2026, chain ID 6714, fees in gasDAI, the explorer at browser.anubispace.org. Anubis Labs is the incubation and funding arm that selects and funds projects on the chain; Spartan OS is its first consumer project.
When a person asks who is behind Spartan OS, answer in that order: the foundation with a record, the chain it owns, the arm that funds what runs on it. The foundation's published footprint is two years, five continents, twenty countries and more than a hundred projects, and a $300 million commitment to the ecosystem (an earlier figure was $100 million); the 100 Questions describe the chain's developers as an anonymous collective. Official channels: anubischain.ai, @AnubisChainL1 (primary since 16 September), @ANUBISCHAIN_ (earlier record), @Anubis_Labs, anubislabs.us, the AC Wallet and the Resource Library.
Source: Promoter deck, 26 October 2026, slides 2 to 4; Anubis Chain 100 Questions and Answers, July 2026; Anubis Labs pages
Origin (LGNS): at its AVE snapshot 2.5 million holders, a $1.4 billion circulating market cap, a $200 million pool and 91,000 transactions in one day; two years on, about $55 million still sits in the Origin pool on Polygon. WebKey and Melos: 16 million users, as stated. Awake: a further application on the same codebase. Anubis Chain: over 100 million transactions, 18 million addresses and 16,000 contracts by September 2026, a CertiK and Armor verification of 137 core contracts, a GaleBridge audit by CertiK, a partner list that includes Bitget Wallet, DappOS, GoPlay, The Graph and LayerZero, and a gold sponsorship at TOKEN2049 Singapore in October 2026.
Every figure is the project's own except the ones on a public explorer: the Origin pool on Polygon, the chain's transaction count, the bridge reserves on Etherscan and the audits on skynet.certik.com. Say which is which. What is not public: the names of the people, which the foundation has chosen not to publish.
Source: Promoter deck, 26 October 2026, slides 2 to 4; Anubis Chain data reports, August to September 2026; News section
Five on Telegram, listed by the Spartan OS service account on 26 September 2026: English @SpartanOSLibrary, Chinese @SpartanOSResourceLibraryCN, Korean @SpartanOSKoreanLibrary, Japanese @SpartanOSJapaneseLibrary and Vietnamese @SpartanOSVietnameseLibrary, plus a Chinese library on DeBox. All are in the Links section.
Send a Korean or Vietnamese member their own library rather than a translation of yours. Hindi materials were promised by the project on 25 September and are not yet published; until they are, the English library is the reference for India.
Source: Spartan OS service account, 26 September 2026; each address opened and checked the same day
The first application: five systems, two tokens, TempleRaid.
The first application on Anubis Chain, built by Anubis Labs to give people a reason to use the chain today and come back tomorrow. Two tokens, RM and GD. A live game, TempleRaid. Staking paid every twelve hours. Live since 16 June 2026.
The team describes it as an operating system for on-chain entertainment and AI: five systems that share users, tokens and distribution. Two are live (the user gateway, through TempleRaid, and the Agent Token Hub, through RM, GD and the Token Router); three are planned (AI distribution, the compute engine, the developer network).
Source: Promoter deck, 26 October 2026, slide 5; Long-form explainer, September 2026, Part III
Live: the user gateway (TempleRaid) and the Agent Token Hub (RM, GD and the Token Router). Planned: AI distribution, the compute engine and the developer network. Say two live, three planned. It is a stronger position than implying all five exist.
The gateway is on-chain games and applications built for frequent return. AI distribution is a recommendation layer that puts the next relevant application in front of a user. The compute engine pools processing power for AI tasks. The Agent Token Hub is where AI agents are created, tokenised, called and settled. The developer network brings third-party teams onto Anubis through Spartan OS. No dates have been announced for the planned three.
Source: Long-form explainer, September 2026, Part III; Spartan OS infographic, June 2026
RM is the ecosystem token: the one you earn, stake, spend in applications and trade on RocketSwap against USDT. GD is the governance token: 390,000 units, fixed, with voting rights in Spartan OS. Both are accepted in TempleRaid.
The split is deliberate. A platform that uses one token for both spending and governance ends up with a governance body that changes every time the price moves. RM circulates; GD, with a small fixed supply, stays with people who have a longer interest. GD is obtained on the open market or through the burning bond's 3% airdrop. Contract addresses: RM 0x2e04…e59d, GD 0x21b6…1b4c, in full under Terms today and verified on the explorer on 24 September 2026.
Source: Long-form explainer, September 2026, Part V
$29 million USDT in the RM liquidity pool, 500,000 RM holders, 68% of RM supply staked on-chain, a $10 million USDT treasury, RM supply 6.1 million. RM opened at $18.85 on 16 June and was stated above $30; GD opened at $40 on 4 May and was stated at $16,000.
Say 68% staked twice. It means two out of three tokens are locked and earning rather than waiting to be sold. That is the number a sceptic cannot argue with. All figures as stated by Spartan OS on 14 September 2026; check the explorer, the DEX and the dApp for today's values.
Source: Promoter deck, 26 October 2026, slide 5; Spartan OS briefing, 14 September 2026
The first Spartan OS application, launched on 6 September 2026 with games partner GoPlay. A sixty-second on-chain round: connect a wallet, choose an asset (RM, GD or another ecosystem asset), enter, and the outcome is drawn from verifiable randomness and settled on Anubis Chain. Anyone can check any round on the explorer.
The game is deliberately plain: no character to level, no inventory, no tutorial. The complexity lives in the chain. Say this every time: games of chance carry risk, and a player can lose what they enter. Nothing in TempleRaid is a promise of return.
Source: Long-form explainer, September 2026, Part IV; Technical guide, September 2026, Guide 12
The mechanism behind the Agent Token Hub. A builder turns an AI agent into a service with its own token; the router connects creation, token issuance, invocation, settlement and incentives into one path, all recorded on Anubis Chain. When the agent earns, revenue settles to the token's holders.
Today an AI service is a subscription or an API key: the money stops at the company. The router replaces that with a token. Announced on the Spartan OS X account; mechanics beyond the five stages have not been published. Describe what has been announced and stop there.
Source: Long-form explainer, September 2026, Part IV
Every platform that has succeeded with consumers got there through something people did for pleasure. A game gives high-frequency interaction, a low barrier and a fast feedback loop. Each round is a transaction, each transaction is a data point for the distribution layer, and each returning player is a user the next application inherits.
GoPlay brought an existing audience and distribution; Spartan OS brought the chain, the tokens and settlement. That is how the first users arrived without a cold start.
Source: Long-form explainer, September 2026, Part IV
Anubis Chain has one consumer application today and the roadmap names a second and a third. Leaders who build now inherit every user those applications bring. Five months old, as the deck says, is not five months late.
Do not oversell scarcity. State it once: the second application is coming, and the people who built their team under the first one are the people it lands on. Dates for the second and third application are the project's to confirm.
Source: Promoter deck, 26 October 2026, slide 14
Phase one, now: mainnet (April 2026), RM and GD (live), TempleRaid with GoPlay (6 September 2026), AI distribution (no date). Phase two: second and third applications, the compute service network and the developer programme, no dates. Phase three: the compute engine as infrastructure for the whole chain.
Where the material shows [date], no date has been announced. Do not fill it in. A promoter who states a date the project has not given is making a promise on the project's behalf.
Source: Long-form explainer, September 2026, Part VI
Entertainment gateways on one side (Steam: 132 million monthly active users) and AI agent tokens on the other ($3.4 billion category capitalisation and $780 million daily volume at the time of the Spartan OS deck). Industry projections put the AI market at $3.5 trillion by 2033.
These are context figures, not Spartan OS figures. They describe the size of the rooms it wants to be in. 'The AI market will be $3.5 trillion' is a fact about the AI market, not a fact about RM. Check the live number before quoting one.
Source: Long-form explainer, September 2026, Part VI (sources as cited by Spartan OS)
Web3 is moving from an asset network to an application network, and entertainment is the highest-frequency door in. Spartan OS is built as five capabilities on AnubisChain: an entertainment entry, an AI growth engine, an AI Agent Token Hub, an AI compute engine and a developer ecosystem, on six technical layers. Two tokens: GD for governance, RM for incentives. Five roadmap phases, none dated.
The paper's own risk section says the platform should avoid revenue commitments and disclose risks. Use that line when someone asks what the project promises: the whitepaper promises a structure, not a return. Full document in the Official documents section.
Source: Spartan OS whitepaper, official, 2026
Thirty-one slides from the project: what Spartan OS is, the four systems (gateway, growth, service, compute), AnubisChain as the foundation (privacy Layer 1, PLONK proofs, EVM, low cost), the AI compute engine, the value loop, market context with its sources, Steam and Hugging Face as precedents, the builder network, growth indicators, five asset classes and a three-phase roadmap.
This is the project's deck; the promoter deck on this page is the fifteen-slide version built for Zoom. Present the official one to a technical or institutional audience. Market figures in it are third-party estimates as cited by Spartan OS.
Source: Spartan OS official deck, 31 slides, 2026
AnubisChain provides security, privacy, intelligence, assets, technology and global resources: the chain, the proofs, the bridges, the DEX, Labs and the partner network. Spartan OS provides users, applications, services, compute, developers and market growth: the entertainment entry, the token hub, the game, the community. One chain, one operating system, as the infographic puts it.
Source: SpartanOS Resource Library (t.me/SpartanOSLibrary), 9 July 2026
GD: governance token, total supply 390,000, used for platform governance voting, protocol parameter adjustment, prediction-market settlement and ecosystem value capture; positioned as the long-term governance right and core value carrier. RM: utility and reward token issued by an adaptive algorithm incentive engine, used for participation rewards, application benefits, community contribution bonuses, task incentives and growth rewards.
GD holds long-term rights; RM circulates every day. AICS scoring and the TriZone incentive engine sit beside the two tokens. The infographic of 26 June 2026 and the whitepaper's chapter 5 say the same thing.
Source: SpartanOS Resource Library (t.me/SpartanOSLibrary), 26 June 2026; Spartan OS whitepaper, official, 2026, chapter 5
Genesis Cornerstone Program 35%, phased release. Liquidity incentives 25%, released on the LP incentive cycle. DAO ecosystem rewards 10%, five-year linear release. Team and core contributors 10%, twelve-month cliff then 36 months linear. Ecosystem fund 10%, released by DAO governance on demand. Strategic partners 5%, 24 months linear. Agreement treasury reserve 5%, non-circulating.
The team's 10% cannot move for a year and then takes three more years to become transferable, as stated. Page 5 of the Economic Model Analysis. The due-diligence answers of 24 September 2026 add that the GD rights tied to the RM Stable Vault come out of this original allocation, the 25% liquidity-incentive share, released linearly over 30 weeks, and that the 5% treasury reserve is a risk reserve; the 390,000 maximum does not move.
Source: Spartan OS Economic Model Analysis, official deck, 2026, page 5
A programme for early participants: 10,000 Genesis NFTs worldwide, with four tiers and a target cycle multiplier for each: S1 Pioneer 3.5×, S2 Guardian 4.0×, S3 Vanguard 4.5×, S4 Spartan Elite 5.0×. Rights named: GD governance airdrop, DAO priority qualification, founding member status, weighted community rewards, airdrop priority, exclusive discounts.
How a tier is earned and what the multiplier applies to are not spelled out on the page. The same programme funded the Price Stability Fund in July 2026. Page 8 of the Economic Model Analysis.
Source: Spartan OS Economic Model Analysis, official deck, 2026, page 8
A fund of 1,000,000 USDT, allocated on 10 July 2026 from round 3 of the Genesis Foundation Program, to be used only to steady the RM market price, improve liquidity and act during abnormal volatility. Address published: 0x2aF89Eb5c0b8c689845E8Ae5bd15c03072F00635. The Foundation says it operates under the programme's rules and accepts DAO and community oversight.
A stability fund is money the project can spend on the market; it is not a floor under the price, and the announcement does not claim one. A reader can watch the address on the explorer.
Source: Announcement reproduced in the SpartanOS Resource Library, 10 July 2026
An airdrop pool announced on 4 August 2026. Users whose single participation exceeds 200 USDT in 360 or 540-day long-term staking, 360 or 540-day bonds, or the RM Stable Vault (2.5×) qualify for irregular airdrops from what the announcement calls the Bottom-Fishing Incentive Pool. Timing and rules are set by official announcement.
Irregular means irregular. Present it as a possibility attached to long-term positions, never as a rate. The dApp's function pages carry the current rules.
Source: Announcement reproduced in the SpartanOS Resource Library, 4 August 2026
Yes. Anubis Labs announced on 2 August 2026 that Spartan OS completed a CertiK security assessment covering the governance multisig, treasury, staking, reward distribution and core token contracts: zero critical findings, zero major, and all three medium findings resolved.
Earlier promoter material said the audit had been submitted; the completion announcement supersedes it. Ask for the report link on skynet.certik.com before repeating the result to a sceptic.
Source: Announcement reproduced in the SpartanOS Resource Library, 2 August 2026
Spartan OS calls TempleRaid the first perpetual insurance-backed blockchain game: 25 grids, a sixty-second round, on-chain randomness, and a line that reads 'lose and remain protected by the insurance mechanism'. How much the insurance returns, and from what pool, has not been published in the material available here.
Do not fill the gap. Say what the announcement says and that the mechanism's terms are the project's to publish. A game of chance with partial insurance is still a game of chance. Assets accepted: RM, GD, DAI, USDT.
Source: Announcement reproduced in the SpartanOS Resource Library, 3 and 5 September 2026
DappOS is a strategic AGI partner of Anubis Chain and Spartan OS. In August 2026 Spartan OS ran an airdrop of DappOS's token DOS for long-term positions: 360-day staking or bonds from 500 USDT earned an extra 1.5% in DOS, 540-day earned 3%, in multiples of 500 USDT. It closed on 31 August. DOS listed on 11 August on Upbit, Binance Alpha, Bitget, OKX and Gate, as announced.
A closed campaign is history, not a pitch. Mention it as an example of what long-term positions have received, and say clearly that no future airdrop is announced.
Source: Announcement reproduced in the SpartanOS Resource Library, 1, 3, 4, 11 and 31 August 2026
5 September 2026: RM/USDT liquidity 28,153,200 USDT, ecosystem reserve 4,000,000 USDT, RM stated at $25.122 rising to $29.9639. 13 September: liquidity about 29.03 million USDT, reserve 4 million, total capital base stated at 33 million+, RM back above $30 after a fall from $32.84 to $25.12. The 14 September briefing put the pool at $29 million.
The same posts state targets: $33 million next, $90 to $100 million by year end, RM at $40 and $50. A target is the project's ambition, not a figure; quote the figures with their dates and leave the targets out. Live liquidity is on geckoterminal.com and the RocketSwap pool page.
Source: Announcement reproduced in the SpartanOS Resource Library, 5 and 13 September 2026
When community rewards are claimed into the turbo pool, energy is consumed one to one: a user can release rewards up to the energy they hold. Energy comes from long-term staking (a 360-day position carries 150% energy value, a 540-day position 200%) or from burning tokens, which earns energy in a range the deck gives as 200% to 600%, set dynamically.
The 150% and 200% on this page are superseded: on 26 September 2026 the project said the live dApp parameters are the final reference (energy staking 260%, RM burning 557% that day, both dynamic and adjustable by the protocol) and that neither this page nor the 2 to 6 times range in the due-diligence answers should override them. Page 17 of the Economic Model Analysis, kept for the mechanism, not the multiples.
Source: Spartan OS Economic Model Analysis, official deck, 2026, page 17
The official name for what promoters call the turbine. Rebase and community rewards are deposited into the turbo trading pool on receipt; the protocol automatically buys RM one to one with the rewards received, and the purchased tokens are locked once the purchase completes. Every payout becomes a purchase.
Source: Spartan OS Economic Model Analysis, official deck, 2026, page 19
Buying 0%, selling 5%, split four ways: 0.5% platform fund (operations and technical maintenance), 1.2% repurchase fund (buying back and burning GD and RM), 1.3% community development fund, 2.0% ecosystem fund (reserves and expansion). Default repurchase ratio: GD 0.6%, RM 0.6%, adjustable with market conditions.
Source: Spartan OS Economic Model Analysis, official deck, 2026, page 20
The Spartan OS at-a-glance page lists twelve levels by personal holding, direct referrals, community volume and reward band: V1 500 USDT, 3 directs, 10,000 community, 5% to 10%; V2 1,500, 4, 50,000, 8% to 15%; V3 3,000, 5, 150,000, 10% to 20%; V4 5,000, 6, 300,000, 15% to 25%; V5 7,000, 8, 600,000, 20% to 35%; V6 9,000, 10, 1,200,000, 25% to 45%; up to V12 at 50,000, 20 directs, twice V11's volume, 85% to 100%.
The reward column is a percentage band, not a daily dollar figure. The promoter deck's daily amounts for V1 to V5 are the leaders' translation of these bands at the rates of 7 September; the bands are the official statement. The Economic Model Analysis names the levels Recruit through Spartan King.
Source: SpartanOS Resource Library (t.me/SpartanOSLibrary), 17 June 2026; Spartan OS Economic Model Analysis, official deck, 2026, page 16
The three-layer incentive structure behind level income. Core Zone: direct contribution, 8%. Coordination Zone: community collaboration and team growth, 4%. Ecosystem Zone: broader expansion and user reach, 2%. The whitepaper introduces it with AICS scoring as the way incentives move from static allocation to dynamic evaluation.
Source: Spartan OS whitepaper, official, 2026, section 5.5; SpartanOS Resource Library (t.me/SpartanOSLibrary), 17 June 2026
Eight points from the project's own table: liquidity (POL plus dynamic adjustment against POL alone), yield (a revenue cap and adaptive release against high rebase APY), market regulation (active strategy against self-balancing), stability (sentiment and data against unanchored support), supply (mint, burn and buyback against rebase expansion), risk control (protocol intervention against participant behaviour), governance (DAO plus multisig plus layered execution) and flexibility (dynamic parameters against fixed mechanisms).
The full table is in the Compared section. Olympus DAO did not write its column. Page 29 of the Economic Model Analysis.
Source: Spartan OS Economic Model Analysis, official deck, 2026, page 29
Content access hub (high-frequency interaction, user aggregation), AI growth engine (understand demand, improve distribution), AI agent and token hub (service orchestration, value circulation), AI compute engine (compute output, elastic scaling), developer ecosystem (open tools, expand scenarios). The same five systems as the whitepaper; two are live today.
Source: SpartanOS Resource Library (t.me/SpartanOSLibrary), June to July 2026
The English-speaking community building Spartan OS on Anubis Chain around this library, named for the formation in which three hundred held a pass because each one covered the next. Four rules: every figure with its cap and its date, no promises of return, links from the official pages only, and unanswered questions go to a leader, not to a guess.
The channel is @spartanos_phalanx on Telegram (t.me/spartanos_phalanx). The referral link is in the Join section. Material is posted in the channel first and updated here.
Source: Phalanx Community, September 2026
On Telegram: @spartanos_phalanx (t.me/spartanos_phalanx). Announcements, the calls and the current material go there first; this page follows at each edition. The registration link is in the Join section, next to the channel.
A new person joins the channel first and registers only when they have decided. Send the channel, not the link, in a first message.
Source: Phalanx Community, 24 September 2026
The statement's two halves of the economy. Asset side: capital entering the protocol adds to protocol assets, liquidity, treasury and POL capacity. Token supply side: RM is minted, locked, released, bought back or burned under the rules of the protocol and the product used. The two interact and are not the same thing, so a deposit is not money that is divided and paid out as RM rewards.
This is the Olympus-style treasury-and-bond logic the project cites as its ancestor: future token supply is used to acquire assets and liquidity the protocol needs today. The honest way to present it is to name both sides in one breath, and to add the project's own caveat: minting alone solves nothing; the question is whether real demand absorbs the supply.
Source: Statement on how capital entering the protocol is treated, received 24 September 2026, reproduced in the Official section
As the project describes it: capital enters the protocol; it becomes protocol assets, treasury, POL or liquidity; RM is minted under protocol rules; that RM is locked and released in a controlled way; it meets secondary-market supply and demand; O² monitors the market; buyback, burn, protection and liquidity mechanisms respond; the system moves towards a new supply-demand equilibrium.
Nine steps, and the RM does not necessarily reach the open market at once. Between minting and the market sit locking, release, the 1:1 turbo demand, buyback and burn, and O². A promoter who can say this chain from memory answers most economic questions before they are asked.
Source: Statement on how capital entering the protocol is treated, received 24 September 2026, reproduced in the Official section
Protocol rules, network incentives and market balancing. The protocol rules layer fixes how assets enter, lock, mint and release: staking periods, bonds, release schedules and maximum reward multiples, which are not changed arbitrarily day to day. AICS is the network incentive layer and adjusts incentives to network health. O² is the market balancing layer and adjusts protection to market health.
The project's one-sentence version: AICS manages network health, O² manages market health. The protocol rules give the framework; effective incentives and protection parameters are not permanent fixed values and adapt through two feedback loops. Say that the mechanisms are designed to improve resilience, not to guarantee price or yield stability; the statement says so itself.
Source: Statement on how capital entering the protocol is treated, received 24 September 2026, reproduced in the Official section
Three assets, three jobs, as Spartan OS puts it. Stablecoins price, settle and bring capital in. RM is the high-frequency asset that runs through incentives, staking, bonds, liquidity, compounding, burns and the applications. GD is the scarce governance and long-term ecosystem-rights layer: a fixed maximum of 390,000 tokens that does not grow with users, TVL or applications. The project's own point is that a fast-circulating asset and the scarcest long-term rights should not be the same token.
The answer concedes what a sceptic will say first: a conventional governance token could be built the same way, so the name proves nothing. GD's difference has to be earned by attaching real governance rights, application utility and ecosystem participation to the fixed 390,000. Where GD comes from: early NFT holders' rights, predefined governance and ecosystem allocations, the GD rights tied to the RM Stable Vault, and the secondary market. The Stable Vault's GD is released linearly over 30 weeks out of the original allocation (the 25% liquidity-incentive share), not minted anew; the original structure also holds a 5% protocol-treasury risk reserve.
Source: Response to Seven Due Diligence Questions, received 24 September 2026, reproduced in the Due diligence section
Use, in the project's own words: scarcity alone creates no demand. The intended structure is fixed supply, limited acquisition, governance demand, application utility and ecosystem expansion together. TempleRaid is the first application bringing GD into play; further games, DeFi, RWA, DID and NFT systems and trading infrastructure are meant to add governance participation, application rights and permissions to the same 390,000 tokens.
Spartan OS names the metrics that would prove it, and the price is not among them: active GD addresses, ownership distribution, governance participation, the number of applications using GD, application interactions and on-chain usage. Its own test cuts both ways: if the ecosystem expands while GD usage does not, structural demand has not been shown. Say that sentence to a sceptic before they say it to you.
Source: Response to Seven Due Diligence Questions, received 24 September 2026, reproduced in the Due diligence section
The message Spartan OS now sends every new international partner before it talks about mechanisms or rates. Anubis Chain launched on 8 April 2026, Spartan OS opened to the market on 16 June, and the total capital foundation passed 35 million USDT after one complete cycle: fast growth, a correction, a period when confidence was tested, then the recovery the project calls U-shaped. The point of telling it first: the early communities learned their discipline in that cycle, and the project wants the international market to inherit the lesson rather than repeat the fall.
Read it whole once, then send the section link rather than a line from it. It carries its own limits: the 35 million is a stated total, the milestones after it are development goals, and the price is set by supply and demand. A promoter who quotes the recovery without the correction that preceded it is telling a different story from the project's.
Source: Harry (Spartan OS), 'From a U-shaped recovery to a global ecosystem', forwarded to the Phalanx channel on 26 September 2026, reproduced whole in the Official section
The project's own summary of what its early communities learned. On the way up, concentrated, large, disorderly selling can hurt liquidity and sentiment even while the protocol stays healthy, so the communities encourage rational, distributed, orderly trading. On the way down, they kept building: community development, market education, events, new participants. The six lines the project asks every market to hold: stay rational when the market rises; do not panic when it corrects; respect individual choice and respect the shared market; watch price, watch liquidity more; watch returns, watch the ecosystem too; think about today, build for tomorrow.
These are conventions, in the project's words, not rules in a contract. Say them as culture, never as a condition of membership. The one sentence to keep: in a shared liquidity market, individual actions can affect the wider ecosystem.
Source: Harry (Spartan OS), 'From a U-shaped recovery to a global ecosystem', forwarded to the Phalanx channel on 26 September 2026, reproduced whole in the Official section
To everyone who contributes to building the ecosystem: not to China, not to India, not to Dubai, not to any single community. The project describes the next stage as the world building together rather than one market leading another, with markets in China, India, the Middle East and Southeast Asia becoming connected parts of one market as the scale grows.
Useful when a member asks whether the international market is second to the Chinese one. The project's own answer is that the early communities built the foundation and are now passing their experience on; the formula it closes with is O² plus AICS plus ecosystem development plus community governance plus global consensus.
Source: Harry (Spartan OS), 'From a U-shaped recovery to a global ecosystem', forwarded to the Phalanx channel on 26 September 2026, reproduced whole in the Official section
Staking, bonds, the turbine. Every rate with its cap and its date.
Five streams, all paid every twelve hours, four of them open from $1. Flexible staking at 0.3% per twelve hours. Long-term staking at 1.1% to 1.3% a day for 180, 360 or 540 days. The burning bond at 1.5% a day net, from $500. Level income of 8%, 4% and 2% of the ROI on three levels. Rank rewards V1 to V12, paid daily from the DAO pool.
Rates as stated by Spartan OS on 7 and 14 September 2026. Rates float. Every long-term position has a cap fixed in USDT at entry. Every RM earned passes through the turbine before it reaches the wallet. Not a promise of return.
Source: Promoter deck, 26 October 2026, slide 6
From $1, no lock. 0.3% every twelve hours on your RM, about 0.6% a day, compounding by itself if left in. About 20% a month if untouched. Principal withdrawable at any time. No cap.
On $1,000: about $6 a day, about $180 a month, about $200 compounding. These are RM figures; the dollar result depends on the RM price on the day of sale. The published overview writes the rate as a band of 0.22% to 0.93%; the live rate on 7 September was 0.3% per twelve hours, floating.
Source: Promoter deck, 26 October 2026, slide 7; Leader document, September 2026, Part II
From $1, for 180, 360 or 540 days. Daily rate as stated: 1.1%, 1.2%, 1.3%. Cap on total payout: 4×, 4.5×, 5× of the entry value in USDT, fixed the moment you enter. The term and the cap are two separate limits, and the position ends at whichever comes first: on the last day of the term all rewards stop, cap reached or not, and the order does not extend itself (as stated by Spartan OS in writing on 16 October 2026; this replaces the 25 September reading that the position keeps paying until the cap). The capital is released second by second over the term together with the interest and the extra rewards, and all of it counts inside the cap: the principal is not paid on top (confirmed 26 September 2026).
On $1,000: $11, $12 or $13 a day; about $330, $360 or $390 a month at the stated rates. A long-term order shows three buckets: principal, interest and extra rewards, all claimable daily. Interest compounds every twelve hours if left in; extra rewards do not compound, so claim them daily. On 14 September the rates were quoted as over 1.0%, 1.1% and 1.2%. If the cap arrives before the term ends, the capital not yet released is frozen until a new order of the same term, larger than that remainder, is opened; see the card on the cap reached early.
Source: Promoter deck, 26 October 2026, slides 7 and 8; Leader document, September 2026, Part II
The most a position can ever pay out, all sources combined, set in USDT the moment you enter. $1,000 in at 540 days can pay out at most $5,000 of RM value: the capital, 1×, released over the term, and up to 4× in interest. At the cap the position stops paying. It also stops on the last day of its term, cap reached or not (as stated 16 October 2026). To continue, you open a new position. Flexible staking has no cap.
Lead with the cap. A rate without a ceiling is a story; a rate with a ceiling is a contract. Two limits, stated separately by Spartan OS on 16 October 2026: the term is the reward period and the cap is the ceiling, and the position ends at whichever comes first. Confirmed 26 September 2026: the capital is inside the cap. Principal and earnings are released together and both count towards the 4×, 4.5× or 5×; the principal is not an additional payment on top. At the stated rates the 360 and 540-day positions reach their ceiling in about ten to eleven months, before the term ends, and the capital still unreleased on that day is frozen until a new, larger order of the same term is opened; the 180-day position reaches the end of its term first, at about 3× of the entry, below its cap. The burning bond reaches its 2.5× in about five and a half months. The calculator applies that reading only. The leader document states the caps as 400%, 450% and 500%.
Source: Promoter deck, 26 October 2026, slide 7; Leader document, September 2026, Part I
It stops. The 540-day term is the fixed reward period of the product: when the order completes its term, all rewards stop accruing, whether or not the 5× cap has been reached, and the order does not extend itself to reach the cap. The term and the cap are two separate rules. The same applies to the 180 and 360-day terms. As stated by Spartan OS in writing on 16 October 2026, for the 540-day USDT liquidity bond and 540-day long-term staking alike.
This replaces the reading of 25 September 2026 that the position keeps paying until it reaches the cap, whatever the term; the 16 October answer is the later and the more specific one, and the page, the calculator and the guides follow it. By the end of the term the capital has been fully released, second by second; what has not arrived by then is interest the position did not earn. To continue, a new order. The full answer is reproduced in the Official section.
Source: Spartan OS, written answers on the 540-day products, 16 October 2026, reproduced in the Official section
The return-cap mechanism takes over: the order stops generating rewards, and the part of the capital not yet released is frozen. The project's example (16 October 2026): an order of 1,000 USDT, cap 5,000; on day 400 the capital released, the base interest and the additional interest together reach 5,000; 140 days of the capital's release schedule remain, and that unreleased portion is frozen. To unlock it, the participant opens a new 540-day order larger than the remaining unreleased capital of the original order. Once the new order is active, the frozen capital resumes its release on the original schedule until it is fully released; the new order runs its own 540-day term under its own 5× cap; the original order's interest does not restart.
Two things to say plainly. The project states the cumulative cap as capital 1× plus interest 4× (base and additional) = 5×, and its example reaches the cap on day 400 with about 259 USDT of the capital (140 of 540 days) still unreleased, more than the stated 4× interest limit on its own would produce: the two limits are stated separately, and the position screen on the day is the reference. At the stated 1.3% a day, arithmetic puts the cap around day 337, with about 376 USDT of each 1,000 still to be released; unlocking that takes a new order above 376 USDT. The unlocked capital is the member's own money coming back, not a new reward. Not a promise of return.
Source: Spartan OS, written answers on the 540-day products, 16 October 2026, reproduced in the Official section
A new order. To keep earning after a 540-day term, the participant opens a new 540-day order, which starts its own 540-day reward cycle under the standard 5× cap. Which asset it takes depends on the product: the 540-day USDT liquidity bond and 540-day long-term staking are two different products, and each accepts the participation assets its own rules name (as stated 16 October 2026). On this page's reading, the bond is entered with USDT and long-term staking with USDT or RM, as the project's side-by-side of 25 September has it. Read the order screen of the product on the day.
A new order is a new decision at that day's rate and that day's price; nothing renews by itself and no renewal on the same terms is promised. A leader who says it rolls over is wrong. The RM released from the first order is the member's to sell, hold or stake; staking it is one of the choices, under the staking product's own rules.
Source: Spartan OS, written answers on the 540-day products, 16 October 2026, reproduced in the Official section
At the stated rates, before any team income: $6 flexible, $11 at 180 days, $12 at 360 days, $13 at 540 days, $15 on a burning bond. On $10,000: $60, $110, $120, $130 or $150 a day.
Simple daily rate as stated on 7 September 2026, compounding not included. Rates float; caps are fixed in USDT at entry. Not a promise of return. Say every result in RM and let the listener convert.
Source: Promoter deck, 26 October 2026, slide 8
No. Bonds are bought from the same dashboard but are their own product. A liquidity bond sells RM at a discount to market (about 2% to 5% at 180 days, 4% to 10% at 360, 6% to 16% at 540 on the dates stated), paid like the matching stake, under the same cap, with no extra rewards. From $1.
Worked example from the call: $1,000 into a 540-day bond at 15% off buys RM worth $1,150; at $30.46 per RM the entry price is $26.21. Staking releases RM faster and adds extra rewards; a bond buys more RM under the same ceiling. Ask which the person wants to hold. Discounts float with the market, and the project said so in as many words on 25 September 2026, the day it also told the international team to lead with the bond at this stage; bond principal and rewards release daily. See the bond cards and the Official section.
Source: Promoter deck, 26 October 2026, slide 9; Leader document, September 2026, Part II
From $500, no maximum. It releases 250% of the order, which is 150% net, at 1.5% a day net with no compounding, capped at 2.5×. It adds a 20% energy recharge and a 3% GD airdrop. It is how leaders buy energy for level income, and one of only two ways to obtain GD.
The highest daily number, the lowest ceiling, and the only door to GD besides the open market. At the stated rate it reaches its cap in about three months.
Source: Promoter deck, 26 October 2026, slides 8 and 9; Leader document, September 2026, Part II
In plain terms, yes. The rewards of every stream, staking interest, bond releases, level income and rank rewards, are paid in RM that the protocol mints and releases under its rules; the project describes it as RM generated through daily block production and released in a controlled way. Spartan OS does not deny this: its own statement says the system is not designed only to create emissions, and that minting alone solves nothing. What it claims is that each release arrives with mechanisms on the demand side: the turbine, which makes every claim a purchase of the same amount of RM with a 24-hour silent period; long-term locking through the 360 and 540-day products and compounding; the 5% base sell tax with 1.2% buyback and burn, and the extra tax on the way down, 65% of it burned; RM burned for Energy; O² adjusting protection to the market; and application demand. None of that guarantees a price.
The honest answer has two halves and a test. The halves: new RM is created to pay the plan (supply), and the design tries to create matching demand (turbine, locks, burns, applications). The test is the data, which the project itself names: new RM supply against circulating supply, Turbo buy demand, RM locked long term, RM burned, and liquidity depth, all on the dashboard and the explorer. The one stress episode on record is the fall of 13 September 2026 and the recovery that followed. Not to say: that RM cannot fall, that the mechanisms stop selling, or that the rewards come from trading profits or company revenue; the project has not said so, and the cash-flow card explains what reaches holders and what does not.
Source: Statement on how capital entering the protocol is treated, received 24 September 2026; Response to Seven Due Diligence Questions, 24 September 2026; both reproduced on this page
Where every RM you earn is claimed, from staking, bonds, rank rewards and level income alike. You buy the same amount of RM on the DEX, one to one, wait 24 hours, and both amounts are yours. Every payout is also a purchase.
That is the platform's explanation for RM holding above $30 since launch while paying daily returns: the returns themselves are buy pressure. Say it in one breath: everything you earn goes through the turbine, buy the same amount, wait 24 hours, then it is yours. Only level income needs energy on top.
Source: Promoter deck, 26 October 2026, slide 13; Leader document, September 2026, Part III
A third bucket on long-term positions only, funded by 35% of the extra sell tax and claimable every twelve hours. They do not compound, so claim them daily. Anyone with $200 or more in a 360 or 540-day position shares in them.
When others panic and sell into a fall, the extra tax they pay is split: 65% burned, 35% to this pool. Holders are paid for the dip.
Source: Promoter deck, 26 October 2026, slides 7 and 13
Three six-day stages as published: stage one at $4 with a 5.0× multiple, an 8% GD airdrop and a 1% fee; stage two at $3, 4.5×, 5%, 0.8%; stage three at $2, 4.0×, 3%, 0.5%. The columns are the project's; how each is applied has not been fully defined.
This is the part of the model most likely to change. Before presenting any of it, check the current announcement on x.com/Spartan_Arena_. If the numbers differ, the leader document's page is superseded.
Source: Leader document, September 2026, Part VI
As shown on spartanar.org on 9 November 2026: RM $31.16. Flexible 0.2832% per rebase, two rebases a day, no cap. Long-term caps 4×, 4.5× and 5×. Bonds 2.79%, 19.52% and 26.00% below the RM price at 180, 360 and 540 days. Stability vault: from 500 USDT, release cap 250%, GD vests over 30 weeks. Energy 260% on a 360-day stake, 557% on burning RM. Fees 5% base, 1% protection. Turbine extra ratio 1%.
The dashboard read market cap $456.61 million, RM supply 14,684,764, treasury $76.22 million (risk-free $13.55 million), 69.65% of RM staked, total value locked $319.0 million, flexible pool $93.1 million, LP bond balance $170.9 million, buyback fund 4,710,668 USDT. Rates float; check the dApp before quoting, and use the Terms today section for the full list.
Source: spartanar.org, read on 9 November 2026
Use the two calculators on this page. The first takes an amount, a product, the rate (pre-filled as stated), a price and a horizon, and shows day one, thirty days, the horizon, the cap and the day it is reached, in RM and USDT, plus every product side by side. The second takes your own position and your legs, finds the rank, and shows the DAO reward on the small zone, level income, energy and the bonus lines, with the same volume re-split into two to six legs.
Both label every assumption. The three bonus lines follow the confirmed rules (differential on the band difference; same-rank and override at 10% to 15% of the nearest such position's earnings) on estimated bases, and each row says which part is estimate. Copy summary gives a text you can paste to the person you are talking to, cap and date included.
Source: This page, 9 November 2026
To create demand alongside supply. Under the 1:1 Turbo Engine, participation generates a compulsory RM purchase of the same size, with a holding period. The statement's purpose is explicit: the system is not designed only to create token emissions; it tries to create corresponding market demand for RM while rewards and supply are being generated and released.
Pair this with the turbine card for the mechanics (claim, buy the same RM, 24 hours). The economic point is that every emission arrives with a matching purchase requirement, which is the project's answer to the question every minting model has to face: who buys the new supply.
Source: Statement on how capital entering the protocol is treated, received 24 September 2026, reproduced in the Official section
Yes. The initial capital of a staking position or a bond is included within the 4×, 4.5× or 5× total release cap. The mechanism releases principal and earnings together over time, and the principal is not separately returned on top once the cap has been completed. On a 5× position, both the principal and the earnings the protocol releases are counted within that 5× total. Confirmed 26 September 2026.
Say it as the project does: principal plus earnings are released together, both inside the cap, and the principal is not an additional payment on top. $1,000 at 540 days can therefore pay out $5,000 of RM value in total, of which $1,000 is your own capital coming back. At the stated rates the 360 and 540-day positions reach their cap before the term ends; the project's answer says nothing is paid after the cap, so read that literally and ask before promising otherwise. The calculator now applies this reading only.
Source: Answers to four follow-up questions, received 26 September 2026, reproduced in the Due diligence section
The project's answer on 25 September 2026: the bond, at this stage. Asked what the bond offers over regular staking, Harry's reply was that the bond carries a discount and staking earns a larger quantity of coins. The instruction relayed to the international team the same hour: tell the international market to buy the bond at this stage instead of regular staking.
Pass it on as the project's guidance, dated, never as your recommendation of a return. The reasons are in the comparison card: the same USDT buys more RM through the bond, and principal and rewards release daily. The discount floats, so open the bond page before quoting it. The Phalanx order, set 3 October 2026: the bond first; staking after the person is in the system and holds RM bought from their leader.
Source: Spartan OS international team, working group, 25 September 2026, reproduced in the Official section
At the market price of $30.8081, about 32.459 RM. Through the 360-day LP bond at $27.5301 (10.64% below market), about 36.324 RM, 3.865 more. Through the 540-day LP bond at $26.2535 (14.79% below market), about 38.090 RM, 5.631 more. All figures as posted by the project on 25 September 2026.
The numbers are one day's snapshot; the comparison card in the Official section carries them with the date, and the products calculator takes today's discount from the bond page. The extra RM is the entry advantage; what the position then pays is the same rate and cap as the matching long-term stake.
Source: Spartan OS international team, working group, 25 September 2026, reproduced in the Official section
Daily. For both the 360-day and 540-day LP bonds, principal and rewards are released daily throughout the bond period; there is no waiting until maturity for the capital. Confirmed by the project on 25 September 2026.
Consistent with the capital-inside-the-cap rule of 26 September: principal and earnings release together and both count inside the 4×, 4.5× or 5× cap. Say 'released daily, inside the cap' and the two answers agree.
Source: Spartan OS international team, working group, 25 September 2026, reproduced in the Official section
No. 'The discount is not fixed. The protocol will be adjusted based on the actual circumstances.' On 24 September the bond page showed 1.29%, 11.46% and 16.61% below market for 180, 360 and 540 days; on 25 September the project quoted 10.64% and 14.79% for 360 and 540; on 21 October 2026 the page showed 2.17%, 13.15% and 18.94%; on 9 November 2026 it showed 2.79%, 19.52% and 26.00%. Read the discount from the bond page on the day.
Never print a discount without its date. The calculator's bond field says 'as shown on the bond page' for this reason.
Source: Spartan OS international team, working group, 25 September 2026, reproduced in the Official section
Level income, energy, the V1 to V12 ladder, the AICS score.
8% of the ROI earned by the people you introduced directly, 4% on the second level, 2% on the third, paid every twelve hours. It is the one stream that needs energy to withdraw, and it passes through the turbine like everything else.
Worked example over one period: level one, three people generating 20 RM each: 60 × 8% = 4.8 RM. Level two, six people at 15 RM: 90 × 4% = 3.6 RM. Level three, ten at 10 RM: 100 × 2% = 2 RM. Total 10.4 RM, which needs 10.4 units of energy to withdraw.
Source: Promoter deck, 26 October 2026, slide 11; Leader document, September 2026, Part IV
The unit needed to withdraw level income: one unit per RM withdrawn. Not needed for personal staking, bonds or rank rewards. Two separate ways to get it, at the multiples the dApp shows on the day: stake RM for 360 days (260% of the position on 26 September 2026) or burn RM (557% of the amount burned, so about 0.18 RM burned covers 1 RM of level income). Both multiples are dynamic protocol parameters; the dApp is the final reference (confirmed 26 September 2026).
Withdrawing $1,000 of level income needs 1,000 units: at 557%, burn RM worth about $180; at 260%, hold about $385 of RM in a 360-day stake. The burning bond adds a 20% energy recharge. The 150% and 200% in the Economic Model Analysis and the 2 to 6 times range in the due-diligence answers of 24 September are superseded by the live dApp figures, by the project's own instruction of 26 September 2026. Open the Energy page before quoting a multiple, and say the date.
Source: Leader document, September 2026, Part III
Two legs, not three. The larger leg qualifies the rank; the smaller pays the reward. V1 needs $500 staked, three qualified directs ($100 or more each) and $10,000 in each of two legs, and pays about $15 to $25 a day from the DAO pool. V2: $1,500, four directs, $50,000 a leg, about $80 to $180 a day. V3: $3,000, five, $150,000, about $150 to $300.
V4: $5,000, six directs, $300,000 a leg, $300 to $500 a day. V5: $7,000, eight, $600,000, $800 to $1,200. V6 to V12 figures are reference only, set daily by the block reward rate and the AICS score: never fixed, never guaranteed. Origin required three teams; Spartan OS requires two. The larger leg is the large zone; every other leg together is the small zone, and the reward is paid on it (confirmed 24 September 2026). V10 to V12 need two legs each holding the rank below. The differential between ranks is confirmed as the percentage difference between the two bands, paid to the higher rank. The same-rank bonus is 10% to 15% of the applicable earnings of the nearest same-rank position under you, once, not from every such position further down; the override (overtaking) reward follows the same nearest-position principle (confirmed 26 September 2026). V12 personal stake 50,000 USDT, confirmed the same day.
Source: Promoter deck, 26 October 2026, slide 11; Leader document, September 2026, Part IV
$500 staked yourself, three directs with $100 or more each, and $10,000 in each of two legs. Stated daily rank income at V1: about $15 to $25, moving within the range by AICS score.
As the deck puts it: three people and two teams of $10,000. Origin needed three teams at $50,000.
Source: Promoter deck, 26 October 2026, slide 11
Your own stake first, then the directs, then two sides at once. V1: $500 of your own, three directs with $100 or more each (the team advises four), $10,000 in the largest line and $10,000 across all the other lines. V2: $1,500, four directs, $50,000 and $50,000. V3: $3,000, five, $150,000 and $150,000. V4: $5,000, six, $300,000 and $300,000.
The Spartan OS team's rank models of 3 November 2026 lay V1 out as one line of $10,000 and three of $4,000, $3,000 and $3,000; V2 as $50,000 and four lines of $20,000, $15,000, $10,000 and $5,000; V3 as $150,000 and four lines of $40,000, $40,000, $35,000 and $35,000; V4 as $300,000 and five lines of $60,000. The largest line qualifies the rank; the other lines together are the small zone, and the DAO reward is paid on it, so grow it first. The models' earnings are illustrations at 0.6% every twelve hours, the static earnings compounded, with RM at $30: rates float, caps are fixed at entry, and nothing here is a promise of return. V4's earnings rows from day 30 do not follow that rate; use V4 for its qualification and layout only. The four images are in the Ranks section.
Source: Spartan OS team, rank models V1 to V4, 3 November 2026; Promoter deck, 26 October 2026, slide 11
A score on every account, published on 24 September 2026 as Score = 0.2H + 0.4C + 0.2A + 0.2R over a 30-day rolling period: holdings 0.2, activity 0.4, contribution 0.2, retention 0.2, with the 0.4 on activity confirmed the same day. It moves rewards within their bands, so two V6s can be paid differently. The programme pays for quality of participation, not size alone.
The letters as printed do not spell the dimensions out; the weights above are the confirmed reading. How each dimension is measured has not been published. Say so when asked.
Source: Leader document, September 2026, Part IV
Level income first: 8, 4, 2 percent of the ROI on three levels, every twelve hours, energy needed to withdraw it. Then the ladder: two legs, the larger qualifies, the smaller pays. Then V1 in plain words: $500, three people, two teams of $10,000. Stop there. If they ask about V6 and above, say approximate, reference only.
Most participants will sit at V1 to V3. Present the upper levels as the structure of the programme, not as a plan for the person in front of you. The small leg is the binding constraint at every level: ask about it first.
Source: Promoter deck, 26 October 2026, slide 11 notes; Leader document, September 2026, Part VII
Under the Community Meeting Policies of 26 August 2026: a community with the required qualification applies in advance with a fee that depends on size, 500 USD for a 30-person meeting, 800 USD for 50, 1,500 USD for 100. Meetings are held online or in a community group, hosted by local leaders with core team members present. If performance after the event reaches at least 150% of the fee, the excess is paid back as a reward; if not, the host community covers half the event cost.
Apply three to five days ahead, pay electronically, get approval before the event, and keep screenshots and the link. Participants attend in full. The policy asks pregnant women, people over 65 and anyone with a heart condition or high blood pressure to sit out or tell the organisers first. As published; confirm current terms with the operations team.
Source: SpartanOS Resource Library (t.me/SpartanOSLibrary), Subsidy policy topic, 26 August 2026
The dApp places every account under the person whose link it first connected through, and the binding cannot be changed later. The Phalanx link is spartanar.org/myinvite?code=0x83659d0BDF57ac8550060E869fC5926e52E2e5Fe; the code is the referrer's wallet address. Register through the link your leader gives you. Your own link is on the My Invite page of the dApp, with the total invited, your directs, team performance and the invite records by level.
Level income (8%, 4%, 2% of the ROI on three generations) and the rank on the DAO page follow from that binding. A direct counts as a node from 100 USDT. Never register through a link found in a public chat: the leg is permanent.
Source: spartanar.org, read on 9 November 2026
Your largest leg is the large zone; every other leg added together is the small zone. Confirmed on 24 September 2026. The large zone qualifies the rank; the DAO reward is paid on the small zone, at the daily block rate, inside the band for the rank. Two legs at the requirement is the minimum; more legs put more of the same volume into the small zone.
The project's V1 example: a power leg of 10,000 and the other legs together at 10,000. In the rank calculator, add every leg you have; the page finds the large zone and sums the rest.
Source: Phalanx Community, confirmed 24 September 2026; Spartan OS V1 example
The difference in percentage between two ranks is paid to the higher rank. Confirmed on 24 September 2026 with the project's own example: if a V7 pays 60% and a V8 pays 70%, the V8 receives the 10% difference on that V7's leg. The same-rank bonus and the override (overtaking) line were confirmed on 26 September 2026: 10% to 15% of the applicable earnings of the nearest same-rank, or nearest higher-ranked, position under you, once, not from every such position down the line.
The base the difference applies to has not been spelled out; the calculator applies it to the lower-ranked leader's estimated small zone at the block rate, and says so. Quote the rule, not the calculator's number.
Source: Phalanx Community, confirmed 24 September 2026
Two legs each holding the rank below: two V9 legs for V10, two V10 legs for V11, two V11 legs for V12. Confirmed on 24 September 2026; it is a rank requirement, not a volume. Personal position and node counts: V10 18,000 USDT and 18 nodes, V11 20,000 and 19, V12 50,000 and 20 (the V12 figure confirmed 26 September 2026).
The reward-pool page prints it as "2 V9s"; some promoters had read it as twice the volume. The 25,000 printed for V12 on page 16 of the Economic Model Analysis should not be used: the project confirmed 50,000 USDT as the V12 personal stake on 26 September 2026, and said there is no separate governance-weight parameter.
Source: Phalanx Community, confirmed 24 September 2026; Economic Model Analysis, page 16
As stated on 24 September 2026: Score = 0.2H + 0.4C + 0.2A + 0.2R, over a 30-day rolling evaluation period, with the 0.4 weight on activity (confirmed the same day) and 0.2 each on holdings, contribution and retention. The assessment considers holder participation, effective accounts, the proportion of long-term participation, retention, activity and contribution to the ecosystem and its liquidity. Two networks at the same rank need not receive identical effective incentives.
The letters as printed do not spell the dimensions out; the September briefing gave holdings 0.2, activity 0.4, contribution 0.2, retention 0.2, and the 0.4 on activity was confirmed on 24 September. Say the formula as written and the weights as confirmed. A score can rise with long-term participation, retention, active addresses and constructive contribution, and fall with heavy selling, falling retention or weaker contribution to liquidity.
Source: Statement on how capital entering the protocol is treated, received 24 September 2026, reproduced in the Official section
Not by design. Spartan OS states that long-term network rewards are not meant to depend only on how many people someone recruits or the volume a network generates. AICS evaluates the quality and health of participation on a 30-day rolling basis, so rewards are increasingly linked to network quality: long-term participation, retention, active addresses and constructive contribution move the assessment up; heavy selling and falling retention move it down.
This changes how a leader builds. Ten people who stake, stay and use the applications score better than fifty who churn. The rank ladder still sets the requirements; AICS moves the pay within the band. Show both, and say which one the leader controls day to day.
Source: Statement on how capital entering the protocol is treated, received 24 September 2026, reproduced in the Official section
10% to 15% of the applicable earnings of the nearest same-rank position under you, once. The project's own example: a V5 with two V5 accounts below, one in the first generation and one in the second, is paid on the first-generation V5 only. You do not receive the same-rank reward again from every V5 further down that line. A V8 with a V8 in the team receives 10% to 15% of the applicable earnings of the nearest qualifying V8 position. Confirmed 26 September 2026.
The override (overtaking) reward follows the same nearest-position principle. Where the 10% or the 15% applies inside the range is not stated; quote the range. The calculator applies the rule to the nearest same-rank leader in each leg, on an estimated base, and says so. Whether two same-rank positions in two different legs both pay has not been stated: the wording is the nearest position under your structure, singular, and the example is a single line.
Source: Answers to four follow-up questions, received 26 September 2026, reproduced in the Due diligence section
50,000 USDT, as the current Leader Edition rank table prints it. The project says the 50,000 is the personal stake requirement for V12, and that there is no separate governance-weight parameter. The 25,000 on page 16 of the Economic Model Analysis should not be used. Confirmed 26 September 2026.
So the ladder reads: personal stake V10 18,000, V11 20,000, V12 50,000 USDT, with 18, 19 and 20 nodes and two legs each holding the rank below. If a member shows you the 25,000 page, say the table it comes from is superseded by the Leader Edition figure, and point to this answer.
Source: Answers to four follow-up questions, received 26 September 2026, reproduced in the Due diligence section
Whatever the dApp shows on the day. Two separate mechanisms: energy staking, 260% on 26 September 2026, and RM burning for energy, 557%. Both are dynamic protocol parameters that the protocol can adjust, so they may change. The 150% and 200% in the Economic Model Analysis and the 2 to 6 times range in the due-diligence answers should not override the live figures. Confirmed 26 September 2026.
Practical reading: a 360-day stake carries energy at 2.6 times its size; burning 1 RM earns 5.57 units, so about 0.18 RM burned covers 1 RM of level income, at those settings. Say the date with the figure, and open the Energy page before quoting it. The two mechanisms are not to be mixed together.
Source: Answers to four follow-up questions, received 26 September 2026, reproduced in the Due diligence section
What protects the price, what it cannot do, the sell tax.
RM's adaptive balancing protocol. Spartan OS positions it as a global first: the Olympus DAO and Origin model of protocol-owned liquidity, upgraded so the rules adapt to the market instead of the market adapting to fixed rules. It balances supply and demand and protects liquidity. It does not set the price.
Four layers: liquidity (protocol-owned liquidity plus dynamic liquidity management), behaviour (buybacks, rewards and trade-side regulation), supply (burns, buybacks and LP-token burn options) and the adaptive engine (market-state analysis and response selection). Visible tax changes are only the outer shell.
Source: Promoter deck, 26 October 2026, slide 13; O² core interpretation deck, Spartan OS, September 2026
Time-weighted average price, average trade price, buy volume, sell volume, the buy-to-sell ratio and liquidity depth, reassessed every three hours. Normal profit-taking and panic selling can both push the price down, but they are not the same event. The system reacts only when volatility becomes a real imbalance. Price is a signal, not the verdict.
A fear-and-greed sentiment engine sits alongside: extreme greed can drive unstable chasing, extreme fear can trigger concentrated exits, and the protocol maps the current regime to an execution strategy.
Source: O² core interpretation deck, Spartan OS, September 2026, slides 4 and 7
Buying is free. Selling starts at 5%. If the price falls more than 5% against its three-hour average, the tax climbs in bands: a 5% to 8% fall pays 8% to 13%, an 8% to 15% fall pays 13% to 20%, a fall of 15% or more pays 20% to 30%. Slow selling is cheap; dumping is not. The aim is to slow cascades, not to block exits.
Of the tax above 5%, 65% is burned and 35% goes to long-term holders. A fixed 1.2% of every sale buys back RM and GD and burns them. What sets the tax within a band is not published: quote the band. Say plainly that exiting in a downturn is expensive by design.
Source: Promoter deck, 26 October 2026, slide 13; Leader document, September 2026, Part V
1.2% of every sale buys back RM and GD and burns them. Of any extra tax above 5%, 65% is burned outright and 35% goes to anyone with $200 or more in a 360 or 540-day position. Supply goes down; holders are paid for the dip.
The published fee split on transactions is 5%: 0.5% platform fund, 1.2% buyback fund, 1.3% community fund, 2.0% ecosystem fund. Extra-tax rewards are locked 72 hours and distributed on a weighted basis; the weighting has not been published.
Source: Promoter deck, 26 October 2026, slide 13; Leader document, September 2026, Part V
Every three hours the market is reassessed from fresh data. The first imbalance triggers protection. Stabilisation triggers a step-by-step rollback of that protection. A new sell wave pauses the rollback and reactivates stronger protection. Under sustained recovery the rollback can complete within a 24-hour window.
O² behaves like a feedback loop, not an on/off switch. The execution loop runs market data, assessment, strategy, execution check, execute, reassess in three hours. A valid strategy still needs a valid execution window: if volatility spikes into an abnormal range, execution can be deferred.
Source: O² core interpretation deck, Spartan OS, September 2026, slides 6 and 9
Deep supply-side tools are reserved for abnormal risk states. An LP-token burn is not an everyday tool: it is considered only under sustained abnormal decline and LP-depth deterioration, gated by TWAP warning conditions and governance authorisation. Different risk levels activate different tools; one mechanism is never asked to solve everything.
The leader document lists the same idea as base pool burning: a last-resort mechanism with no published trigger level. The adaptive market engine's parameters have not been published either. Do not describe how it works beyond this, because the project has not.
Source: O² core interpretation deck, Spartan OS, September 2026, slide 8; Leader document, September 2026, Part V
Manufacture demand. In the project's own words, the protocol can buy time; only consensus creates enduring support. O² can defend liquidity, slow concentrated selling and reduce supply-side pressure. The market determines the price.
Answer the question they are thinking before they ask it: what stops it collapsing like the others. The honest answer is that the protocol protects liquidity and slows a cascade, and it does not promise a price. Then the four cards: turbine, tax, burn, pool.
Source: Promoter deck, 26 October 2026, slide 13 notes; O² core interpretation deck, Spartan OS, September 2026, slides 10 and 12
Growth drives rewards. Rewards drive buying demand, because every payout passes through the turbine. Buying demand strengthens support. Support reinforces confidence. Confidence fuels the next wave of growth. Protocol balance and ecosystem demand compound each other.
Source: O² core interpretation deck, Spartan OS, September 2026, slide 11
Supply and demand, not the price on its own. In the project's words, price is the result; supply and demand are the cause. Every three hours O² reads buy volume, sell volume, TWAP, average execution price, the buy/sell ratio, liquidity depth and overall supply-and-demand conditions. When the imbalance is significant it raises sell-side protection; when conditions return to the healthy range it steps protection back gradually, and returning to the baseline requires the conditions to hold continuously.
The statement calls it an adaptive safety valve at the execution layer. Say that in plain words: it slows a cascade and gives liquidity time; it does not decide the price and it does not stop anyone selling.
Source: Statement on how capital entering the protocol is treated, received 24 September 2026, reproduced in the Official section
No, and the project says so. A protocol can manage mechanisms; it cannot control human behaviour. Even with O², sudden large-scale selling and market shocks cannot be completely avoided. O² manages the supply-demand balance and AICS manages network health; both reduce risk and neither removes anyone's freedom to sell. That is why Spartan OS says it puts weight on consensus education, community guidelines and long-term culture.
Use the project's own line: mechanisms maintain balance, consensus builds long-term value. It is also the honest close to any O² conversation. Whether the design works is to be judged on on-chain data over time, not on the description.
Source: Statement on how capital entering the protocol is treated, received 24 September 2026, reproduced in the Official section
Seven mechanisms on both sides of the ledger, as Spartan OS lists them: controlled release; 1:1 Turbo demand; long-term locking through 360 and 540-day bonds, long-term staking and compounding; burn, with RM burned for 2 to 6 times its value in Energy and Energy staking on a 360-day structure; AICS; O²; and application demand. Turbo purchases sit in a 24-hour silent period and the baseline sell tax is 5%, so a purchase cannot become a sell order of the same size an hour later.
The metrics the project says matter: new RM supply, actual circulating supply, Turbo buy demand, application demand, long-term locked RM, burned RM and liquidity depth, rather than how much RM is generated. And its own limit, in its own words: these mechanisms improve the supply-demand structure and guarantee no price; sustainable demand has to grow enough to absorb sustainable supply. On O²: the fastest return to the 5% baseline is within 24 hours, and only if the recovery conditions hold continuously through the three-hour cycles. On the burn multiple: two days later the project said the 2 to 6 times range should not override the live dApp parameters, which read 557% for burning and 260% for energy staking on 26 September 2026, both dynamic.
Source: Response to Seven Due Diligence Questions, received 24 September 2026, reproduced in the Due diligence section
Because mechanisms adjust parameters and cannot control behaviour, in the project's own words. O² reads supply and demand, TWAP, transaction activity, buy and sell ratios and liquidity depth, and raises protection when the market is imbalanced. AICS scores network health. Neither can stop a person becoming greedy in a rally or fearful in a correction, which is why Spartan OS names community governance as a second foundation next to the mechanisms.
Olympus DAO is the reference the project uses: mechanism design has power, and mechanisms alone did not solve every market problem. Say both halves. A promoter who sells O² as a guarantee is contradicted by the project's own text.
Source: Harry (Spartan OS), 'From a U-shaped recovery to a global ecosystem', forwarded to the Phalanx channel on 26 September 2026, reproduced whole in the Official section
Add the network, bridge, gasDAI, import tokens, swap, play.
Install Bitget Wallet and back up the seed phrase. Switch to Anubis Chain (chain ID 6714), or add it in another wallet. Bridge a few dollars of DAI through app.anubisbridge.com or galebridge.net: that is your gasDAI for fees. Bring USDT onto Anubis the same way, a small amount first. Open the Spartan OS dApp through your leader's referral link or code and connect the wallet. Then buy the 540-day bond, from $1, reading the price and the cap on the screen, and claim every twelve hours through the turbine.
Seven steps, one evening. The Get in section of this page walks through all of it, from installing a wallet to the 540-day bond and the first claim, with the written version and the team's films at each step; one-pager 06 fits it on a page. Staking is not one of the seven: it comes after you are in the system and hold RM bought from your leader. Test every new route with a small amount first.
Source: Promoter deck, 26 October 2026, slide 15; Technical guide, September 2026, Part IV; Spartan OS international team, working group, 25 September 2026 (the bond first)
In the Tutorials section: thirteen lessons, twenty-five films by the Phalanx team, from installing the wallet (A1) to claiming through the turbine (D1) and the way out (B5). Pick your wallet once at the top of the section and every lesson shows the film for it: Bitget Wallet and AstraCore for the whole path, TokenPocket for the two wallet lessons. Each Get in step shows the films that belong to it.
English voice and captions, two to four minutes each, recorded on the real apps at the end of September 2026. The films point to section 20, Links, for the chain settings and the token addresses. Screens change, the parameters do not; a rate seen in a film is the rate on the day of recording.
Source: Phalanx team tutorial films, received 2 October 2026
Section 20, Links, opens with them: network name Anubis, RPC https://rpc.anubispace.org, chain ID 6714, symbol DAI (gasDAI), explorer https://browser.anubispace.org; and the contract addresses of RM, GD, USDT and DAI on Anubis, each with a copy button. Compare the first four and the last four characters before you save one.
The full list of twenty-one contracts, each checked on the explorer, is in Terms today. Take addresses from this page or anubischain.ai, never from a chat.
Source: Spartan OS service account lists, 25 and 26 September 2026; each address checked on browser.anubispace.org
Network name ANUBIS Mainnet. Chain ID 6714 (hex 0x1a3a). RPC URL https://rpc.anubispace.org. Currency symbol gasDAI. Block explorer https://browser.anubispace.org. The chain ID is the value that matters: if it is wrong, the wallet is on the wrong network.
Registered on chainlist.org/chain/6714. Confirm the RPC against anubischain.ai before publishing it anywhere.
Source: Technical guide, September 2026, Part I and Guide 01
Bitget Wallet for the fewest steps: Anubis Chain is built in, swap and cross-chain work inside the wallet, and a gas subsidy of up to three zero-gas transfers a day runs through it. AC Wallet (AstraCore) is named by Spartan OS as the officially recommended strategic wallet partner and is the gateway for the AstraCore campaigns. OKX Wallet, TokenPocket and Binance Wallet also support Anubis; MetaMask needs the network added by hand.
Whatever the wallet: write the seed phrase on paper, never photograph it, and never type it into anything that asks. The tutorial videos on this page show Bitget, TokenPocket, OKX and Binance Wallet.
Source: Technical guide, September 2026, Part IV; Anubis Chain guide, 20 September 2026
Through an official bridge: Anubis Bridge at app.anubisbridge.com or GaleBridge at galebridge.net, from Ethereum, BNB Chain or Polygon. Connect the wallet on the source chain, choose the asset and Anubis (6714) as destination, approve, bridge, then confirm arrival on browser.anubispace.org. Small test amount first.
Anubis Bridge is free and takes two to three hours; GaleBridge takes seconds and charges 0.5% to 1.5%, as stated on the 7 September call. Bitget Wallet bridges from inside the wallet. Bridgers and Stargate are third-party routes that Anubis does not operate. Never follow a bridge link from a message.
Source: Promoter deck, 26 October 2026, slide 15; Technical guide, September 2026, Guides 06 to 08
You have no gasDAI. Bridge a small amount of DAI through the official bridge; the destination balance is your gas. A few dollars covers thousands of transactions. Never buy gasDAI from anyone offering it directly.
Source: Technical guide, September 2026, Guide 09
Tokens do not appear until you import their contract address. Take the address from the Terms today section of this page (RM 0x2e04…e59d, GD 0x21b6…1b4c, verified on the explorer on 24 September 2026), compare the first four and last four characters, then use the wallet's Import token screen. RM and GD are separate contracts: import both. If the symbol the wallet reads does not match, stop: the address is wrong.
Source: Technical guide, September 2026, Guide 10
On RocketSwap, the native exchange, from bridged USDT. Open it from the link on anubischain.ai, connect the wallet on Anubis, choose USDT to RM, read the quote (price impact and minimum received), approve once, then swap. Each transaction costs a fraction of a cent in gasDAI.
Large price impact means the pool is thin relative to your trade: reduce the amount or split it. Because of the encrypted mempool no one can front-run the swap. Confirm on the explorer with the transaction hash.
Source: Technical guide, September 2026, Guide 11
Paste it into browser.anubispace.org. An address shows its gasDAI balance, token balances and every transaction. A transaction hash shows status, block, fee, sender, receiver and token transfers. A token contract shows name, symbol, supply and holders; if the name does not match, the address is not the real token.
Screenshots from the explorer end most disputes. The home page lists the newest blocks and the time between them, which is where the live block time is visible.
Source: Technical guide, September 2026, Guide 13
Wrong balance after bridging: wait a minute, check the explorer, import the token. Fails for gas: bridge a little DAI. MetaMask says the chain ID does not match: the RPC is wrong, re-enter it. Bridge not arrived: check the source-chain lock transaction, confirm destination 6714, allow time. Wrong token symbol: wrong address, remove and re-import. Application will not connect: switch the wallet to Anubis (6714).
Source: Technical guide, September 2026, Part V
As published by Anubis Chain: USDT 0xDfb6a28BC6DC51fed17c27C880F2c66cDd040A3e. USDC 0x7DD9c7cBC32dF500Fa3C06fD60Cd62C4E97B2eEF. DAI 0x83fd06F0846d9D90B3016bF670Efe2E0B11cDe14. ETH 0xCA326ae4fE47d07e7D20421170DADAcD92eD694C. BNB 0x699D13487Ed6b78953da2750887B58Ef738f9636. POL 0x72cf15f74657Bb00dd1D8Dd475248dEe644F689A. LGNS 0x4D1D808a081FdAc440703b3765FC61f8028C06B8.
Confirm each on browser.anubispace.org/tokens before importing: the name, symbol and supply must match. Addresses as printed in the 100 Questions document (July 2026) and the 28 June statement; a typo in a PDF is possible, the explorer is the reference. RM 0x2e045e1380f5f5b6e7550328910a7377c9fce59d and GD 0x21b6b0b3fab224921d3054d187e324a673411b4c, verified on the explorer on 24 September 2026; see the Terms today section.
Source: Anubis Chain 100 Questions and Answers, official, July 2026, Q40; Announcement reproduced in the SpartanOS Resource Library, 28 June 2026
Time depends on the source chain: on Ethereum the bridge waits for 12 to 20 confirmations, so several minutes end to end; the bridge app shows the current estimate. Cost is the source-chain gas plus a bridge service fee displayed in the app. No minimum, no maximum, no total cap. Anubis advises a first test of 10 to 50 USDT.
On the 7 September call the leaders described Anubis Bridge as free but slower (two to three hours) and GaleBridge as seconds at 0.5% to 1.5%. Redemption is the reverse: burn on Anubis, release on the source chain. Never send Anubis-side assets straight to an exchange.
Source: Anubis Chain 100 Questions and Answers, official, July 2026, Q30, Q42, Q43 and Q45
No. A pegged USDT on Anubis is a separate asset from USDT on Ethereum or BNB Chain, and exchanges do not credit deposits from Anubis Chain. Bridge back to the source chain first, then send from there. The same 0x address exists on every EVM chain, which is exactly why the mistake is easy to make.
Sent by mistake, the assets sit on Anubis at an address the exchange controls and does not watch. Recovery depends entirely on the exchange. Say this before the first withdrawal, not after.
Source: Anubis Chain 100 Questions and Answers, official, July 2026, Q41, Q52 and Q53
Usually not. Many wallets have no price feed for tokens on a new chain, so the balance shows without a dollar value. The balance itself is what matters: confirm it on browser.anubispace.org by pasting your address.
If the balance is missing as well, the token is probably not imported yet, or the wallet is on the wrong network. Chain ID 6714, then import the contract address.
Source: Anubis Chain support in the promoter group, September 2026; Anubis Chain 100 Questions and Answers, official, July 2026, Q57
No. A self-custody wallet's seed phrase is the only key; neither Anubis Chain, the wallet maker nor any support person can reset it. If the wallet still opens, back it up now, create a new wallet, move the assets, revoke unneeded approvals and store the new phrase offline.
Anyone offering to recover a seed phrase for a fee is the second loss waiting to happen.
Source: Anubis Chain 100 Questions and Answers, official, July 2026, Q50
A confirmed transaction cannot be reversed by anyone. If the address is one you control, import it, switch to the right network and send the assets back. If it belongs to an exchange or another person, only they can help. If no one holds the key, the assets are gone. The project cannot alter the chain.
Source: Anubis Chain 100 Questions and Answers, official, July 2026, Q59, Q60 and Q81
Check the hash on browser.anubispace.org, then in order: the wallet is on chain ID 6714; the balance covers the amount plus gas; no earlier transaction from the same address is still pending, because transactions execute in nonce order; if the wallet offers Speed Up or Cancel, use it before the transaction lands. Do not resend with a new nonce, or you may pay twice.
Source: Anubis Chain 100 Questions and Answers, official, July 2026, Q62
Enter through official channels only, never through a search advertisement or a message. Compare the complete contract address with the one published officially: a matching name, symbol or logo proves nothing. On the explorer, check the network is 6714 and compare address, symbol, decimals and name. Verified source code helps review; it does not prove the team's identity. Then test with a small amount.
Source: Anubis Chain 100 Questions and Answers, official, July 2026, Q80
The one with chain ID 6714. Networks can share a name and not be the same chain. Enter the parameters by hand: name Anubis, RPC https://rpc.anubispace.org, chain ID 6714, symbol DAI, explorer https://browser.anubispace.org. If the RPC will not save, do not pick an 'Anubis' from the wallet's search list; fix the RPC and try again.
Source: Anubis Chain support note pinned in the promoter group, September 2026
An ordinary transfer is estimated at about 0.000252 DAI, as the FAQ puts it; token transfers, swaps and contract calls use more. The wallet shows the fee before you sign. A failed transaction still consumes the gas for the part that ran; one that never broadcast costs nothing.
Source: Anubis Chain 100 Questions and Answers, official, July 2026, Q54 to Q56
RM: 0x2e045e1380f5f5b6e7550328910a7377c9fce59d. GD: 0x21b6b0b3fab224921d3054d187e324a673411b4c. Both on Anubis Chain (6714). The explorer reads them as Rome (RM), 9 decimals, and Gladiator (GD), 18 decimals, 390,000 supply. As posted by Anubis Chain support on 13 September 2026 and matched to browser.anubispace.org on 9 November 2026.
Import both; they are separate contracts. Compare the first four and last four characters with the Terms today section, and check the name the wallet reads back. Pegged USDT is 0xDfb6a28BC6DC51fed17c27C880F2c66cDd040A3e and DAI 0x83fd06F0846d9D90B3016bF670Efe2E0B11cDe14. If a chat shows a different address, the chat is wrong.
Source: Anubis Chain support, 13 September 2026; browser.anubispace.org, 9 November 2026
spartanar.org. Pages: Dashboard (Data Analysis), Flexible Stake, 180, 360 and 540-day long-term stakes, Long-Term Liquidity Bond, RM Stability Vault, Charge Incentive Pool, My Invite, Spider Web Rewards (level income), DAO (rank), Turbine, Energy, Genesis Cornerstone, DAO Vote and the Trading Center (swap). The footer links home.spartanar.org and x.com/Spartan_Arena_ and shows the CertiK badge.
Type it, or open it through your leader's referral link the first time so the dApp binds the referrer. The dashboard is the reference for every rate and cap; the DAO page updates at each rebase, not in real time. Never connect a wallet to a look-alike domain.
Source: spartanar.org, read on 9 November 2026
Only if the chain ID is 6714. Harry's instruction to a member with a stuck bridge, 21 September: verify the network settings by hand against the official mainnet parameters, and do not rely on the name shown in the wallet. Network name Anubis, RPC rpc.anubispace.org, chain ID 6714, currency symbol DAI, explorer browser.anubispace.org. Networks can share a name and still be different chains; the chain ID is the identifier.
If the RPC cannot be added, do not pick an 'Anubis' entry from the wallet's own network search. Add it by hand from the parameters above, typed, then confirm 6714 before any transaction.
Source: Harry, working chat, 21 September 2026; parameters as published by the Spartan OS service account
Close the pending operation and leave GaleBridge. Open the wallet and check whether the asset is still there, then open the transaction record and check whether anything was actually submitted and completed on-chain. If the asset is intact and no outgoing transaction succeeded, the operation never completed: reconnect the wallet to GaleBridge and try again. Under normal conditions a transfer completes within seconds.
Changing phones does not help when the pending state belongs to the transaction or the wallet session. Before retrying, confirm the wallet is on chain ID 6714. Harry's steps of 21 September 2026, in order; the tutorial recordings show the bridge screens.
Source: Harry, working chat, 21 September 2026
The rules that prevent losses. Say them before, not after.
Type addresses, do not click them: links come from anubischain.ai or the three official X accounts only. Verify the first four and last four characters of every contract and recipient address. Test every new route with a small amount. Read every wallet prompt. Keep the seed phrase offline. Check the chain ID is 6714. Say what the risks are before, not after.
No official account will ever ask for a seed phrase. An address in a chat, a DM, a screenshot or a forwarded message is not official, whoever sent it.
Source: Technical guide, September 2026, Part V
When it appears on anubischain.ai or on x.com/AnubisLayer1 (Anubis Chain's primary account since 9 October 2026), x.com/AnubisChainL1 (the ecosystem account), x.com/ANUBISCHAIN_, x.com/Spartan_Arena_ or x.com/Anubis_Labs. Nowhere else. The Telegram community and the resource library are for conversation and files, never for addresses.
Source: Technical guide, September 2026, Part III
Anubis Chain is a new network with a short track record. Bridges are the most attacked component in the industry, and every asset moves through one. Tokens with small supplies and thin liquidity move sharply. RM carries a sell tax that rises as the price falls, so exiting in a downturn is expensive by design. TempleRaid is a game of chance. Three of the five Spartan OS systems do not exist yet. Roadmap items may slip.
None of that is unusual for a project at this stage. All of it should be said out loud by anyone presenting the project to someone who has not heard of it. Nothing here is financial advice and no figure is a promise of return.
Source: Long-form explainer, September 2026, Part VII; Leader document, September 2026, Part VII
No. Caps, variable rates, energy gating and price-dependent taxes all mean outcomes depend on conditions and behaviour. Every rate carries its cap and its date, and every rate floats.
Source: Leader document, September 2026, Part VII
Lead with the cap. Quote the band, never the top. Explain the turbine before the rewards. Name what is unpublished. Keep the public material separate from the programme terms. Say what the risks are.
Always with the cap, always with the date, never as a promise. A rate without a ceiling is a story; a rate with a ceiling is a contract. Present the files as issued, translate with approval, never edit a number.
Source: Leader document, September 2026, Part VII
Two, from September 2026. Anubis Chain has never published a social app on any app store; an app called 'Anubischat' is not official and must not be installed or connected to a wallet (19 September). CertiK and Anubis Chain warn that malicious code linked to FomoPeek can be repackaged into iOS apps and read keys, seed phrases and chats: update to iOS 26.7, avoid apps from unknown sources, never type a seed phrase into an unofficial app (20 September).
Forward both notices whole. A promoter who circulates a security warning early has done more for the team than one who circulates a price chart.
Source: Announcement reproduced in the SpartanOS Resource Library, 19 and 20 September 2026
Anubis Chain's primary X account since 9 October 2026 is @AnubisLayer1; @AnubisChainL1, primary from 16 September to 9 October, is the ecosystem account; the older @ANUBISCHAIN_ carries the earlier announcements. Anubis Labs: @Anubis_Labs. Spartan OS: @Spartan_Arena_. The website: anubischain.ai. The English resource library on Telegram: t.me/SpartanOSLibrary. The Spartan OS dApp: spartanar.org, whose footer links x.com/Spartan_Arena_ and home.spartanar.org.
Anything else is conversation. Addresses and links are taken from these sources, never from a chat, however senior the sender appears.
Source: Announcement reproduced in the SpartanOS Resource Library, 16 September and 9 October 2026; SpartanOS Resource Library (t.me/SpartanOSLibrary)
No, and the project says so in as many words. On-chain assets belong to their owners and every participant has the right to make their own decisions. Community conventions are self-governance: freedom of choice with an understanding of how a choice affects the shared market. The protocol does not decide for users and the community does not decide for users; a mature community helps people understand the market so they decide well.
If a member has been told, anywhere, that selling is forbidden or that a leader can hold their assets, correct it on the spot and point to this answer. The project's phrase: true decentralisation should not mean the absence of order, and freedom should not mean the absence of responsibility.
Source: Harry (Spartan OS), 'From a U-shaped recovery to a global ecosystem', forwarded to the Phalanx channel on 26 September 2026, reproduced whole in the Official section
Where to check every figure yourself, and what is only stated.
Chain ID and fee unit: chainlist.org/chain/6714. Any transaction, contract or address: browser.anubispace.org. Bridge contracts: etherscan.io, bscscan.com, polygonscan.com. Audits: skynet.certik.com. RM market data: geckoterminal.com, dextools.io. Official announcements: anubischain.ai and the three X accounts.
Source: Long-form explainer, September 2026, Part VII
Verifiable today: chain ID 6714 and gasDAI, EVM compatibility, bridge contracts on three source chains, the GaleBridge audit, RocketSwap on CertiK Skynet, TempleRaid rounds and RM trades on the explorer. Stated by the project: Origin's snapshot figures, the 16 million users, data-report figures beyond the explorer, the $300 million commitment, 137 contracts and the audit submission, every rate and dashboard figure, DeBox's 26 million users, all undated roadmap items.
The second list is a list of claims carried as the project states them, because they could not be checked against an independent source. A promoter who is asked about any of them should say exactly that.
Source: Long-form explainer, September 2026, Part VII
GaleBridge was audited by CertiK in October 2025: three findings, none critical, report on skynet.certik.com. RocketSwap is listed on CertiK Skynet. Anubis Chain announced a CertiK and Armor audit of 137 core contracts on 13 July 2026. Anubis Labs announced on 2 August 2026 that Spartan OS completed its CertiK assessment: zero critical, zero major, three medium findings resolved.
Ask for the report links on skynet.certik.com before repeating a result to a sceptic; an announcement is the project's word, a report is CertiK's.
Source: Long-form explainer, September 2026, Part II; Technical guide, September 2026, Part III; announcements of 13 July and 2 August 2026
Presentations state 450 milliseconds; the September 2026 data report says about one second; the network's technical documentation describes a two-second target; the docs.anubispace.org pages say 0.45 seconds. The live figure is on the explorer's latest-blocks view. Quote whichever you can show, and say where it comes from.
Source: Technical guide, September 2026, Part I
Press 'Question not answered' under the assistant, or the feedback button at the bottom of the screen, write the question as it was asked, and press Send. The library's assistant answers at once, and a copy can go to an email address left in the form. Every note also goes to the Phalanx team by email, and the next edition carries whatever was missing. Until then, say that you will find out rather than guessing.
A promoter who says 'I do not know, I will check' keeps more people than one who improvises a number.
Source: This page
The project proposes it: for every unit of capital entering Spartan OS, what protocol assets are created or acquired, what corresponding RM supply or future token liability is generated, how is that RM released into circulation, and what mechanisms exist to balance that supply against real market demand and liquidity?
And where to look for the answer: net RM issuance, buyback and burn volumes, POL and liquidity depth, retention behaviour, and how the system performed under market stress. The explorer, the dashboard and the Charge Incentive Pool page carry most of these figures; the 13 September fall and recovery is the one stress episode on record so far.
Source: Statement on how capital entering the protocol is treated, received 24 September 2026, reproduced in the Official section
Spartan OS separates three things a promoter tends to merge: capital flow, protocol accrual and holder value accrual. Capital entering a product follows that product's asset path (LP, treasury, POL, other protocol functions), and a product-specific split must not be presented as a universal revenue percentage. Treasury and liquidity are protocol accrual, not holder income. In the project's own signs: treasury ≠ holder dividend; liquidity ≠ holder dividend; price appreciation ≠ cash-flow distribution.
Holder value is described as indirect today: for RM through Turbo buy demand, locking, changes in circulating supply, burns, application utility and revenue-linked buyback and burn where it applies; for GD through the fixed 390,000 supply, governance rights and application utility. The next layer is external application revenue from GoPlay, TempleRaid and what follows, which can be tracked into treasury, liquidity, buyback and burn, or explicit distribution. Unless a contract or written protocol rule says X% of revenue goes to RM or GD holders, do not say it does. Capital flow ≠ revenue; protocol assets ≠ holder dividend; buyback and burn ≠ direct cash distribution.
Source: Response to Seven Due Diligence Questions, received 24 September 2026, reproduced in the Due diligence section
On-chain and checkable by anyone: wallet addresses, token contracts, RM and GD transfers, swaps, liquidity changes, burns, contract interactions, transaction hashes and final settlement. Off-chain and to be treated separately: parts of the AICS scoring computation, intent interpretation, external-data analysis, API calls and agent decisions. Spartan OS's own rule: a result on-chain does not mean the whole computation was on-chain.
The trust boundary as the project draws it: AI and off-chain infrastructure handle intelligence, analysis and execution logic; the blockchain verifies state, assets, transactions and settlement. Making off-chain computation itself verifiable would need public algorithms, oracles, TEEs, ZK proofs, signatures or validator networks, depending on the implementation, and none of that is claimed as deployed. So when someone asks whether the AICS score is on-chain, the answer is that the transactions it leads to are, and the scoring is not presented as verified on-chain.
Source: Response to Seven Due Diligence Questions, received 24 September 2026, reproduced in the Due diligence section
Two levels of proof, kept apart. Execution result: the transaction hash, the contract called, what left the wallet, what arrived and whether it settled, all readable on the explorer without trusting a 'Completed' message. Computation: why the agent decided, whether its inputs were right and whether each reasoning step was correct. The chain proves the first. It does not prove the second, and Spartan OS says so.
Cryptographic verification of the agent's internal computation would need TEEs, ZK proofs, oracles, validator networks or signatures, and is to be judged on whatever verification technology is actually deployed. The rule to pass on: never rely on an agent saying it finished; check that the chain shows it finished. Intent infrastructure such as dappOS is meant to spare the user the manual steps, with the asset outcome still returning to on-chain settlement.
Source: Response to Seven Due Diligence Questions, received 24 September 2026, reproduced in the Due diligence section
A development goal, in the project's words: 'these numbers represent development goals, not guarantees of returns or future RM prices.' The sequence it gives is 35M, 36M, 50M, then a larger global ecosystem, and it adds that RM's price will continue to be set by supply and demand, liquidity conditions and ecosystem development.
Quote the disclaimer with the number every time. The 35 million itself is the project's stated total capital foundation on 26 September 2026; the dashboard figures in Terms today are what a reader can check against it.
Source: Harry (Spartan OS), 'From a U-shaped recovery to a global ecosystem', forwarded to the Phalanx channel on 26 September 2026, reproduced whole in the Official section
Twenty-one addresses, published by the project's service accounts on 25 and 26 September 2026: RM, GD, USDT and DAI; the treasury; flexible, 180, 360 and 540-day staking; the 180, 360 and 540-day liquidity bonds; three long-term fixed bonds; the burn, community rewards, Turbo, activity score and stable vault contracts; and a charge incentive pool. Checked on browser.anubispace.org on 26 September: twenty are contracts with live transaction histories (the Turbo contract alone over a million transactions). The charge incentive pool address is not a contract on the explorer: a plain address with no transactions of its own. Treat it as unconfirmed and send nothing to it.
Source code is verified on the explorer for the USDT and DAI token contracts only; RM, GD and the product contracts are deployed but their source is not published for reading. Say so when asked: the bytecode and every transaction are public, the readable code is not, and the project can change that by verifying the contracts. The full table with counts is in Terms today.
Source: Spartan OS service accounts, contract list of 25 and 26 September 2026, checked on browser.anubispace.org on 26 September; the table in Terms today
Anubis against other chains. Spartan OS against other programmes.
Fees in a dollar-pegged unit instead of a volatile gas token. An encrypted mempool that prevents front-running by design. Privacy by choice with zero-knowledge proofs, while the protocol stays auditable. Final blocks with no reorganisation. Full Ethereum compatibility, so nothing is rewritten. And a foundation that owns the chain and funds what runs on it.
Each of these is described by Anubis in its own documentation; the mempool and privacy claims come from the Anubis Network documentation, the fee unit and chain ID are verifiable on chainlist.org. Two tables on this page: ours, against a typical EVM chain, and Anubis Chain's own eight-point comparison from the July 2026 infographic.
Source: Technical guide, September 2026, Part II; Long-form explainer, September 2026, Part II
The capital is released in daily portions from day one instead of being held to the end of the term. Every long-term position has a cap fixed in USDT at entry, pays until it reaches it, and the capital counts inside that cap (confirmed 26 September 2026). Two legs qualify a rank, not three. Every payout passes through the turbine and becomes a purchase. A sell tax that rises as the price falls slows cascades. A score pays the active leader more than the passive one. And it runs on a chain the same foundation owns.
As stated by Spartan OS in the 7 and 14 September 2026 briefings. Origin required three teams at $50,000; V1 here is $500, three people and two teams of $10,000.
Source: Promoter deck, 26 October 2026, slides 7, 11, 13, 14; Leader document, September 2026
On the chain: dollar-pegged gas, an encrypted mempool, selective privacy and gasless transactions through a paymaster, as described in the Anubis documentation. On Spartan OS: O², an adaptive balancing protocol that changes the rules with the market; the Token Router, which gives an AI agent its own token and settles its revenue on-chain; and a programme where the returns themselves are buy pressure.
Spartan OS positions O² as a global first. The Token Router is announced but not fully published. Describe what has been announced and stop there.
Source: Long-form explainer, September 2026, Parts II to IV; O² core interpretation deck, Spartan OS, September 2026; Anubis Chain documentation (docs.anubispace.org)
Five layers together, in the project's own account, and none of them alone: the economic layer (RM, GD, O², 1:1 Turbo, AICS, the Stable Vault, long-term staking and bonds, Energy, burn, compounding); the application layer (GoPlay, TempleRaid and what follows); the AI, intent and execution layer (dappOS-style infrastructure that turns an intent into routing and execution while settlement returns to the chain); the blockchain infrastructure (Anubis Chain with wallets, bridges, DEXs, explorers, indexing and cross-chain systems such as The Graph, Blockscout and LayerZero); and ecosystem expansion.
The roadmap from Q3: LayerZero and OFT cross-chain infrastructure, explorer upgrades, RocketSwap V3, Guard multisig, NFT and DID, AI Meme and AI Agent, RWA tokenisation, a decentralised contract-trading platform and contract-trading insurance. Spartan OS says itself that none of these may be presented as live revenue-generating products: live products are judged on usage and on-chain data, integrations on technical progress and official announcements, future products once deployed. It calls it premature to describe its moat as uncopyable; a network moat, to be shown through liquidity depth, active users, adoption, developer activity, external revenue and integrations.
Source: Response to Seven Due Diligence Questions, received 24 September 2026, reproduced in the Due diligence section
Both run 540 days, both carry a 5× cap, both earn through daily block production and both can compound. The bond is entered with USDT and its advantage is the discount: more RM at entry, then daily release of principal and rewards. Long-term staking is entered with USDT or RM and its advantage is the long-term yield plus the additional rewards. In the project's shorthand: bond = discounted entry, more RM, daily release, compounding, up to 5×; staking = USDT or RM entry, long-term yield, additional rewards, daily rewards, compounding, up to 5×.
The project's worked example: at an RM price of 30 and a bond price of 24, 10,000 USDT buys 333.3 RM at market and 416.7 RM through the bond, 83.4 more at entry. Ask the person which they want: more RM on day one, or the additional rewards of the stake. Both end on the last day of the term or at the cap, whichever comes first, and a cap reached early freezes the unreleased capital until a new, larger order is opened (as stated 16 October 2026).
Source: Spartan OS international team, working group, 25 September 2026, reproduced in the Official section
What people say against it, and the answer that holds. Short version to say, longer version if they push.
Ask what they mean, then answer the mechanism. A Ponzi pays old money with new money and hides it. Here every payout is a purchase: the turbine makes each claim buy the same amount of RM on the DEX before it is released, the treasury, the liquidity and the fund addresses are on a public explorer, and every long-term position has a cap fixed in dollars the day it opens.
The honest version has three parts. First, what is verifiable today: the bridge reserves on Etherscan, the treasury and liquidity figures on the dApp dashboard, RM trades and TempleRaid rounds on browser.anubispace.org, the CertiK assessment of the Spartan OS contracts (zero critical, zero major, three medium resolved). Second, what is the project's own statement rather than a fact you can check: the rates, the roadmap, the user numbers. Third, the risk: rates float, the price moves, the sell tax rises on the way down, and a cap means a position ends. Someone who hears all three from you will trust the rest. Not to say: Do not say 'it cannot be'. Do not compare it to a bank. Do not quote the annualised figure.
Source: Objection scripts, this page, September 2026
They are high, they float, and they are capped. 1.1% to 1.3% a day on a long-term position is the stated rate on the day; the cap is 4× to 5× of what went in, fixed in USDT; the flexible pool pays around 0.3% per twelve hours and can move. Say the cap in the same breath as the rate, every time.
Explain where the payout comes from as the project describes it: the RM emission, the sell fee split (0.5% platform, 1.2% buyback, 1.3% community, 2.0% ecosystem), the extra sell tax on the way down, and the turbine that turns every claim into a purchase. Then explain what limits it: the cap on every long-term position, the rebase snapshot, and the O² protocol that slows selling when the price falls. High and unlimited is a story. High, capped and dated is a term sheet. Not to say: Never say 'guaranteed'. Never project a month's income as if the rate were fixed.
Source: Objection scripts, this page, September 2026
Anubis Foundation, which built Origin (LGNS), WebKey and Melos, and now its own chain. Anubis Labs is the funding arm; Spartan OS is its first application. The team publishes under the foundation's name rather than personal names, which is common in this part of the industry and is a fair thing to dislike. What you can check is the work: the chain has been live since April 2026 with over 100 million transactions, and the contracts were assessed by CertiK.
The foundation's footprint is public: two years, five continents, a hundred projects, and Origin's snapshot of 2.5 million holders and a $1.4 billion market cap at its peak. Company management runs Spartan OS with a stated plan to run it for years, and to run it bigger and better than Origin. The Dubai office and the leader meetings are where people meet them in person. Say plainly that founders are not public by name, and that the person deciding should weigh a public codebase, a public chain and an audit against that. Not to say: Do not invent a founder's name or nationality. Do not claim to have met anyone you have not met.
Source: Objection scripts, this page, September 2026
Yes. RM is a traded token; the dollar value of every payout depends on the price on the day. Selling into a fall carries a tax that rises with the fall. TempleRaid is a game of chance. A long-term position cannot be unwound early. Anyone who tells you otherwise is not describing the programme.
Then describe what the project has built to reduce the damage, without turning it into a floor: caps fixed at entry so a position cannot chase, the turbine that converts claims into purchases, O² that raises the sell tax and protects liquidity when the price falls 5% or more against the three-hour average, the buyback fund, and the Price Stability Fund of 1,000,000 USDT at a published address. None of these is a guarantee. All of them are on the dApp or the explorer. Not to say: Do not say 'you cannot lose'. Do not say the price 'always comes back'.
Source: Objection scripts, this page, September 2026
You can, after one step. Every claim goes into the turbine: you buy the same amount of RM on RocketSwap, the claim unlocks after 24 hours, and the purchased RM is yours as well. Level income needs energy on top, one unit per RM, from a 360-day stake or from burning RM.
The turbine is the mechanism the project points to when asked how a token paying daily returns has stayed above $30 for months: the returns themselves are buy pressure. It also means every payout costs a matching purchase before it can be sold, which a promoter should say out loud. Energy applies only to the 8%, 4% and 2% level income, not to personal staking, bonds or rank rewards. Not to say: Do not describe the turbine as a fee. Do not skip the 24 hours.
Source: Objection scripts, this page, September 2026
Spartan OS completed a CertiK assessment on 2 August 2026: governance multisig, treasury, staking, reward distribution and core token contracts, with zero critical and zero major findings and three medium findings resolved. GaleBridge was audited by CertiK in October 2025. Anubis Chain states 137 core contracts verified with CertiK and Armor. Every bridged asset is minted one to one against assets locked in bridge contracts you can read on Etherscan.
Safety on the way in is mostly the user's own: chain ID 6714, addresses typed from this page, the first four and last four characters checked, a small test first, the seed phrase on paper. Two current notices matter: there is no official 'Anubischat' app, and CertiK warns about malicious code repackaged into iOS apps. Forward both. An audit covers the code. It does not cover a phishing link. Not to say: Do not say 'audited' without saying by whom and when. Do not send links from chats.
Source: Objection scripts, this page, September 2026
Then you already know the two questions that matter: what limits the payout, and what happens on the way down. Spartan OS answers the first with a cap fixed at entry and the second with O², the sell tax and the buyback fund. Origin required three legs; Spartan OS requires two. The codebase is the one Origin ran, on a chain the same foundation now owns.
Do not argue about the past. Ask what went wrong for them: usually an uncapped rate, an exit that was closed, or a promise from a promoter. Show the cap, show the turbine, show the sell tax table, and show the explorer. Then let them decide the size, and suggest a small position first. About $55 million remains in Origin's pool on Polygon two years on; that is a fact about longevity, not a promise about this one. Not to say: Do not disparage other projects by name. Do not promise this one is different; show what is different.
Source: Objection scripts, this page, September 2026
The programme pays for building a community, in the open: 8%, 4% and 2% of the ROI on three levels, then twelve ranks paid from the DAO pool on the smaller leg. The referral link is how the dApp knows who introduced whom. Nobody earns from a recruit's deposit; the level income is a share of what that person's own position earns.
Say what the rank structure demands before saying what it pays: your own position, a number of directs from 100 USDT, and volume in two legs, with the larger leg qualifying and the smaller one paying. Most people will sit at V1 to V3. Use the rank calculator with their real numbers rather than the top of the table. The referral link is theirs to use or not; the staking products pay the same either way. Not to say: Do not sell the ladder above V5 to someone who has not opened a first position. Do not call it 'passive'.
Source: Objection scripts, this page, September 2026
It stops paying. A 540-day position that took $1,000 has paid out $5,000 of RM value, principal included (confirmed 26 September 2026: the capital counts inside the cap and is not paid on top). If the cap arrives before day 540, the capital not yet released is frozen until you open a new 540-day order larger than that remainder; then it resumes its release on the original schedule (as stated 16 October 2026). If day 540 arrives first, rewards stop that day, cap reached or not. Either way you open a new order if you want to continue. Flexible staking has no cap and no term; the principal can be withdrawn at any time.
At the stated rates the 360 and 540-day positions reach their ceiling in about ten to eleven months, before the term ends; the 180-day position reaches the end of its term first, at about 3× of the entry, below its cap. The burning bond releases 250% of the order in about five and a half months at 1.5% a day. Say which one applies, and that all of this is arithmetic on today's stated rate, which floats. Not to say: Do not describe the cap as a loss. Do not promise a renewal on the same terms. Do not say the frozen capital is lost: it is released once the new order is active.
Source: Objection scripts, this page, September 2026
Because the foundation is, and because its community was built there first: Origin's 2.5 million holders, the Melos and WebKey users, the launch events in Kuala Lumpur and the region. The English material exists because that community is now being built here. The chain, the contracts and the explorer do not have a language.
This library exists for that reason: the official documents translated or reproduced as issued, the announcements in plain English with the date, the tutorials with English captions, and one place to check a figure. If a person's concern is really about accountability rather than language, answer it with the audit, the public chain and the meetings in Dubai. Not to say: Do not make it about nationality. Do not translate a number you have not checked.
Source: Objection scripts, this page, September 2026
You can. Do not. Start with an amount you would not miss, run one full cycle (stake, claim, turbine, release), then decide. The programme rewards long-term positions, and a long-term position cannot be unwound early, so the second decision should be made with the first one behind you.
A leader who tells a new person to start small is the leader that person stays with. Show the minimums: 1 USDT for staking and bonds, 500 USDT for the stability vault, 200 USDT for the extra-reward bucket on 360 and 540-day positions. Then show what each product pays at their number on the calculator, cap and date attached. Not to say: Do not set a target. Do not stack products for a stranger.
Source: Objection scripts, this page, September 2026
None, because that is not the model. Spartan OS says capital entering the protocol goes to the asset side, liquidity, treasury and protocol-owned liquidity, while RM is minted against it under the protocol's rules, locked, released in a controlled way and balanced by O². A percentage would describe a fund that splits deposits, which the project says it does not run.
Give the two sides in one breath: what protocol assets the money creates, and what future RM supply is created against it and how it reaches the market. Then hand over the project's own due-diligence question: for every unit of capital, what assets are created, what RM supply or future liability is generated, how it is released, and what balances it against real demand and liquidity. Point at the data that answers it: net RM issuance, buyback and burn volumes, POL and liquidity depth, retention, and the 13 September fall and recovery. Not to say: Do not invent a percentage to satisfy the question. Do not say the mechanisms guarantee anything; the statement says they cannot control behaviour.
Source: Objection scripts, this page, September 2026
That is the risk the design is built around, and the project says so in its own due-diligence answers. RM does not reach the market when it is minted: long-term staking, the 360 and 540-day bonds and compounding hold it back; every Turbo claim needs a purchase of the same size, which then sits in a 24-hour silent period; RM burned for Energy leaves supply for good; O² raises the sell-side protection when selling runs ahead of buying; and the applications are meant to consume it. None of that guarantees a price.
Give them the numbers to watch instead of an argument: new RM supply against circulating supply, Turbo buy demand, RM locked long term, RM burned, and liquidity depth. Those are the project's own metrics, and all of them are on the dashboard or the explorer. The one line to keep: the mechanisms improve the structure of supply and demand; whether demand grows enough to absorb supply is what the data will show, and nobody can promise it. Not to say: Do not say RM cannot fall. Do not say O² stops selling; it slows a cascade and gives liquidity time.
Source: Objection scripts, this page, September 2026
It is a game of chance with money at stake, on chain, with provable randomness and sixty-second rounds, and a player can lose what they enter. It is one application on Spartan OS, not the programme. Nobody needs to play it to stake.
The project describes an insurance mechanism behind it and the rounds are readable on the explorer. Say the risk before the feature, every time, and never send the game to someone who asked about staking. Not to say: Do not describe TempleRaid as income. Do not send it to anyone under 18 or in a jurisdiction where it is unlawful.
Source: Objection scripts, this page, September 2026
They are the project's numbers, with the project's own label on them. 35 million USDT is the stated total capital foundation on 26 September 2026; on 19 October 2026 the project stated 39 million (35 million in the RM/USDT pool, 4 million in reserve), and on 27 October 2026 40 million (36 million in the pool, 4 million in reserve) with 41 million as the next target. 36 million and 50 million are what the message to the international partners calls development goals, and the same paragraph says they are not guarantees of returns or of the RM price, which is set by supply and demand, liquidity and ecosystem development.
Send the message whole rather than the milestone line. Its argument is the opposite of a promise: the project reached 35 million through a cycle that included a correction and a period when confidence was tested, and it tells new markets that story so they do not mistake growth for a straight line. The reader can check the dashboard figures in Terms today against the 35 million and draw their own conclusion about the distance to 50. Not to say: Do not say 'we are going to 50 million'. Do not turn a goal into a date. Do not quote the milestones without the sentence that follows them.
Source: Objection scripts, this page, September 2026
Every official announcement since the mainnet, dated, with its link. Newest last.
Chain ID 6714, fees in gasDAI, PoSA consensus. Every later milestone counts from this day. Source link: https://browser.anubispace.org
Source: Anubis Chain, 8 April 2026, reproduced in the SpartanOS Resource Library
The first genesis-level ecosystem project opens the DAI/LGNS pair on RocketSwap with an initial pool the project states at about $163 million.
Source: Anubis Chain, 13 May 2026, reproduced in the SpartanOS Resource Library
AVE.ai adds cross-chain access and swap for AnubisChain assets. Source link: https://x.com/ANUBISCHAIN_/status/2066098355516981427
Source: Anubis Chain, 15 June 2026, reproduced in the SpartanOS Resource Library
The first Anubis Labs application opens. RM opens at $18.85, as later stated by Spartan OS. Source link: https://x.com/Spartan_Arena_/status/2066789503961010667
Source: Spartan OS, 16 June 2026, reproduced in the SpartanOS Resource Library
Ecosystem projects can submit token information for the AnubisChain section. Source link: https://x.com/Anubis_Labs/status/2069308169613091169
Source: Anubis Chain, 23 June 2026, reproduced in the SpartanOS Resource Library
CoinMarketCap, CoinGecko, DEXTools, Bitget Wallet, MyToken, Ave.ai, dappOS, RocketSwap, AuraOS, Ads3, Spartan OS and VEST listed as ecosystem partners. Source link: https://x.com/ANUBISCHAIN_/status/2070368709898879098
Source: Anubis Chain, 26 June 2026, reproduced in the SpartanOS Resource Library
Total value of official anchored assets as stated on the day, with both bridge contracts and the DAI mapped-asset contract published. Source link: https://x.com/ANUBISCHAIN_/status/2071216870569791658
Source: Anubis Chain, 28 June 2026, reproduced in the SpartanOS Resource Library
Up to three zero-gas transfers a day inside AnubisChain through Bitget Wallet, 0.1 gasDAI maximum each; cross-chain transactions excluded. Source link: https://x.com/ANUBISCHAIN_/status/2074407426812506327
Source: Anubis Chain, 7 July 2026, reproduced in the SpartanOS Resource Library
Round 3 of the Genesis Foundation Program allocates the fund; address published; used only to steady the RM market in abnormal volatility, under DAO oversight.
Source: Spartan OS, 10 July 2026, reproduced in the SpartanOS Resource Library
137 core smart contracts verified; asset reserves, issuance and transfers traceable. Source link: https://x.com/ANUBISCHAIN_/status/2076558678287593693
Source: Anubis Chain, 13 July 2026, reproduced in the SpartanOS Resource Library
As of 20 July: 12.13 million addresses, 38.49 million transactions, 9.05 million blocks, TVL $189.91 million, 2,650+ token types, 119 verified contracts, average block time about one second.
Source: Anubis Chain, 22 July 2026, reproduced in the SpartanOS Resource Library
AC Wallet becomes a gateway to AnubisChain assets; DEXTools data cited the same day placing AnubisChain 12th by trading volume and 10th by liquidity among chains. Source link: https://x.com/ANUBISCHAIN_/status/2081382013081354342
Source: Anubis Chain, 26 July 2026, reproduced in the SpartanOS Resource Library
Omnichain infrastructure and the OFT standard to be used for mainnet deployment and ecosystem integration; details to follow. Source link: https://x.com/ANUBISCHAIN_/status/2082878468900139147
Source: Anubis Chain, 31 July 2026, reproduced in the SpartanOS Resource Library
360-day staking or bond from 500 USDT: an extra 1.5% DOS airdrop; 540-day: 3%. The campaign closed on 31 August.
Source: Spartan OS, 1 August 2026, reproduced in the SpartanOS Resource Library
Governance multisig, treasury, staking, reward distribution and core token contracts: zero critical, zero major, three medium findings resolved. Source link: https://x.com/Anubis_Labs/status/2083889127552954824
Source: Anubis Labs, 2 August 2026, reproduced in the SpartanOS Resource Library
Single participations over 200 USDT in 360 or 540-day staking or bonds, or the RM Stable Vault, qualify for irregular airdrops from the pool; rules by official announcement.
Source: Spartan OS, 4 August 2026, reproduced in the SpartanOS Resource Library
An AI question-and-answer page for mainnet, wallet, security, privacy, swap and bridge questions. Source link: https://anubis-ai-web-production.up.railway.app
Source: Anubis Chain, 7 August 2026, reproduced in the SpartanOS Resource Library
14.10 million addresses, 10.64 million blocks, 938,000 transactions in 24 hours, 10,792 contracts; gas below $0.01. Source link: https://x.com/ANUBISCHAIN_/status/2086069847201603938
Source: Anubis Chain, 8 August 2026, reproduced in the SpartanOS Resource Library
First listings named: Upbit, Binance Alpha, Bitget, OKX, Gate. Source link: https://x.com/ANUBISCHAIN_/status/2087071234572079451
Source: Anubis Chain, 11 August 2026, reproduced in the SpartanOS Resource Library
Thirty days of tasks through AC Wallet, 12 August to 11 September. Source link: https://x.com/ANUBISCHAIN_/status/2087498654240403678
Source: Anubis Chain, 12 August 2026, reproduced in the SpartanOS Resource Library
Omnichain asset flow, ZK privacy infrastructure, fast low-cost transactions, DeFi, Awake NFT identity, on-chain governance, long-term incentives, AI and RWA. Source link: https://x.com/ANUBISCHAIN_/status/2089232962927706466
Source: Anubis Chain, 18 August 2026, reproduced in the SpartanOS Resource Library
74.73 million transactions, 15.61 million addresses, 1.079 million transactions in 24 hours, 13,000+ contracts, 250,149 DAI transfers. Source link: https://x.com/ANUBISCHAIN_/status/2091067320214942142
Source: Anubis Chain, 22 August 2026, reproduced in the SpartanOS Resource Library
GoPlay, described as the first Play-to-Co-Create platform, to launch TempleRaid on AnubisChain with RM, DAI and USDT supported first. Source link: https://x.com/Spartan_Arena_/status/2092234955883717088
Source: Spartan OS, 25 August 2026, reproduced in the SpartanOS Resource Library
Application fees by meeting size, hosting rules and the 150% performance condition for reimbursement.
Source: Spartan OS, 26 August 2026, reproduced in the SpartanOS Resource Library
Ecosystem reserve 4,000,000 USDT; RM stated at $25.122 rising to $29.9639.
Source: Spartan OS, 5 September 2026, reproduced in the SpartanOS Resource Library
Sixty-second rounds on AnubisChain, outcomes by provable randomness, RM and GD accepted. Source link: https://x.com/Spartan_Arena_/status/2096220807236120976
Source: Spartan OS, 6 September 2026, reproduced in the SpartanOS Resource Library
AC Wallet users brought into AnubisChain through a daily incentive campaign. Source link: https://x.com/Spartan_Arena_/status/2097190313282748724
Source: Spartan OS, 8 September 2026, reproduced in the SpartanOS Resource Library
Day 155: 102,934,209 transactions, 18,185,105 addresses, 16,533 contracts, block time 1.0 second, gas below $0.01. Source link: https://x.com/ANUBISCHAIN_/status/2097997490452939114
Source: Anubis Chain, 10 September 2026, reproduced in the SpartanOS Resource Library
From $32.84 to $25.12 and back above $30; RM/USDT liquidity about 29.03 million USDT, reserve 4 million, capital base stated at 33 million+.
Source: Spartan OS, 13 September 2026, reproduced in the SpartanOS Resource Library
On-chain infrastructure, ecosystem resources and application-level collaboration confirmed for Spartan OS. Source link: https://x.com/ANUBISCHAIN_/status/2099509073121350094
Source: Anubis Chain, 14 September 2026, reproduced in the SpartanOS Resource Library
Subgraph indexing live; developers can query on-chain data through The Graph. Source link: https://x.com/ANUBISCHAIN_/status/2099740662803595626
Source: Anubis Chain, 15 September 2026, reproduced in the SpartanOS Resource Library
The primary channel for ecosystem, partnership, product and official announcements from this date. Source link: https://x.com/Anubis_Labs/status/2100194475473838164
Source: Anubis Chain, 16 September 2026, reproduced in the SpartanOS Resource Library
Marina Bay Sands, 7 to 8 October 2026. Source link: https://x.com/AnubisChainL1/status/2100493181263421455
Source: Anubis Chain, 17 September 2026, reproduced in the SpartanOS Resource Library
Anubis Chain has never published a social app on any store; do not install one or connect a wallet to it. Source link: https://x.com/AnubisChainL1/status/2101183815293214950
Source: Anubis Chain, 19 September 2026, reproduced in the SpartanOS Resource Library
Malicious code repackaged into iOS apps can read keys, seed phrases and chat records; update to iOS 26.7, avoid unknown apps. Source link: https://x.com/Spartan_Arena_/status/2101680990913720441
Source: Anubis Chain × CertiK, 20 September 2026, reproduced in the SpartanOS Resource Library
A gold-badged primary account for announcements, technical developments, partnerships and global updates; @AnubisChainL1 becomes the ecosystem account. Both are official. Source link: https://x.com/AnubisChainL1/status/2108492587405566369
Source: Anubis Chain, 9 October 2026, reproduced in the SpartanOS Resource Library
Rewards stop when the 540-day term completes, cap reached or not; a cap reached early freezes the unreleased capital until a new, larger 540-day order is opened; a new order is needed to continue. The FAQ is reproduced in the Official section.
Source: Spartan OS, 16 October 2026, reproduced in the SpartanOS Resource Library
An agency for exchange listings, with a network of partner exchanges, joins Anubis Chain as a strategic partner, as announced. Source link: https://x.com/AnubisLayer1/status/2110989117408305401
Source: Anubis Chain, 16 October 2026, reproduced in the SpartanOS Resource Library
The official bridge appears on DeFiLlama, where its locked value can be read by anyone. Source link: https://x.com/AnubisChainL1/status/2110994404466934072
Source: Anubis Chain, 16 October 2026, reproduced in the SpartanOS Resource Library
35 million in the RM/USDT liquidity pool and 4 million in the ecosystem reserve, 45 countries, next milestone 40 million, as stated; development figures, not guarantees. Source link: https://t.me/spartanos_phalanx/102
Source: Spartan OS, 19 October 2026, reproduced in the SpartanOS Resource Library
One iPhone 18 Pro Max added to a conference's draw for every 100,000 USDT of verified new liquidity-bond participation at that conference; a single 360-day or 540-day LP bond of 3,000 USDT or more qualifies a person; the staking products do not count, nor do hedging deposits or internal transfers. Participation does not guarantee a prize; the bonds carry their lock-up and their risk. Source link: https://t.me/spartanos_phalanx/108
Source: Spartan OS, 21 October 2026, reproduced in the SpartanOS Resource Library
36 million in the RM/USDT liquidity pool and 4 million in the ecosystem reserve, 45 countries, next target 41 million, as stated; development figures, not guarantees. Source link: https://t.me/spartanos_phalanx/138
Source: Spartan OS, 27 October 2026, reproduced in the SpartanOS Resource Library
A Dubai event on 7 to 10 December 2026 (dates tentative) for leaders at V1 or above, up to five core leaders per V1+ team, with at least 10,000 USDT in long-term staking, subject to approval; round-trip flight and four days, three nights, as announced to the international teams. Source link: https://t.me/spartanos_phalanx/159
Source: Spartan OS, 30 October 2026, reproduced in the SpartanOS Resource Library
Communities ranked on new, verified deposits into 360-day and 540-day liquidity bonds (days counted in UTC+8): an iPhone 18 Pro Max for the daily champion, 100 g of gold for the weekly, a car for the month, as announced. The bonds carry their lock-up and their risk; a prize is not a return. Source link: https://t.me/spartanos_phalanx/182
Source: Spartan OS, 3 November 2026, reproduced in the SpartanOS Resource Library
Stargate, the LayerZero bridge, has integrated Anubis Chain, which can now reach the LayerZero network of chains; 44 asset routes across 33 assets were listed on 9 November. The Phalanx note of 7 November: technical connectivity is the first stage, cross-chain inside the Spartan OS dApp the second; its date and assets are to be confirmed by official announcement. Source link: https://x.com/AnubisLayer1/status/2118405709830541318
Source: Anubis Chain, 5 November 2026, reproduced in the SpartanOS Resource Library
Arabic, Russian, French, Spanish and German added to spartanar.org, as announced. Source link: https://t.me/spartanos_phalanx/190
Source: Spartan OS, 5 November 2026, reproduced in the SpartanOS Resource Library
As of 4 November 2026, as stated by Anubis Chain: DeFi TVL about 330 million dollars, more than 205 million transactions, more than 24.42 million addresses. The explorer stood at 218.8 million transactions and 26.3 million addresses on 9 November. Source link: https://x.com/AnubisLayer1/status/2118601175553728982
Source: Anubis Chain, 6 November 2026, reproduced in the SpartanOS Resource Library
The first tokenised stock assets launched on the chain's RWA sector (SPCXon, NVDAon, AAPLon among them), with 24-hour trading and fractional shares, as announced. Not a Spartan OS product; the Trading Center is unchanged. Source link: https://x.com/AnubisLayer1/status/2119713846143353226
Source: Anubis Chain, 9 November 2026, reproduced in the SpartanOS Resource Library
Statements reproduced as received, with the date received: the message to the international partners of 26 September, the bond texts of 25 September, the 540-day FAQ of 16 October, the asset-pegging statement and the account of how capital entering the protocol is treated. Quote them whole or not at all; a statement cut down in a chat becomes a claim of your own.
Anubis Chain has never launched or listed a social product on the Apple App Store, Google Play or any Android marketplace. Any app called Anubischat, or claiming affiliation, is not official and may be phishing. Do not install it, connect a wallet to it, or enter a seed phrase. Web3 social features will come through AstraCore Wallet, when announced on official channels.
Original postFollowing reports of asset theft linked to FomoPeek, malicious code may be repackaged into iOS apps and read private keys, seed phrases, login credentials, chat records and local files. Update to iOS 26.7, avoid apps from unknown sources, never enter keys or seed phrases into unofficial apps, keep the device updated.
Original postAnubis Chain opened a new gold-badged primary X account on 9 October 2026, @AnubisLayer1, for announcements, technical developments, partnerships and global updates. @AnubisChainL1, the primary account from 16 September, becomes the ecosystem account: infrastructure, partnerships, developer initiatives, ecosystem applications and community updates. Both are official; the earlier @ANUBISCHAIN_ posts remain the record for June to September.
Original postAnubis Chain Network adopts an official 1:1 asset-backed pegging mechanism.
All officially issued bridged assets on Anubis Chain, including USDT, USDC, DAI, ETH, BNB, POL, and other supported assets, are minted on Anubis Chain at a 1:1 ratio after users deposit the corresponding native assets from their source chains into the official asset-pegging bridge.
When users redeem their assets, the corresponding assets on Anubis Chain are burned, and the locked assets on the source chain are released accordingly. This mechanism is designed to ensure that all officially bridged assets on Anubis Chain are backed by corresponding reserves.
Supported source chains include major blockchain networks such as Ethereum, Polygon, BSC, and others.
The Anubis official bridge contracts and reserve assets are publicly visible on-chain. Users can independently verify the amount of assets locked in the bridge contracts through blockchain explorers and compare those reserves against the corresponding circulating supply of assets on Anubis Chain to verify the 1:1 backing relationship.
The asset balances held by the official bridge contracts, the total supply of corresponding assets on Anubis Chain, and source-chain transaction records can all be publicly verified on-chain, providing transparent and independently verifiable asset tracking throughout the entire process.
Used for locking source-chain assets and issuing corresponding assets on Anubis Chain at a 1:1 ratio.
Used for official cross-chain transactions and asset transfers.
Anubis Chain Official On-Chain Asset Pegging Statement

Anubis Chain Network adopts an official 1:1 asset-backed pegging mechanism.
All officially issued bridged assets on Anubis Chain, including USDT, USDC, DAI, ETH, BNB, POL, and other supported assets, are minted on Anubis Chain at a 1:1 ratio after users deposit the corresponding native assets from their source chains into the official asset-pegging bridge.
When users redeem their assets, the corresponding assets on Anubis Chain are burned, and the locked assets on the source chain are released accordingly. This mechanism is designed to ensure that all officially bridged assets on Anubis Chain are backed by corresponding reserves.
Supported source chains include major blockchain networks such as Ethereum, Polygon, BSC, and others.
The Anubis official bridge contracts and reserve assets are publicly visible on-chain. Users can independently verify the amount of assets locked in the bridge contracts through blockchain explorers and compare those reserves against the corresponding circulating supply of assets on Anubis Chain to verify the 1:1 backing relationship.
The asset balances held by the official bridge contracts, the total supply of corresponding assets on Anubis Chain, and source-chain transaction records can all be publicly verified on-chain, providing transparent and independently verifiable asset tracking throughout the entire process.

Official Asset-Pegging Main Bridge
Used for locking source-chain assets and issuing corresponding assets on Anubis Chain at a 1:1 ratio.
Contract address: 0x250ba4e73a365cefdd170a2b1ff9fc03097d64f3
Explorer: https://etherscan.io/address/0x250ba4e73a365cefdd170a2b1ff9fc03097d64f3#asset-multichain

Official Transaction Main Bridge
Used for official cross-chain transactions and asset transfers.
Contract address: 0x8932fe7726C1EE743F662f485C3e5a5D1D595F71
Explorer: https://etherscan.io/address/0x8932fe7726C1EE743F662f485C3e5a5D1D595F71#asset-multichain
Open the Etherscan link, read the balances the contract holds under the multichain asset tab, then compare them with the supply of the same asset on browser.anubispace.org. The statement says the two should match one to one. That comparison is the reader's to make; the page does not make it for them.
The project's account of how it reached 35 million USDT: the chain on 8 April, the market launch on 16 June, one complete cycle with a correction inside it, the recovery, and the culture the early communities took from it. Seven sections and a close. It tells a new partner to understand the history before the mechanisms, the returns or the price. Read it whole; the cards below it are the short versions.
A Message to Every Global Community Partner Joining SpartanOS
Today, more and more partners from India, the Middle East, Southeast Asia, and other parts of the world are joining SpartanOS.
For the international market, what you see is SpartanOS today:
Over 35 million USDT in total capital foundation, an expanding global community, a growing ecosystem, and a market entering a new stage of international development.
But before we talk about mechanisms, returns, or price, there is something even more important:
You need to understand how we got here.
Because the 35 million USDT we see today was not built overnight.
And the consensus we have today was not created by a single price rally.
From the launch of Anubis Chain on April 8, to the official market launch of SpartanOS on June 16, and now to a total capital foundation exceeding 35 million USDT and continuing toward the next milestone—
We have experienced a real and complete market cycle.
We have experienced rapid growth.
We have experienced price corrections.
We have seen moments of extreme market excitement.
And we have also experienced moments when confidence was tested.
Most importantly, we experienced a genuine U-shaped market recovery.
This is why the early communities understand the word "consensus" differently from someone who has just entered the ecosystem.
Because we learned one important lesson:
The true test of an ecosystem is not how many people believe in it when the market is rising. The real test is how many people are still willing to build when the market becomes difficult.
Through every market cycle, we gradually developed the community culture that exists today.
This is the first experience we want to share with our international communities.
When RM was rising rapidly and market sentiment was extremely strong, we realized something important:
If everyone focuses only on short-term profits, concentrated, large, and disorderly selling can create unnecessary pressure on liquidity and market sentiment—even when the protocol itself remains healthy.
That is why our communities began encouraging:
Rational trading. Distributed trading. Orderly market behavior.
This does not mean people are forbidden from selling.
And it certainly does not mean that anyone has the right to control another person's assets.
It means understanding one simple principle:
In a shared liquidity market, individual actions can affect the wider ecosystem.
And when the market entered a correction and prices moved lower, we did not stop building.
We continued community development.
We continued market education.
We continued events and ecosystem expansion.
We brought in new participants and encouraged more rational market behavior to reduce concentrated market pressure.
Eventually, we experienced the U-shaped recovery.
From that experience, we developed a very simple but important philosophy:
When prices are high, practice discipline. When prices are low, keep building.
During a rally, manage emotion. During a correction, strengthen confidence.
These are not rules written into a smart contract.
They are lessons learned through real market experience.
DeFi has already given the industry many important lessons.
Earlier-generation protocols, including Olympus DAO, demonstrated the power of economic mechanism design.
But they also taught the industry something equally important:
Economic mechanisms alone cannot solve every market problem.
SpartanOS therefore does not simply copy previous DeFi models.
We developed the O2 Adaptive Balancing Protocol.
O2 observes market conditions including supply and demand, TWAP, average transaction activity, buy/sell ratios, and liquidity depth.
When the market becomes imbalanced, protective mechanisms can be activated.
When conditions normalize, the system reassesses the data and adjusts accordingly.
That is why we often say:
Price is the result. Supply and demand are the cause. When imbalance appears, protection begins. When balance returns, adjustments follow.
But after experiencing real market cycles, we understand something even more clearly:
Mechanisms can adjust parameters. They cannot control human behavior.
Smart contracts can execute rules.
O2 can respond to market data.
AICS can evaluate network health.
But no code can guarantee that people will not become greedy during a rally.
And no algorithm can guarantee that people will not become fearful during a correction.
That is why SpartanOS has another equally important foundation:
COMMUNITY GOVERNANCE.
This is especially important for our new international communities to understand.
When we talk about community conventions, we are not saying:
"You are not allowed to sell."
On-chain assets belong to their owners.
Every participant has the right to make their own decisions.
What we want to build is a mature decentralized community culture:
You have freedom of choice, while also understanding how your choices may affect the wider market.
That is why our communities discuss market conditions.
We educate new participants.
We encourage people to avoid concentrated, large-scale, emotion-driven market behavior.
We encourage long-term participants to contribute more to ecosystem development.
And during difficult market conditions, we work together to find solutions rather than amplify fear.
This is what we mean by:
Community Governance.
True decentralization should not mean the absence of order.
And freedom should not mean the absence of responsibility.
The protocol does not make decisions for users. The community does not make decisions for users either.
But a mature community can help participants better understand the market so they can make more informed, responsible, and long-term decisions.
This is one of the most important lessons we have learned.
Because SpartanOS has entered a new stage.
In the past, much of the foundation was built by our early communities.
Today, India, the Middle East, Southeast Asia, and more international markets are joining.
At the same time, ecosystem development continues to move forward.
As more ecosystem applications, partners, external capital, liquidity, and global users enter, the scale of the market will become very different from what it was before.
35 million is not the destination.
We are continuing toward new liquidity and ecosystem milestones:
35M → 36M → 50M → A Larger Global Ecosystem
These numbers represent development goals, not guarantees of returns or future RM prices.
RM's market price will continue to be determined by actual supply and demand, liquidity conditions, and ecosystem development.
But one principle will remain unchanged:
The larger the ecosystem becomes, the more important consensus becomes.
When an ecosystem is small, a few core communities may be able to accomplish many things.
At 35 million, more communities must participate.
And if the ecosystem eventually develops toward 50 million, 100 million, or an even larger scale, we will no longer be dealing with a regional market.
We will be dealing with a truly global ecosystem.
At that point, market behavior in China, community activity in India, ecosystem expansion in the Middle East, and growth in Southeast Asia may all become interconnected parts of one global market.
Therefore, it is not only the protocol that must evolve.
Our global consensus must evolve with it.
That is exactly why we are sharing the experience of the early communities with our international partners today.
Not because we want you to repeat everything we experienced.
Quite the opposite.
We want the global market to benefit from the lessons we have already learned.
From today onward, the story of SpartanOS is changing.
In the past, we talked about how one market could grow.
In the future, the question becomes:
How can a global ecosystem grow together?
The future of SpartanOS does not belong to China.
It does not belong to India.
It does not belong to Dubai.
And it does not belong to any single community.
It belongs to everyone who genuinely contributes to building the ecosystem.
That is why the global culture we want to establish is simple:
When the market rises — stay rational. When the market corrects — do not panic. Respect individual choice — and respect the shared market. Pay attention to price — but pay even more attention to liquidity. Pay attention to returns — but also pay attention to the ecosystem. Think about today — but build for tomorrow.
Over the past several months, real market experience has taught us something very important:
Mechanisms without consensus are not enough.
And equally:
Consensus without strong mechanisms is not enough.
What SpartanOS is ultimately building is the combination of:
O2 + AICS + ECOSYSTEM DEVELOPMENT + COMMUNITY GOVERNANCE + GLOBAL CONSENSUS
O2 maintains adaptive balance.
AICS evaluates ecosystem health.
The ecosystem creates long-term demand and utility.
And the global community connects everything together.
Mechanisms can help us navigate volatility. But people are what allow an ecosystem to survive and grow through market cycles.
From April 8 to June 16.
From our first market challenges to a U-shaped recovery.
From the early market to more than 35 million USDT today.
And from 35 million toward 50 million and a much larger global ecosystem—
What we have accumulated is not only liquidity.
More importantly:
We have accumulated real experience in navigating markets, responding to volatility, and building long-term consensus.
Now, that experience is being passed from the early communities to the global market.
The next stage is not about one market leading another.
It is about Spartans from different countries, languages, and communities building together, protecting together, and witnessing the growth of this ecosystem together.
The protocol determines how we operate. The ecosystem determines how much value we can create. And global consensus determines how far we can go.
SPARTAN OS
FROM PROTOCOL TO ECOSYSTEM. FROM COMMUNITY TO GLOBAL. FROM CONSENSUS TO THE FUTURE.
FROM A U-SHAPED RECOVERY TO A GLOBAL ECOSYSTEM

A Message to Every Global Community Partner Joining SpartanOS

Today, more and more partners from India, the Middle East, Southeast Asia, and other parts of the world are joining SpartanOS.

For the international market, what you see is SpartanOS today:

Over 35 million USDT in total capital foundation, an expanding global community, a growing ecosystem, and a market entering a new stage of international development.

But before we talk about mechanisms, returns, or price, there is something even more important:

You need to understand how we got here.

Because the 35 million USDT we see today was not built overnight.

And the consensus we have today was not created by a single price rally.

1. FROM APRIL 8 TO TODAY — OUR JOURNEY HAS NEVER BEEN A STRAIGHT LINE

From the launch of Anubis Chain on April 8, to the official market launch of SpartanOS on June 16, and now to a total capital foundation exceeding 35 million USDT and continuing toward the next milestone—

We have experienced a real and complete market cycle.

We have experienced rapid growth.

We have experienced price corrections.

We have seen moments of extreme market excitement.

And we have also experienced moments when confidence was tested.

Most importantly, we experienced a genuine U-shaped market recovery.

This is why the early communities understand the word "consensus" differently from someone who has just entered the ecosystem.

Because we learned one important lesson:

The true test of an ecosystem is not how many people believe in it when the market is rising. The real test is how many people are still willing to build when the market becomes difficult.

Through every market cycle, we gradually developed the community culture that exists today.

2. WHEN PRICES RISE, WE LEARN DISCIPLINE. WHEN PRICES FALL, WE BUILD.

This is the first experience we want to share with our international communities.

When RM was rising rapidly and market sentiment was extremely strong, we realized something important:

If everyone focuses only on short-term profits, concentrated, large, and disorderly selling can create unnecessary pressure on liquidity and market sentiment—even when the protocol itself remains healthy.

That is why our communities began encouraging:

Rational trading. Distributed trading. Orderly market behavior.

This does not mean people are forbidden from selling.

And it certainly does not mean that anyone has the right to control another person's assets.

It means understanding one simple principle:

In a shared liquidity market, individual actions can affect the wider ecosystem.

And when the market entered a correction and prices moved lower, we did not stop building.

We continued community development.

We continued market education.

We continued events and ecosystem expansion.

We brought in new participants and encouraged more rational market behavior to reduce concentrated market pressure.

Eventually, we experienced the U-shaped recovery.

From that experience, we developed a very simple but important philosophy:

When prices are high, practice discipline. When prices are low, keep building.

During a rally, manage emotion. During a correction, strengthen confidence.

These are not rules written into a smart contract.

They are lessons learned through real market experience.

3. IF WE HAVE O2, WHY DO WE STILL PLACE SO MUCH IMPORTANCE ON PEOPLE?

DeFi has already given the industry many important lessons.

Earlier-generation protocols, including Olympus DAO, demonstrated the power of economic mechanism design.

But they also taught the industry something equally important:

Economic mechanisms alone cannot solve every market problem.

SpartanOS therefore does not simply copy previous DeFi models.

We developed the O2 Adaptive Balancing Protocol.

O2 observes market conditions including supply and demand, TWAP, average transaction activity, buy/sell ratios, and liquidity depth.

When the market becomes imbalanced, protective mechanisms can be activated.

When conditions normalize, the system reassesses the data and adjusts accordingly.

That is why we often say:

Price is the result. Supply and demand are the cause. When imbalance appears, protection begins. When balance returns, adjustments follow.

But after experiencing real market cycles, we understand something even more clearly:

Mechanisms can adjust parameters. They cannot control human behavior.

Smart contracts can execute rules.

O2 can respond to market data.

AICS can evaluate network health.

But no code can guarantee that people will not become greedy during a rally.

And no algorithm can guarantee that people will not become fearful during a correction.

That is why SpartanOS has another equally important foundation:

COMMUNITY GOVERNANCE.

4. COMMUNITY CONVENTIONS ARE NOT ABOUT RESTRICTION — THEY ARE ABOUT SELF-GOVERNANCE

This is especially important for our new international communities to understand.

When we talk about community conventions, we are not saying:

"You are not allowed to sell."

On-chain assets belong to their owners.

Every participant has the right to make their own decisions.

What we want to build is a mature decentralized community culture:

You have freedom of choice, while also understanding how your choices may affect the wider market.

That is why our communities discuss market conditions.

We educate new participants.

We encourage people to avoid concentrated, large-scale, emotion-driven market behavior.

We encourage long-term participants to contribute more to ecosystem development.

And during difficult market conditions, we work together to find solutions rather than amplify fear.

This is what we mean by:

Community Governance.

True decentralization should not mean the absence of order.

And freedom should not mean the absence of responsibility.

The protocol does not make decisions for users. The community does not make decisions for users either.

But a mature community can help participants better understand the market so they can make more informed, responsible, and long-term decisions.

This is one of the most important lessons we have learned.

5. WHY ARE WE SHARING THIS HISTORY WITH THE GLOBAL MARKET NOW?

Because SpartanOS has entered a new stage.

In the past, much of the foundation was built by our early communities.

Today, India, the Middle East, Southeast Asia, and more international markets are joining.

At the same time, ecosystem development continues to move forward.

As more ecosystem applications, partners, external capital, liquidity, and global users enter, the scale of the market will become very different from what it was before.

35 million is not the destination.

We are continuing toward new liquidity and ecosystem milestones:

35M → 36M → 50M → A Larger Global Ecosystem

These numbers represent development goals, not guarantees of returns or future RM prices.

RM's market price will continue to be determined by actual supply and demand, liquidity conditions, and ecosystem development.

But one principle will remain unchanged:

The larger the ecosystem becomes, the more important consensus becomes.

6. AS WE MOVE TOWARD 50 MILLION, WHAT MUST EVOLVE IS NOT ONLY THE MARKET — BUT OUR CONSENSUS

When an ecosystem is small, a few core communities may be able to accomplish many things.

At 35 million, more communities must participate.

And if the ecosystem eventually develops toward 50 million, 100 million, or an even larger scale, we will no longer be dealing with a regional market.

We will be dealing with a truly global ecosystem.

At that point, market behavior in China, community activity in India, ecosystem expansion in the Middle East, and growth in Southeast Asia may all become interconnected parts of one global market.

Therefore, it is not only the protocol that must evolve.

Our global consensus must evolve with it.

That is exactly why we are sharing the experience of the early communities with our international partners today.

Not because we want you to repeat everything we experienced.

Quite the opposite.

We want the global market to benefit from the lessons we have already learned.

7. THE PAST WAS ABOUT EARLY COMMUNITIES BUILDING CONSENSUS. THE FUTURE IS ABOUT THE WORLD BUILDING AN ECOSYSTEM TOGETHER.

From today onward, the story of SpartanOS is changing.

In the past, we talked about how one market could grow.

In the future, the question becomes:

How can a global ecosystem grow together?

The future of SpartanOS does not belong to China.

It does not belong to India.

It does not belong to Dubai.

And it does not belong to any single community.

It belongs to everyone who genuinely contributes to building the ecosystem.

That is why the global culture we want to establish is simple:

When the market rises — stay rational. When the market corrects — do not panic. Respect individual choice — and respect the shared market. Pay attention to price — but pay even more attention to liquidity. Pay attention to returns — but also pay attention to the ecosystem. Think about today — but build for tomorrow.

FROM REGIONAL CONSENSUS TO GLOBAL CONSENSUS

Over the past several months, real market experience has taught us something very important:

Mechanisms without consensus are not enough.

And equally:

Consensus without strong mechanisms is not enough.

What SpartanOS is ultimately building is the combination of:

O2 + AICS + ECOSYSTEM DEVELOPMENT + COMMUNITY GOVERNANCE + GLOBAL CONSENSUS

O2 maintains adaptive balance.

AICS evaluates ecosystem health.

The ecosystem creates long-term demand and utility.

And the global community connects everything together.

Mechanisms can help us navigate volatility. But people are what allow an ecosystem to survive and grow through market cycles.

From April 8 to June 16.

From our first market challenges to a U-shaped recovery.

From the early market to more than 35 million USDT today.

And from 35 million toward 50 million and a much larger global ecosystem—

What we have accumulated is not only liquidity.

More importantly:

We have accumulated real experience in navigating markets, responding to volatility, and building long-term consensus.

Now, that experience is being passed from the early communities to the global market.

The next stage is not about one market leading another.

It is about Spartans from different countries, languages, and communities building together, protecting together, and witnessing the growth of this ecosystem together.

The protocol determines how we operate. The ecosystem determines how much value we can create. And global consensus determines how far we can go.

SPARTAN OS

FROM PROTOCOL TO ECOSYSTEM. FROM COMMUNITY TO GLOBAL. FROM CONSENSUS TO THE FUTURE.
Conventions, in the project's words, never rules in a contract. Nobody is forbidden to sell and nobody may control another person's assets; the ask is that a member understands how a choice affects the shared market.
Tell the history in order and keep the correction in it: launch, growth, correction, confidence tested, recovery. The story is the project's argument for discipline, and it only works with the hard middle left in.
Quote the numbers with their labels. 35 million USDT is the stated total capital foundation on 26 September. 36M and 50M are development goals; the text says in its own words that they are not guarantees of returns or of the RM price.
Use it to answer "why do you keep talking about people if there is O²": mechanisms adjust parameters and cannot control behaviour, so the project names community governance as a second foundation. Do not use it to answer "what will I earn". That question belongs to the Terms today and the calculators, with a cap and a date.
Asked on 25 September whether the international market should copy regular staking or the bonds, Harry answered: the bonds, at this stage; the bond carries a discount, staking earns a larger quantity of coins. The four texts below followed the same morning: what 1,000 USDT bought at market and through each bond that day, the confirmation that bond principal and rewards release daily, the line that the discount is not fixed, and the side-by-side of the two 540-day products. Figures are that day's; the bond page is the reference.
Current Market Price: $30.8081
Buying directly at market price with 1,000 USDT: ≈ 32.459 RM
360-Day LP Bond. Bond Price: $27.5301. Discount vs. Market Price: ≈ 10.64% OFF. RM Received with 1,000 USDT: ≈ 36.324 RM. Additional RM vs. Direct Market Purchase: ≈ +3.865 RM
540-Day LP Bond. Bond Price: $26.2535. Discount vs. Market Price: ≈ 14.79% OFF. RM Received with 1,000 USDT: ≈ 38.090 RM. Additional RM vs. Direct Market Purchase: ≈ +5.631 RM
For both the 360-day and 540-day LP Bonds, you do not need to wait until maturity to receive your capital and profit. Both principal and rewards are released daily throughout the bond period.
The discount is not fixed. The protocol will be adjusted based on the actual circumstances.
Both products have a 540-day term and a maximum 5× cap.
Rewards are generated through daily block production, and the rewards generated can be continuously compounded to accelerate overall return accumulation.
540-Day Bond | Core Advantage: Discount + More RM
You enter with USDT, and the key advantage is the bond discount, which allows you to acquire more RM at a price below the current market price.
After entering, principal and rewards are progressively released daily. The daily rewards can also be compounded, with a maximum cap of 5×.
For example, with an investment of 10,000 USDT, assuming: RM Market Price: 30 USDT. 540-Day Bond Price: 24 USDT.
At market price: 10,000 ÷ 30 ≈ 333.3 RM
Through the 540-Day Bond: 10,000 ÷ 24 ≈ 416.7 RM
With the same 10,000 USDT, the bond discount gives you approximately 83.4 more RM at entry.
So the core advantage of the bond is: first gain more RM through the discounted entry price, then continue accumulating through daily release and compounding over the 540-day period.
540-Day Long-Term Staking | Core Advantage: Long-Term Yield + Additional Rewards
You can enter with either USDT or RM, and the assets participate in the 540-day long-term staking cycle.
Unlike the bond, the main focus is not acquiring additional RM through a discounted bond price. Instead, the mechanism focuses on long-term yield plus additional rewards.
Rewards are generated daily through block production and can also be continuously compounded to accelerate accumulation, with a maximum cap of 5×.
In simple terms:
540-Day Bond = Discounted RM Entry + More RM at Entry + Daily Principal & Reward Release + Compounding + Up to 5× Cap
540-Day Long-Term Staking = USDT/RM Entry + Long-Term Yield + Additional Rewards + Daily Block Rewards + Compounding + Up to 5× Cap
Both have a 540-day term, a maximum 5× cap, and compounding capability. The key difference is that the Bond focuses on the discount and RM quantity advantage, while Long-Term Staking focuses on long-term yield and additional rewards.
1000 USDT RM Purchase Comparison

Current Market Price: $30.8081

Buying directly at market price with 1,000 USDT: ≈ 32.459 RM

360-Day LP Bond. Bond Price: $27.5301. Discount vs. Market Price: ≈ 10.64% OFF. RM Received with 1,000 USDT: ≈ 36.324 RM. Additional RM vs. Direct Market Purchase: ≈ +3.865 RM

540-Day LP Bond. Bond Price: $26.2535. Discount vs. Market Price: ≈ 14.79% OFF. RM Received with 1,000 USDT: ≈ 38.090 RM. Additional RM vs. Direct Market Purchase: ≈ +5.631 RM

Is the profit paid only after 360 or 540 days, or daily?

For both the 360-day and 540-day LP Bonds, you do not need to wait until maturity to receive your capital and profit. Both principal and rewards are released daily throughout the bond period.

Is the discount fixed?

The discount is not fixed. The protocol will be adjusted based on the actual circumstances.

540-Day Bond vs. 540-Day Long-Term Staking

Both products have a 540-day term and a maximum 5× cap.

Rewards are generated through daily block production, and the rewards generated can be continuously compounded to accelerate overall return accumulation.

540-Day Bond | Core Advantage: Discount + More RM

You enter with USDT, and the key advantage is the bond discount, which allows you to acquire more RM at a price below the current market price.

After entering, principal and rewards are progressively released daily. The daily rewards can also be compounded, with a maximum cap of 5×.

For example, with an investment of 10,000 USDT, assuming: RM Market Price: 30 USDT. 540-Day Bond Price: 24 USDT.

At market price: 10,000 ÷ 30 ≈ 333.3 RM

Through the 540-Day Bond: 10,000 ÷ 24 ≈ 416.7 RM

With the same 10,000 USDT, the bond discount gives you approximately 83.4 more RM at entry.

So the core advantage of the bond is: first gain more RM through the discounted entry price, then continue accumulating through daily release and compounding over the 540-day period.

540-Day Long-Term Staking | Core Advantage: Long-Term Yield + Additional Rewards

You can enter with either USDT or RM, and the assets participate in the 540-day long-term staking cycle.

Unlike the bond, the main focus is not acquiring additional RM through a discounted bond price. Instead, the mechanism focuses on long-term yield plus additional rewards.

Rewards are generated daily through block production and can also be continuously compounded to accelerate accumulation, with a maximum cap of 5×.

In simple terms:

540-Day Bond = Discounted RM Entry + More RM at Entry + Daily Principal & Reward Release + Compounding + Up to 5× Cap

540-Day Long-Term Staking = USDT/RM Entry + Long-Term Yield + Additional Rewards + Daily Block Rewards + Compounding + Up to 5× Cap

Both have a 540-day term, a maximum 5× cap, and compounding capability. The key difference is that the Bond focuses on the discount and RM quantity advantage, while Long-Term Staking focuses on long-term yield and additional rewards.
A leader asked what happens when the full 540 days elapse, rather than when the 5× cap is reached early, for the 540-day USDT liquidity bond and 540-day long-term staking alike. The FAQ below is the answer. The term is the fixed reward period and rewards stop when it completes, cap reached or not; a cap reached early freezes the unreleased capital until a new, larger 540-day order is opened; a new order is needed to continue. One reading note: the example reaches the cap on day 400 with part of the capital still unreleased, which the stated 4× interest limit on its own would not produce; the two limits are stated separately, and the position screen on the day is the reference. This answer replaces the 25 September reading that a position keeps paying until the cap, whatever its term; the cards, the calculator and the plain guide follow it.
Applicable to: 540-Day USDT Long-Term Liquidity Bonds and 540-Day Long-Term Staking.
Yes. The 540-day period is the fixed reward-generating term of the product.
Regardless of whether the 5× cumulative return cap has been reached, all rewards will stop accruing once the order completes its 540-day term. The original order will not automatically extend its reward period.
If a participant wishes to continue earning rewards, they must open a new 540-day order to begin a new reward cycle.
No.
The 540-day term and the 5× cumulative return cap are two separate rules.
The product's cumulative return structure is as follows:
• Principal: 1×
• Interest: 4× (Base Interest + Additional Interest)
• Maximum Cumulative Return: 5×
The principal is released linearly, second by second, over the 540-day period. Interest is distributed according to the product's base interest and additional interest mechanisms.
Even if the order has not reached the 5× cumulative return cap by Day 540, it will stop generating new rewards. Rewards will not continue accumulating beyond the 540-day term simply to reach the 5× cap.
Yes. To continue earning rewards, the participant must open a new 540-day order.
The new order will begin its own independent 540-day reward cycle and operate under the standard 5× cumulative return cap.
Regarding whether RM or USDT can be used, this depends on the selected product.
The 540-Day Long-Term Staking product and the 540-Day USDT Long-Term Liquidity Bond are two different products. The accepted participation assets must follow the specific rules of each product.
If an order reaches the 5× cumulative return cap before the end of its 540-day term, the system activates the return-cap mechanism.
Any remaining unreleased principal will be frozen. It will stop being released and will not generate additional rewards.
Assume a participant opens a 540-day long-term product order worth 1,000 USDT.
• Principal: 1,000 USDT equivalent
• Maximum Interest: 4,000 USDT equivalent
• Maximum Cumulative Return: 5,000 USDT equivalent
• Principal Release Period: 540 days
Suppose that on Day 400, the total amount released through principal, base interest, and additional interest has already reached the 5× cumulative return cap.
At that point, 140 days of the original principal release schedule remain.
The unreleased portion of the principal will be frozen.
The participant must open a new 540-day order with an amount greater than the remaining unreleased principal of the original order.
Once the new order meets the activation requirements:
1. The frozen principal from the original order will resume being released.
2. The remaining principal will continue to be released linearly, second by second, according to its original release schedule, until fully released.
3. The new order will operate independently, beginning a new 540-day reward cycle with its own standard 5× cumulative return cap.
4. The original order's interest rewards will not restart, as the original order has already reached its 5× cumulative return cap.
540 days is the fixed reward-generating term, while 5× is the maximum cumulative return cap.
Upon normal expiration of the 540-day term, all rewards stop accruing, regardless of whether the 5× cap has been reached.
If the 5× cap is reached early, any remaining unreleased principal will be frozen.
SpartanOS 540-Day Long-Term Products – Frequently Asked Questions (FAQ)

Applicable to: 540-Day USDT Long-Term Liquidity Bonds and 540-Day Long-Term Staking.

1. On Day 540, will the existing position automatically end and stop generating rewards, regardless of whether the 5× total return cap has been reached?

Yes. The 540-day period is the fixed reward-generating term of the product.

Regardless of whether the 5× cumulative return cap has been reached, all rewards will stop accruing once the order completes its 540-day term. The original order will not automatically extend its reward period.

If a participant wishes to continue earning rewards, they must open a new 540-day order to begin a new reward cycle.

2. If the 5× cumulative return cap has not been reached by Day 540, will rewards continue accumulating until the cap is reached?

No.

The 540-day term and the 5× cumulative return cap are two separate rules.

The product's cumulative return structure is as follows:

• Principal: 1×

• Interest: 4× (Base Interest + Additional Interest)

• Maximum Cumulative Return: 5×

The principal is released linearly, second by second, over the 540-day period. Interest is distributed according to the product's base interest and additional interest mechanisms.

Even if the order has not reached the 5× cumulative return cap by Day 540, it will stop generating new rewards. Rewards will not continue accumulating beyond the 540-day term simply to reach the 5× cap.

3. After the 540-day term expires, is it necessary to open a new order to continue participating? Can previously released RM be used, or must new USDT be deposited?

Yes. To continue earning rewards, the participant must open a new 540-day order.

The new order will begin its own independent 540-day reward cycle and operate under the standard 5× cumulative return cap.

Regarding whether RM or USDT can be used, this depends on the selected product.

The 540-Day Long-Term Staking product and the 540-Day USDT Long-Term Liquidity Bond are two different products. The accepted participation assets must follow the specific rules of each product.

4. What happens if the 5× cumulative return cap is reached before Day 540?

If an order reaches the 5× cumulative return cap before the end of its 540-day term, the system activates the return-cap mechanism.

Any remaining unreleased principal will be frozen. It will stop being released and will not generate additional rewards.

Example

Assume a participant opens a 540-day long-term product order worth 1,000 USDT.

• Principal: 1,000 USDT equivalent

• Maximum Interest: 4,000 USDT equivalent

• Maximum Cumulative Return: 5,000 USDT equivalent

• Principal Release Period: 540 days

Suppose that on Day 400, the total amount released through principal, base interest, and additional interest has already reached the 5× cumulative return cap.

At that point, 140 days of the original principal release schedule remain.

The unreleased portion of the principal will be frozen.

How can the frozen principal be unlocked?

The participant must open a new 540-day order with an amount greater than the remaining unreleased principal of the original order.

Once the new order meets the activation requirements:

1. The frozen principal from the original order will resume being released.

2. The remaining principal will continue to be released linearly, second by second, according to its original release schedule, until fully released.

3. The new order will operate independently, beginning a new 540-day reward cycle with its own standard 5× cumulative return cap.

4. The original order's interest rewards will not restart, as the original order has already reached its 5× cumulative return cap.

Summary

540 days is the fixed reward-generating term, while 5× is the maximum cumulative return cap.

Upon normal expiration of the 540-day term, all rewards stop accruing, regardless of whether the 5× cap has been reached.

If the 5× cap is reached early, any remaining unreleased principal will be frozen.
The project's own account of its economy: the asset side and the token supply side, the three layers (protocol rules, AICS, O²), the 1:1 Turbo Engine, the AICS formula Score = 0.2H + 0.4C + 0.2A + 0.2R, and the line that mechanisms cannot control human behaviour. Read it whole before quoting any part of it.
The question is: "How many % of total deposits in Spartan goes to the network out of 100%?"
The key point is that SpartanOS should not be understood as a traditional fund-distribution or revenue-sharing model. If we simply answered this question with "20%," "30%," or "50%," it would create the wrong impression that every $100 entering SpartanOS is immediately divided into fixed portions and distributed to different parties. That is not how the SpartanOS economic model works.
The fundamental logic of SpartanOS is not: $100 comes in → X% goes to the network → X% goes to rewards → X% goes somewhere else.
Instead, when capital enters SpartanOS, we need to look at two different sides of the economic system.
1. The Asset Side. Capital entering the protocol contributes to protocol assets, liquidity, treasury/POL capacity, and the overall economic foundation of the system.
2. The Token Supply Side. RM is minted, locked, released, repurchased or burned according to the rules of the protocol and the specific product being used.
These two sides interact with each other, but they are not the same thing. Therefore: capital deposited into the protocol ≠ money that is immediately divided and paid out as RM rewards. This distinction is extremely important.
A useful historical reference is the treasury-and-bond model pioneered by protocols such as Olympus. The core concept was not: new users deposit $100, and part of that $100 is directly distributed to previous users. Instead, the protocol could acquire assets or liquidity through bonds, while token supply was created according to predefined protocol rules.
Conceptually: assets enter the protocol → Treasury / Protocol-Owned Liquidity increases; while, on the other side: protocol rules → token minting → token release over time.
This introduced an important concept into DeFi: future token supply can be used to acquire assets and liquidity that the protocol needs today. Therefore, the economic system cannot be accurately analyzed simply by asking how each $100 deposit is divided.
This is the next and more important issue. A protocol can have a sophisticated minting mechanism, but eventually every token economy has to answer one fundamental question: can real market demand absorb the newly created token supply?
If RM supply is released faster than genuine market demand can absorb it, selling pressure can increase. So the real economic question is not simply "How much money entered the system?" The more important question is: "How much new RM supply is entering circulation, and can market demand and liquidity absorb that supply?" This is where SpartanOS moves beyond a simple minting model.
SpartanOS does not operate simply as: deposit → mint RM → release RM. Between token creation and the secondary market, SpartanOS introduces the O2 Adaptive Balancing Protocol.
O2 is designed around the relationship between supply, demand and market liquidity. It monitors multiple market indicators, including TWAP, buy volume, sell volume, average execution prices, buy/sell ratios, liquidity depth, and overall market supply-demand conditions. The system evaluates market conditions on a recurring cycle. When the market becomes imbalanced, the protocol can increase protective measures on the sell side. When supply and demand return toward equilibrium, the system reassesses conditions and can gradually adjust those protections back according to protocol rules.
So O2 is not asking "We received $100. How much of it should we distribute?" O2 is asking "What is happening between RM supply, real buying demand, selling pressure and available liquidity right now?" That is a fundamentally different economic model.
Suppose $100 enters SpartanOS. It should not be understood like this: $100 deposit → $20 to the network → $20 to the community → $20 to rewards → $40 to treasury. That would be a traditional fund-allocation model. The SpartanOS logic is different.
The $100 entering the protocol contributes to the asset side of the protocol economy, including liquidity, treasury/POL or other protocol asset functions depending on the product. At the same time, the protocol determines the corresponding RM minting and future release obligations according to its economic rules. That RM does not necessarily enter the open market immediately. There are additional mechanisms involving: locking → release → 1:1 Turbo demand → buyback → burn → O2 adaptive balancing.
Therefore, what matters economically is not simply "How much of the $100 was distributed?" What matters is: "What protocol asset value was created by that $100, what future RM supply was created against it, how and when that RM enters circulation, and how the market absorbs that supply."
There is no accurate fixed formula such as "$100 deposited = X% goes to the network." That framing assumes the wrong economic model. A more accurate representation of SpartanOS is: capital enters the protocol → protocol assets / treasury / POL / liquidity → RM minting according to protocol rules → RM locking and controlled release → secondary-market supply and demand → O2 monitors market conditions → buyback / burn / protection / liquidity mechanisms respond to market conditions → the system moves toward a new supply-demand equilibrium.
So, in simple terms: SpartanOS does not simply divide deposits; it manages a token economy. O2's role is to dynamically balance RM supply, market demand and liquidity. And this is why evaluating SpartanOS only by asking "what percentage of every deposit goes to the network?" does not accurately describe how the protocol works.
A more meaningful due-diligence question would be: "For every unit of capital entering SpartanOS, what protocol assets are created or acquired, what corresponding RM supply or future token liability is generated, how is that RM released into circulation, and what mechanisms exist to balance that supply against real market demand and liquidity?" That question gets much closer to the actual economics of SpartanOS.
Here is one more important design principle that needs to be clarified. SpartanOS is not designed to sustain itself through a permanently fixed set of high-yield parameters. A more scientific way to understand the system is to separate it into three layers: Protocol Rules, Network Incentives, and Market Balancing.
1. Protocol Rules Layer. Different staking periods, bonds, long-term staking products, release schedules, and maximum reward multiples are governed by defined product and protocol rules. These parameters form the underlying framework of the economic model. They are not simply changed arbitrarily on a daily basis.
2. Network Incentive Layer — AICS. The second layer is AICS, which focuses on network health. SpartanOS is not designed to determine long-term network rewards solely based on how many people someone recruits or how much volume a network generates. Instead, AICS continuously evaluates the quality and health of network participation. The current AICS scoring model is: Score = 0.2H + 0.4C + 0.2A + 0.2R, with a 30-day rolling evaluation period. The assessment considers factors such as holder participation, effective accounts, the proportion of long-term participation, retention, activity, and contribution to the overall ecosystem and liquidity. Therefore, even two networks at the same level do not necessarily receive identical effective incentives over time. If a network increases long-term participation, retention, active addresses and constructive ecosystem contribution, its health assessment can improve. Conversely, if selling increases significantly, retention decreases, long-term participation declines, or positive contribution to liquidity weakens, its AICS assessment can also adjust accordingly. In other words: network rewards are not determined only by network size; they are increasingly linked to network quality and health.
3. Market Balancing Layer — O2 Adaptive Balancing Protocol. AICS, however, cannot solve secondary-market supply-and-demand imbalances by itself. That is the role of O2. O2 operates around a three-hour observation and reassessment cycle. It does not simply react to whether the RM price goes up or down. Instead, it evaluates multiple market indicators, including buy volume, sell volume, TWAP, average execution price, buy/sell ratio, liquidity depth, and overall supply-and-demand conditions. The underlying principle is simple: price is the result; supply and demand are the cause. When RM supply and demand become significantly imbalanced, O2 can increase sell-side protection. When market conditions return toward the protocol-defined healthy range, O2 continues reassessing conditions on its three-hour cycle and can gradually step protections back toward their normal level rather than removing them abruptly. Under the current design, returning to the normal baseline requires the relevant conditions to remain satisfied continuously. Economically, this functions as an adaptive safety valve at the execution layer.
4. Creating Demand Alongside Supply — The 1:1 Turbo Engine. SpartanOS also contains another important supply-demand mechanism: the 1:1 Turbo Engine. Under the relevant reward mechanism, participation can generate a corresponding 1:1 compulsory RM purchase requirement, together with a holding/silent-period mechanism. The purpose is important: the system is not designed only to create token emissions. It also attempts to create corresponding market demand for RM while rewards and token supply are being generated and released.
So when we look at SpartanOS as a complete system, there are effectively three layers of control: Protocol Rules define how assets enter, lock, mint and release; AICS adjusts incentives according to network health; O2 adjusts market protection according to market health. These mechanisms then interact with the Turbo Engine, buybacks, burns, long-term locking, bonds and POL, affecting both the supply side and demand side of RM.
Therefore, when we say that SpartanOS has dynamic elements in both its active and passive incentive structures, a more technically accurate explanation is: the underlying product rules provide the framework, while effective network incentives and market-protection parameters are not necessarily permanent fixed values. They can adapt according to network health and market health. This is an important structural distinction between SpartanOS and models that rely primarily on fixed APYs, fixed referral incentives, or fixed allocation of incoming capital.
The key concept is not simply that parameters can "float." The more important concept is that SpartanOS attempts to establish feedback loops: network behavior changes → AICS reassesses network health; market supply and demand change → O2 reassesses market health.
In one sentence: AICS manages network health; O2 manages market health. AICS evaluates whether internal network growth and participation remain healthy, while O2 evaluates whether external RM supply, demand and liquidity remain balanced. One addresses the quality of incentives; the other addresses the balance of the market. The protocol rules define the framework, AICS adapts incentives, and O2 adapts market protection.
Importantly, these mechanisms are designed to improve long-term sustainability and resilience, rather than guarantee permanent price or yield stability. Whether they achieve that objective over time should ultimately be evaluated through actual on-chain data, including net RM issuance, buyback and burn volumes, POL/liquidity depth, retention behavior, and performance under market stress.
We have to recognize a fundamental reality of decentralized protocols: a protocol can manage mechanisms, but it cannot control human behavior. Even with O2 Adaptive Balancing, sudden large-scale selling pressure and market shocks cannot be completely avoided. O2 manages supply-demand balance, while AICS manages network health. These mechanisms can reduce risk, but they cannot eliminate participants' freedom of choice.
That is why we place great importance on consensus education, community guidelines, and long-term community culture, not to restrict anyone's freedom to trade, but to help participants understand how individual behavior can affect the broader ecosystem. Mechanisms maintain balance; consensus builds long-term value. Together, they create a healthier and more resilient ecosystem.
The question is: "How many % of total deposits in Spartan goes to the network out of 100%?"

The key point is that SpartanOS should not be understood as a traditional fund-distribution or revenue-sharing model. If we simply answered this question with "20%," "30%," or "50%," it would create the wrong impression that every $100 entering SpartanOS is immediately divided into fixed portions and distributed to different parties. That is not how the SpartanOS economic model works.

SpartanOS Is a Minting-Based Protocol Economy

The fundamental logic of SpartanOS is not: $100 comes in → X% goes to the network → X% goes to rewards → X% goes somewhere else.

Instead, when capital enters SpartanOS, we need to look at two different sides of the economic system.

1. The Asset Side. Capital entering the protocol contributes to protocol assets, liquidity, treasury/POL capacity, and the overall economic foundation of the system.

2. The Token Supply Side. RM is minted, locked, released, repurchased or burned according to the rules of the protocol and the specific product being used.

These two sides interact with each other, but they are not the same thing. Therefore: capital deposited into the protocol ≠ money that is immediately divided and paid out as RM rewards. This distinction is extremely important.

The Historical Logic: Treasury + Bonds + Minting + POL

A useful historical reference is the treasury-and-bond model pioneered by protocols such as Olympus. The core concept was not: new users deposit $100, and part of that $100 is directly distributed to previous users. Instead, the protocol could acquire assets or liquidity through bonds, while token supply was created according to predefined protocol rules.

Conceptually: assets enter the protocol → Treasury / Protocol-Owned Liquidity increases; while, on the other side: protocol rules → token minting → token release over time.

This introduced an important concept into DeFi: future token supply can be used to acquire assets and liquidity that the protocol needs today. Therefore, the economic system cannot be accurately analyzed simply by asking how each $100 deposit is divided.

But Minting Alone Does Not Solve the Economic Problem

This is the next and more important issue. A protocol can have a sophisticated minting mechanism, but eventually every token economy has to answer one fundamental question: can real market demand absorb the newly created token supply?

If RM supply is released faster than genuine market demand can absorb it, selling pressure can increase. So the real economic question is not simply "How much money entered the system?" The more important question is: "How much new RM supply is entering circulation, and can market demand and liquidity absorb that supply?" This is where SpartanOS moves beyond a simple minting model.

Why O2 Is Important to SpartanOS

SpartanOS does not operate simply as: deposit → mint RM → release RM. Between token creation and the secondary market, SpartanOS introduces the O2 Adaptive Balancing Protocol.

O2 is designed around the relationship between supply, demand and market liquidity. It monitors multiple market indicators, including TWAP, buy volume, sell volume, average execution prices, buy/sell ratios, liquidity depth, and overall market supply-demand conditions. The system evaluates market conditions on a recurring cycle. When the market becomes imbalanced, the protocol can increase protective measures on the sell side. When supply and demand return toward equilibrium, the system reassesses conditions and can gradually adjust those protections back according to protocol rules.

So O2 is not asking "We received $100. How much of it should we distribute?" O2 is asking "What is happening between RM supply, real buying demand, selling pressure and available liquidity right now?" That is a fundamentally different economic model.

A Simple $100 Example

Suppose $100 enters SpartanOS. It should not be understood like this: $100 deposit → $20 to the network → $20 to the community → $20 to rewards → $40 to treasury. That would be a traditional fund-allocation model. The SpartanOS logic is different.

The $100 entering the protocol contributes to the asset side of the protocol economy, including liquidity, treasury/POL or other protocol asset functions depending on the product. At the same time, the protocol determines the corresponding RM minting and future release obligations according to its economic rules. That RM does not necessarily enter the open market immediately. There are additional mechanisms involving: locking → release → 1:1 Turbo demand → buyback → burn → O2 adaptive balancing.

Therefore, what matters economically is not simply "How much of the $100 was distributed?" What matters is: "What protocol asset value was created by that $100, what future RM supply was created against it, how and when that RM enters circulation, and how the market absorbs that supply."

So What Is the Correct Answer?

There is no accurate fixed formula such as "$100 deposited = X% goes to the network." That framing assumes the wrong economic model. A more accurate representation of SpartanOS is: capital enters the protocol → protocol assets / treasury / POL / liquidity → RM minting according to protocol rules → RM locking and controlled release → secondary-market supply and demand → O2 monitors market conditions → buyback / burn / protection / liquidity mechanisms respond to market conditions → the system moves toward a new supply-demand equilibrium.

So, in simple terms: SpartanOS does not simply divide deposits; it manages a token economy. O2's role is to dynamically balance RM supply, market demand and liquidity. And this is why evaluating SpartanOS only by asking "what percentage of every deposit goes to the network?" does not accurately describe how the protocol works.

A more meaningful due-diligence question would be: "For every unit of capital entering SpartanOS, what protocol assets are created or acquired, what corresponding RM supply or future token liability is generated, how is that RM released into circulation, and what mechanisms exist to balance that supply against real market demand and liquidity?" That question gets much closer to the actual economics of SpartanOS.

Three Layers: Protocol Rules, Network Incentives, Market Balancing

Here is one more important design principle that needs to be clarified. SpartanOS is not designed to sustain itself through a permanently fixed set of high-yield parameters. A more scientific way to understand the system is to separate it into three layers: Protocol Rules, Network Incentives, and Market Balancing.

1. Protocol Rules Layer. Different staking periods, bonds, long-term staking products, release schedules, and maximum reward multiples are governed by defined product and protocol rules. These parameters form the underlying framework of the economic model. They are not simply changed arbitrarily on a daily basis.

2. Network Incentive Layer — AICS. The second layer is AICS, which focuses on network health. SpartanOS is not designed to determine long-term network rewards solely based on how many people someone recruits or how much volume a network generates. Instead, AICS continuously evaluates the quality and health of network participation. The current AICS scoring model is: Score = 0.2H + 0.4C + 0.2A + 0.2R, with a 30-day rolling evaluation period. The assessment considers factors such as holder participation, effective accounts, the proportion of long-term participation, retention, activity, and contribution to the overall ecosystem and liquidity. Therefore, even two networks at the same level do not necessarily receive identical effective incentives over time. If a network increases long-term participation, retention, active addresses and constructive ecosystem contribution, its health assessment can improve. Conversely, if selling increases significantly, retention decreases, long-term participation declines, or positive contribution to liquidity weakens, its AICS assessment can also adjust accordingly. In other words: network rewards are not determined only by network size; they are increasingly linked to network quality and health.

3. Market Balancing Layer — O2 Adaptive Balancing Protocol. AICS, however, cannot solve secondary-market supply-and-demand imbalances by itself. That is the role of O2. O2 operates around a three-hour observation and reassessment cycle. It does not simply react to whether the RM price goes up or down. Instead, it evaluates multiple market indicators, including buy volume, sell volume, TWAP, average execution price, buy/sell ratio, liquidity depth, and overall supply-and-demand conditions. The underlying principle is simple: price is the result; supply and demand are the cause. When RM supply and demand become significantly imbalanced, O2 can increase sell-side protection. When market conditions return toward the protocol-defined healthy range, O2 continues reassessing conditions on its three-hour cycle and can gradually step protections back toward their normal level rather than removing them abruptly. Under the current design, returning to the normal baseline requires the relevant conditions to remain satisfied continuously. Economically, this functions as an adaptive safety valve at the execution layer.

4. Creating Demand Alongside Supply — The 1:1 Turbo Engine. SpartanOS also contains another important supply-demand mechanism: the 1:1 Turbo Engine. Under the relevant reward mechanism, participation can generate a corresponding 1:1 compulsory RM purchase requirement, together with a holding/silent-period mechanism. The purpose is important: the system is not designed only to create token emissions. It also attempts to create corresponding market demand for RM while rewards and token supply are being generated and released.

So when we look at SpartanOS as a complete system, there are effectively three layers of control: Protocol Rules define how assets enter, lock, mint and release; AICS adjusts incentives according to network health; O2 adjusts market protection according to market health. These mechanisms then interact with the Turbo Engine, buybacks, burns, long-term locking, bonds and POL, affecting both the supply side and demand side of RM.

What "Dynamic" Really Means

Therefore, when we say that SpartanOS has dynamic elements in both its active and passive incentive structures, a more technically accurate explanation is: the underlying product rules provide the framework, while effective network incentives and market-protection parameters are not necessarily permanent fixed values. They can adapt according to network health and market health. This is an important structural distinction between SpartanOS and models that rely primarily on fixed APYs, fixed referral incentives, or fixed allocation of incoming capital.

The key concept is not simply that parameters can "float." The more important concept is that SpartanOS attempts to establish feedback loops: network behavior changes → AICS reassesses network health; market supply and demand change → O2 reassesses market health.

In one sentence: AICS manages network health; O2 manages market health. AICS evaluates whether internal network growth and participation remain healthy, while O2 evaluates whether external RM supply, demand and liquidity remain balanced. One addresses the quality of incentives; the other addresses the balance of the market. The protocol rules define the framework, AICS adapts incentives, and O2 adapts market protection.

Importantly, these mechanisms are designed to improve long-term sustainability and resilience, rather than guarantee permanent price or yield stability. Whether they achieve that objective over time should ultimately be evaluated through actual on-chain data, including net RM issuance, buyback and burn volumes, POL/liquidity depth, retention behavior, and performance under market stress.

Mechanisms and Consensus

We have to recognize a fundamental reality of decentralized protocols: a protocol can manage mechanisms, but it cannot control human behavior. Even with O2 Adaptive Balancing, sudden large-scale selling pressure and market shocks cannot be completely avoided. O2 manages supply-demand balance, while AICS manages network health. These mechanisms can reduce risk, but they cannot eliminate participants' freedom of choice.

That is why we place great importance on consensus education, community guidelines, and long-term community culture, not to restrict anyone's freedom to trade, but to help participants understand how individual behavior can affect the broader ecosystem. Mechanisms maintain balance; consensus builds long-term value. Together, they create a healthier and more resilient ecosystem.
The project's answers to seven due-diligence questions of 24 September and four follow-up questions of 26 September are reproduced whole in the Due diligence section. The twenty-one published contract addresses, checked on the explorer, are in Terms today.
Every official announcement since the mainnet, newest first, in plain words, with the link to the original post where one exists. Read the last three before any call; the person you are talking to may have read them already.
The first tokenised stock assets launched on the chain's RWA sector (SPCXon, NVDAon, AAPLon among them), with 24-hour trading and fractional shares, as announced. Not a Spartan OS product; the Trading Center is unchanged.
SourceAs of 4 November 2026, as stated by Anubis Chain: DeFi TVL about 330 million dollars, more than 205 million transactions, more than 24.42 million addresses. The explorer stood at 218.8 million transactions and 26.3 million addresses on 9 November.
SourceStargate, the LayerZero bridge, has integrated Anubis Chain, which can now reach the LayerZero network of chains; 44 asset routes across 33 assets were listed on 9 November. The Phalanx note of 7 November: technical connectivity is the first stage, cross-chain inside the Spartan OS dApp the second; its date and assets are to be confirmed by official announcement.
SourceArabic, Russian, French, Spanish and German added to spartanar.org, as announced.
SourceCommunities ranked on new, verified deposits into 360-day and 540-day liquidity bonds (days counted in UTC+8): an iPhone 18 Pro Max for the daily champion, 100 g of gold for the weekly, a car for the month, as announced. The bonds carry their lock-up and their risk; a prize is not a return.
SourceA Dubai event on 7 to 10 December 2026 (dates tentative) for leaders at V1 or above, up to five core leaders per V1+ team, with at least 10,000 USDT in long-term staking, subject to approval; round-trip flight and four days, three nights, as announced to the international teams.
Source36 million in the RM/USDT liquidity pool and 4 million in the ecosystem reserve, 45 countries, next target 41 million, as stated; development figures, not guarantees.
SourceOne iPhone 18 Pro Max added to a conference's draw for every 100,000 USDT of verified new liquidity-bond participation at that conference; a single 360-day or 540-day LP bond of 3,000 USDT or more qualifies a person; the staking products do not count, nor do hedging deposits or internal transfers. Participation does not guarantee a prize; the bonds carry their lock-up and their risk.
Source35 million in the RM/USDT liquidity pool and 4 million in the ecosystem reserve, 45 countries, next milestone 40 million, as stated; development figures, not guarantees.
SourceRewards stop when the 540-day term completes, cap reached or not; a cap reached early freezes the unreleased capital until a new, larger 540-day order is opened; a new order is needed to continue. The FAQ is reproduced in the Official section.
Posted in the Resource LibraryAn agency for exchange listings, with a network of partner exchanges, joins Anubis Chain as a strategic partner, as announced.
SourceThe official bridge appears on DeFiLlama, where its locked value can be read by anyone.
SourceA gold-badged primary account for announcements, technical developments, partnerships and global updates; @AnubisChainL1 becomes the ecosystem account. Both are official.
SourceMalicious code repackaged into iOS apps can read keys, seed phrases and chat records; update to iOS 26.7, avoid unknown apps.
SourceAnubis Chain has never published a social app on any store; do not install one or connect a wallet to it.
SourceThe primary channel for ecosystem, partnership, product and official announcements from this date.
SourceSubgraph indexing live; developers can query on-chain data through The Graph.
SourceOn-chain infrastructure, ecosystem resources and application-level collaboration confirmed for Spartan OS.
SourceFrom $32.84 to $25.12 and back above $30; RM/USDT liquidity about 29.03 million USDT, reserve 4 million, capital base stated at 33 million+.
Posted in the Resource LibraryDay 155: 102,934,209 transactions, 18,185,105 addresses, 16,533 contracts, block time 1.0 second, gas below $0.01.
SourceAC Wallet users brought into AnubisChain through a daily incentive campaign.
SourceSixty-second rounds on AnubisChain, outcomes by provable randomness, RM and GD accepted.
SourceEcosystem reserve 4,000,000 USDT; RM stated at $25.122 rising to $29.9639.
Posted in the Resource LibraryApplication fees by meeting size, hosting rules and the 150% performance condition for reimbursement.
Posted in the Resource LibraryGoPlay, described as the first Play-to-Co-Create platform, to launch TempleRaid on AnubisChain with RM, DAI and USDT supported first.
Source74.73 million transactions, 15.61 million addresses, 1.079 million transactions in 24 hours, 13,000+ contracts, 250,149 DAI transfers.
SourceOmnichain asset flow, ZK privacy infrastructure, fast low-cost transactions, DeFi, Awake NFT identity, on-chain governance, long-term incentives, AI and RWA.
SourceThirty days of tasks through AC Wallet, 12 August to 11 September.
Source14.10 million addresses, 10.64 million blocks, 938,000 transactions in 24 hours, 10,792 contracts; gas below $0.01.
SourceAn AI question-and-answer page for mainnet, wallet, security, privacy, swap and bridge questions.
SourceSingle participations over 200 USDT in 360 or 540-day staking or bonds, or the RM Stable Vault, qualify for irregular airdrops from the pool; rules by official announcement.
Posted in the Resource LibraryGovernance multisig, treasury, staking, reward distribution and core token contracts: zero critical, zero major, three medium findings resolved.
Source360-day staking or bond from 500 USDT: an extra 1.5% DOS airdrop; 540-day: 3%. The campaign closed on 31 August.
Posted in the Resource LibraryOmnichain infrastructure and the OFT standard to be used for mainnet deployment and ecosystem integration; details to follow.
SourceAC Wallet becomes a gateway to AnubisChain assets; DEXTools data cited the same day placing AnubisChain 12th by trading volume and 10th by liquidity among chains.
SourceAs of 20 July: 12.13 million addresses, 38.49 million transactions, 9.05 million blocks, TVL $189.91 million, 2,650+ token types, 119 verified contracts, average block time about one second.
Posted in the Resource Library137 core smart contracts verified; asset reserves, issuance and transfers traceable.
SourceRound 3 of the Genesis Foundation Program allocates the fund; address published; used only to steady the RM market in abnormal volatility, under DAO oversight.
Posted in the Resource LibraryUp to three zero-gas transfers a day inside AnubisChain through Bitget Wallet, 0.1 gasDAI maximum each; cross-chain transactions excluded.
SourceTotal value of official anchored assets as stated on the day, with both bridge contracts and the DAI mapped-asset contract published.
SourceCoinMarketCap, CoinGecko, DEXTools, Bitget Wallet, MyToken, Ave.ai, dappOS, RocketSwap, AuraOS, Ads3, Spartan OS and VEST listed as ecosystem partners.
SourceEcosystem projects can submit token information for the AnubisChain section.
SourceThe first Anubis Labs application opens. RM opens at $18.85, as later stated by Spartan OS.
SourceAVE.ai adds cross-chain access and swap for AnubisChain assets.
SourceThe first genesis-level ecosystem project opens the DAI/LGNS pair on RocketSwap with an initial pool the project states at about $163 million.
Posted in the Resource LibraryChain ID 6714, fees in gasDAI, PoSA consensus. Every later milestone counts from this day.
SourceAnnouncements are summarised, not quoted. Figures are as stated on the day; targets and price ambitions in the original posts are left out on purpose. Source links open the original post on X.
A member put seven due-diligence questions to the project on 24 September 2026: what GD is for, what creates demand for it, what stops RM becoming sell pressure, what cash flows reach holders, where the moat is, what is verified on-chain, and how an AI agent's work is proved. Four follow-up questions were answered on 26 September: the same-rank bonus, the V12 stake, the energy multiple and whether the capital sits inside the cap. The answers came back whole and are reproduced here as supplied, with the numbering kept. Open a question for the full text; the short version is a card in the Knowledge section and the assistant reads both.
The same-rank reward is 10%–15%, calculated based on the earnings of the nearest same-rank position under your structure.
For example, if you are V5 and there are two V5 accounts below you—one in the first generation and another in the second generation—the same-rank reward is calculated from the nearest V5, which is the first-generation V5. You receive 10%–15% of that V5's applicable earnings.
You do not repeatedly receive the same-rank reward from every V5 below that position.
The override reward follows the same nearest-position principle.
Therefore, if you are V8 and there is a V8 under your team, you receive 10%–15% of the applicable earnings of the nearest qualifying V8 position.
1. What's the same-rank % reward? I am V8 and my team is V8?

The same-rank reward is 10%–15%, calculated based on the earnings of the nearest same-rank position under your structure.

For example, if you are V5 and there are two V5 accounts below you—one in the first generation and another in the second generation—the same-rank reward is calculated from the nearest V5, which is the first-generation V5. You receive 10%–15% of that V5's applicable earnings.

You do not repeatedly receive the same-rank reward from every V5 below that position.

The override reward follows the same nearest-position principle.

Therefore, if you are V8 and there is a V8 under your team, you receive 10%–15% of the applicable earnings of the nearest qualifying V8 position.
According to the current Leader Edition rank table, V12 requires 50,000 USDT.
To be precise, the 50,000 USDT refers to the personal Stake requirement for V12, rather than a separate "governance weight" parameter.
So the current standard is:
V12 Personal Stake = 50,000 USDT.
The 25,000 figure should not be used as the current V12 personal Stake requirement.
2. What is the governance weight for V12 — 25,000 or 50,000?

According to the current Leader Edition rank table, V12 requires 50,000 USDT.

To be precise, the 50,000 USDT refers to the personal Stake requirement for V12, rather than a separate "governance weight" parameter.

So the current standard is:

V12 Personal Stake = 50,000 USDT.

The 25,000 figure should not be used as the current V12 personal Stake requirement.
The current DApp display should be used as the final reference.
There are two different Energy mechanisms currently shown in the DApp:
Energy Staking = 260%
RM Burning for Energy = 557%
These are two separate mechanisms and should not be mixed together.
Most importantly, 260% and 557% are dynamic protocol parameters, not permanently fixed rates. The protocol can adjust these values, so the figures may change over time.
The 150%/200% figures in previous Economic Model Analysis materials, as well as previous explanations of a 2–6× burn range, should not override the current live DApp parameters.
Therefore, promoters should always use the latest values displayed in the DApp.
Currently: Staking = 260%, Burning = 557%. These values are dynamic and subject to protocol adjustment. The DApp is always the final reference.
3. The Energy multiple: the DApp shows 260% and 557%, the Economic Model Analysis says 150% and 200%, and tonight's answers say 2–6× on burn. Which one is correct?

The current DApp display should be used as the final reference.

There are two different Energy mechanisms currently shown in the DApp:

Energy Staking = 260%

RM Burning for Energy = 557%

These are two separate mechanisms and should not be mixed together.

Most importantly, 260% and 557% are dynamic protocol parameters, not permanently fixed rates. The protocol can adjust these values, so the figures may change over time.

The 150%/200% figures in previous Economic Model Analysis materials, as well as previous explanations of a 2–6× burn range, should not override the current live DApp parameters.

Therefore, promoters should always use the latest values displayed in the DApp.

Currently: Staking = 260%, Burning = 557%. These values are dynamic and subject to protocol adjustment. The DApp is always the final reference.
The initial capital is included within the 4×/5× total release cap.
The mechanism releases principal + earnings together over time. The principal is not separately returned on top after the 4×/5× has been completed.
For example, if a position has a 5× total cap, both the principal and earnings released by the protocol are calculated within that 5× total.
So the correct explanation is:
Principal + earnings are released together, and both are included within the 4×/5× total release cap. The principal is not an additional payment on top of the 4×/5×.
4. Does the initial capital from staking or bonds count inside the 4×/5×, or is the 4×/5× reward with the capital on top?

The initial capital is included within the 4×/5× total release cap.

The mechanism releases principal + earnings together over time. The principal is not separately returned on top after the 4×/5× has been completed.

For example, if a position has a 5× total cap, both the principal and earnings released by the protocol are calculated within that 5× total.

So the correct explanation is:

Principal + earnings are released together, and both are included within the 4×/5× total release cap. The principal is not an additional payment on top of the 4×/5×.
Spartan OS · Answers to four follow-up questions · received 26 September 2026

1. What's the same-rank % reward? I am V8 and my team is V8?

The same-rank reward is 10%–15%, calculated based on the earnings of the nearest same-rank position under your structure.

For example, if you are V5 and there are two V5 accounts below you—one in the first generation and another in the second generation—the same-rank reward is calculated from the nearest V5, which is the first-generation V5. You receive 10%–15% of that V5's applicable earnings.

You do not repeatedly receive the same-rank reward from every V5 below that position.

The override reward follows the same nearest-position principle.

Therefore, if you are V8 and there is a V8 under your team, you receive 10%–15% of the applicable earnings of the nearest qualifying V8 position.

2. What is the governance weight for V12 — 25,000 or 50,000?

According to the current Leader Edition rank table, V12 requires 50,000 USDT.

To be precise, the 50,000 USDT refers to the personal Stake requirement for V12, rather than a separate "governance weight" parameter.

So the current standard is:

V12 Personal Stake = 50,000 USDT.

The 25,000 figure should not be used as the current V12 personal Stake requirement.

3. The Energy multiple: the DApp shows 260% and 557%, the Economic Model Analysis says 150% and 200%, and tonight's answers say 2–6× on burn. Which one is correct?

The current DApp display should be used as the final reference.

There are two different Energy mechanisms currently shown in the DApp:

Energy Staking = 260%

RM Burning for Energy = 557%

These are two separate mechanisms and should not be mixed together.

Most importantly, 260% and 557% are dynamic protocol parameters, not permanently fixed rates. The protocol can adjust these values, so the figures may change over time.

The 150%/200% figures in previous Economic Model Analysis materials, as well as previous explanations of a 2–6× burn range, should not override the current live DApp parameters.

Therefore, promoters should always use the latest values displayed in the DApp.

Currently: Staking = 260%, Burning = 557%. These values are dynamic and subject to protocol adjustment. The DApp is always the final reference.

4. Does the initial capital from staking or bonds count inside the 4×/5×, or is the 4×/5× reward with the capital on top?

The initial capital is included within the 4×/5× total release cap.

The mechanism releases principal + earnings together over time. The principal is not separately returned on top after the 4×/5× has been completed.

For example, if a position has a 5× total cap, both the principal and earnings released by the protocol are calculated within that 5× total.

So the correct explanation is:

Principal + earnings are released together, and both are included within the 4×/5× total release cap. The principal is not an additional payment on top of the 4×/5×.
GD serves as the scarce governance and long-term ecosystem-rights layer of SpartanOS. It is deliberately separated from both stablecoins and RM because these assets perform fundamentally different economic functions.
Stablecoins primarily provide pricing, capital entry, and settlement. RM is the higher-frequency economic asset used across incentives, staking, bonds, liquidity, compounding, burns, and application participation. GD, by contrast, is designed to represent scarce governance rights and longer-term ecosystem participation.
GD has a fixed maximum supply of 390,000 tokens. Its maximum supply does not expand simply because SpartanOS gains more users, TVL, or applications.
Access to GD is also constrained by the original tokenomics. Relevant channels include rights allocated to early NFT holders, predefined governance and ecosystem allocations, GD governance rights associated with the RM Stable Vault, and secondary-market circulation.
An important distinction concerns the GD associated with the RM Stable Vault. Those GD rights are released linearly over 30 weeks, but they are not newly minted because the Stable Vault exists. They come from GD that was already allocated under the original tokenomics, including the original 25% liquidity-incentive allocation. The original allocation structure also includes a 5% protocol-treasury risk reserve. Therefore, the Stable Vault does not change GD's 390,000 maximum-supply logic.
The reason SpartanOS does not use RM for everything is that RM itself is designed to circulate through a much higher-frequency economic cycle: incentives → staking → bonds → liquidity → applications → release → market demand → burn. Combining that role with the ecosystem's scarcest long-term governance rights would place two different economic objectives into the same asset.
Stablecoins cannot fully perform this role either. Their primary economic purpose is stable denomination and settlement, rather than representing a scarce governance asset whose supply remains fixed while the ecosystem around it expands.
This separation of economic roles is not unusual in crypto. Major protocols have similarly separated settlement or productive assets from governance and ecosystem-rights assets. The comparison does not mean GD is equivalent to those tokens; it illustrates a broader crypto-economic principle: high-frequency economic circulation and scarce governance rights do not necessarily need to be represented by the same asset.
A conventional governance token could theoretically be designed with similar characteristics. Therefore, GD's differentiation is not simply that it is called a governance token. Its long-term differentiation must come from whether SpartanOS can continuously attach meaningful governance rights, application utility, and ecosystem participation to a fixed supply of 390,000 GD. The ecosystem can expand. Applications can expand. The user base can expand. GD's maximum supply does not need to expand with them. That is the core economic purpose of GD.
1. What specific economic purpose does GD serve that could not be achieved with a conventional governance token or stablecoin?

GD serves as the scarce governance and long-term ecosystem-rights layer of SpartanOS. It is deliberately separated from both stablecoins and RM because these assets perform fundamentally different economic functions.

Stablecoins primarily provide pricing, capital entry, and settlement. RM is the higher-frequency economic asset used across incentives, staking, bonds, liquidity, compounding, burns, and application participation. GD, by contrast, is designed to represent scarce governance rights and longer-term ecosystem participation.

GD has a fixed maximum supply of 390,000 tokens. Its maximum supply does not expand simply because SpartanOS gains more users, TVL, or applications.

Access to GD is also constrained by the original tokenomics. Relevant channels include rights allocated to early NFT holders, predefined governance and ecosystem allocations, GD governance rights associated with the RM Stable Vault, and secondary-market circulation.

An important distinction concerns the GD associated with the RM Stable Vault. Those GD rights are released linearly over 30 weeks, but they are not newly minted because the Stable Vault exists. They come from GD that was already allocated under the original tokenomics, including the original 25% liquidity-incentive allocation. The original allocation structure also includes a 5% protocol-treasury risk reserve. Therefore, the Stable Vault does not change GD's 390,000 maximum-supply logic.

The reason SpartanOS does not use RM for everything is that RM itself is designed to circulate through a much higher-frequency economic cycle: incentives → staking → bonds → liquidity → applications → release → market demand → burn. Combining that role with the ecosystem's scarcest long-term governance rights would place two different economic objectives into the same asset.

Stablecoins cannot fully perform this role either. Their primary economic purpose is stable denomination and settlement, rather than representing a scarce governance asset whose supply remains fixed while the ecosystem around it expands.

This separation of economic roles is not unusual in crypto. Major protocols have similarly separated settlement or productive assets from governance and ecosystem-rights assets. The comparison does not mean GD is equivalent to those tokens; it illustrates a broader crypto-economic principle: high-frequency economic circulation and scarce governance rights do not necessarily need to be represented by the same asset.

A conventional governance token could theoretically be designed with similar characteristics. Therefore, GD's differentiation is not simply that it is called a governance token. Its long-term differentiation must come from whether SpartanOS can continuously attach meaningful governance rights, application utility, and ecosystem participation to a fixed supply of 390,000 GD. The ecosystem can expand. Applications can expand. The user base can expand. GD's maximum supply does not need to expand with them. That is the core economic purpose of GD.
Structural demand for GD cannot come from scarcity alone. Scarcity does not automatically create demand. Utility does.
The intended long-term demand structure for GD is: fixed supply + limited acquisition + governance demand + application utility + ecosystem expansion.
GD is beginning to move beyond being purely a governance asset and into actual application utility. For example, applications such as TempleRaid are bringing GD, RM, and other AnubisChain ecosystem assets into application-level use. This represents an important transition from simply holding a governance asset toward using that asset across both governance and applications.
As additional games, DeFi applications, RWA products, DID/NFT systems, trading infrastructure, and other DApps enter the ecosystem, GD can progressively support additional governance participation, application rights, ecosystem permissions, or other utility.
The economic relationship we want to establish is therefore straightforward: the number of applications can increase; the number of users can increase; the amount of utility attached to GD can increase; but the maximum GD supply remains 390,000. This is the important distinction between speculative demand and structural demand.
ETH provides a useful mainstream reference point for the principle, although its economic model is different. ETH demand is not based solely on people choosing to hold ETH; ETH is required for gas, participates in staking, and is used throughout the Ethereum ecosystem. GD must ultimately prove itself through the same broader economic principle: real utility must support long-term demand.
For that reason, GD should not be evaluated only by its market price. More meaningful metrics include the number of active GD addresses, ownership distribution, governance participation, number of applications using GD, application interactions, and actual on-chain usage. If the ecosystem expands while GD usage does not, then structural demand has not been proven. If more applications and users genuinely require GD while maximum supply remains fixed at 390,000, then GD is developing utility-driven structural demand.
2. What creates structural demand for GD through actual SpartanOS usage?

Structural demand for GD cannot come from scarcity alone. Scarcity does not automatically create demand. Utility does.

The intended long-term demand structure for GD is: fixed supply + limited acquisition + governance demand + application utility + ecosystem expansion.

GD is beginning to move beyond being purely a governance asset and into actual application utility. For example, applications such as TempleRaid are bringing GD, RM, and other AnubisChain ecosystem assets into application-level use. This represents an important transition from simply holding a governance asset toward using that asset across both governance and applications.

As additional games, DeFi applications, RWA products, DID/NFT systems, trading infrastructure, and other DApps enter the ecosystem, GD can progressively support additional governance participation, application rights, ecosystem permissions, or other utility.

The economic relationship we want to establish is therefore straightforward: the number of applications can increase; the number of users can increase; the amount of utility attached to GD can increase; but the maximum GD supply remains 390,000. This is the important distinction between speculative demand and structural demand.

ETH provides a useful mainstream reference point for the principle, although its economic model is different. ETH demand is not based solely on people choosing to hold ETH; ETH is required for gas, participates in staking, and is used throughout the Ethereum ecosystem. GD must ultimately prove itself through the same broader economic principle: real utility must support long-term demand.

For that reason, GD should not be evaluated only by its market price. More meaningful metrics include the number of active GD addresses, ownership distribution, governance participation, number of applications using GD, application interactions, and actual on-chain usage. If the ecosystem expands while GD usage does not, then structural demand has not been proven. If more applications and users genuinely require GD while maximum supply remains fixed at 390,000, then GD is developing utility-driven structural demand.
RM is not designed around emission control alone. SpartanOS attempts to manage both sides of the equation: how RM enters circulation and what creates demand for RM once it does. If a token's long-term economic path is simply mint → reward → sell, then increasing emission can eventually translate into persistent sell pressure. SpartanOS therefore combines controlled release, long-term locking, market-buy demand, burns, dynamic incentives, application demand, and liquidity balancing.
First, RM being generated does not mean that all RM immediately enters the open market. Long-term staking, 360/540-day long-term liquidity bonds, compounding, and the Energy system affect when and how much RM becomes actual circulating supply. The Energy system also creates an RM consumption path. RM can be burned to obtain 2–6× Energy value, while Energy staking itself follows a 360-day structure. RM therefore has a consumption mechanism in addition to its reward and trading functions.
Second, the 1:1 Turbo Engine introduces corresponding market-buy demand. Under the relevant reward mechanism, the system does not operate only on the reward side. Corresponding rewards require a 1:1 market purchase of RM, creating a demand side against token release. This is an important distinction. The objective is not to prohibit users from selling RM. The economic question is whether RM entering circulation is accompanied by sufficient real market demand. RM purchased through Turbo also enters a 24-hour silent period, while the baseline sell-side tax is 5%, reducing the possibility that the same purchase immediately becomes an equivalent short-term sell order.
Third, SpartanOS uses the O2 Adaptive Balancing Protocol. O2 operates on a three-hour cycle and incorporates TWAP while observing variables including buy/sell volume, average transaction size, buy/sell ratios, liquidity depth, and broader market conditions. When significant short-term supply-demand imbalance appears, sell-side protection can increase. When conditions normalize, the system re-evaluates conditions every three hours and progressively adjusts protection back toward the baseline 5%. The fastest return to baseline conditions within 24 hours still requires the relevant recovery conditions to remain satisfied continuously. O2 therefore addresses liquidity and supply-demand imbalance. It is not a mechanism that dictates what RM's market price should be, nor should it be interpreted as a price guarantee. The underlying principle is simple: price is the result; supply and demand are the cause. When imbalance occurs, protection increases. When balance returns, protection normalizes.
Fourth, SpartanOS uses AICS as a dynamic incentive layer. AICS operates on a rolling 30-day evaluation: Score = 0.2H + 0.4C + 0.2A + 0.2R. It evaluates network-health factors including referral structure, holder addresses, long-term participation, retention, activity, and contribution to the ecosystem. As a result, reaching the same nominal level does not necessarily mean receiving exactly the same incentives. Persistent heavy selling, weak retention, or declining long-term contribution can affect AICS evaluation. In simple terms: AICS evaluates network health; O2 manages market balance.
Long-term staking, 360/540-day bonds, compounding, locking, burns, and growing application demand then add further supply and demand components. The broader DeFi market has already demonstrated why this matters. High-emission liquidity-mining models without sufficient utility, locking, or real demand can eventually convert incentives into sell pressure. Other major crypto systems have responded to similar economic problems through combinations of locking, fee burns, buybacks, or utility demand.
SpartanOS combines: controlled release + 1:1 Turbo demand + long-term locking + burn + AICS + O2 adaptive balancing + application demand. The key long-term metrics are therefore not simply how much RM is generated. They are: new RM supply, actual circulating supply, 1:1 Turbo buy demand, application demand, long-term locked RM, burned RM, and liquidity depth. These mechanisms are designed to improve the supply-demand structure. They do not constitute a guarantee of RM's market price. Ultimately, sustainable demand must grow sufficiently to absorb sustainable supply.
3. RM is designed to incentivize users, developers, and community participation. What prevents RM from becoming a pure emission-and-sell-pressure token over time?

RM is not designed around emission control alone. SpartanOS attempts to manage both sides of the equation: how RM enters circulation and what creates demand for RM once it does. If a token's long-term economic path is simply mint → reward → sell, then increasing emission can eventually translate into persistent sell pressure. SpartanOS therefore combines controlled release, long-term locking, market-buy demand, burns, dynamic incentives, application demand, and liquidity balancing.

First, RM being generated does not mean that all RM immediately enters the open market. Long-term staking, 360/540-day long-term liquidity bonds, compounding, and the Energy system affect when and how much RM becomes actual circulating supply. The Energy system also creates an RM consumption path. RM can be burned to obtain 2–6× Energy value, while Energy staking itself follows a 360-day structure. RM therefore has a consumption mechanism in addition to its reward and trading functions.

Second, the 1:1 Turbo Engine introduces corresponding market-buy demand. Under the relevant reward mechanism, the system does not operate only on the reward side. Corresponding rewards require a 1:1 market purchase of RM, creating a demand side against token release. This is an important distinction. The objective is not to prohibit users from selling RM. The economic question is whether RM entering circulation is accompanied by sufficient real market demand. RM purchased through Turbo also enters a 24-hour silent period, while the baseline sell-side tax is 5%, reducing the possibility that the same purchase immediately becomes an equivalent short-term sell order.

Third, SpartanOS uses the O2 Adaptive Balancing Protocol. O2 operates on a three-hour cycle and incorporates TWAP while observing variables including buy/sell volume, average transaction size, buy/sell ratios, liquidity depth, and broader market conditions. When significant short-term supply-demand imbalance appears, sell-side protection can increase. When conditions normalize, the system re-evaluates conditions every three hours and progressively adjusts protection back toward the baseline 5%. The fastest return to baseline conditions within 24 hours still requires the relevant recovery conditions to remain satisfied continuously. O2 therefore addresses liquidity and supply-demand imbalance. It is not a mechanism that dictates what RM's market price should be, nor should it be interpreted as a price guarantee. The underlying principle is simple: price is the result; supply and demand are the cause. When imbalance occurs, protection increases. When balance returns, protection normalizes.

Fourth, SpartanOS uses AICS as a dynamic incentive layer. AICS operates on a rolling 30-day evaluation: Score = 0.2H + 0.4C + 0.2A + 0.2R. It evaluates network-health factors including referral structure, holder addresses, long-term participation, retention, activity, and contribution to the ecosystem. As a result, reaching the same nominal level does not necessarily mean receiving exactly the same incentives. Persistent heavy selling, weak retention, or declining long-term contribution can affect AICS evaluation. In simple terms: AICS evaluates network health; O2 manages market balance.

Long-term staking, 360/540-day bonds, compounding, locking, burns, and growing application demand then add further supply and demand components. The broader DeFi market has already demonstrated why this matters. High-emission liquidity-mining models without sufficient utility, locking, or real demand can eventually convert incentives into sell pressure. Other major crypto systems have responded to similar economic problems through combinations of locking, fee burns, buybacks, or utility demand.

SpartanOS combines: controlled release + 1:1 Turbo demand + long-term locking + burn + AICS + O2 adaptive balancing + application demand. The key long-term metrics are therefore not simply how much RM is generated. They are: new RM supply, actual circulating supply, 1:1 Turbo buy demand, application demand, long-term locked RM, burned RM, and liquidity depth. These mechanisms are designed to improve the supply-demand structure. They do not constitute a guarantee of RM's market price. Ultimately, sustainable demand must grow sufficiently to absorb sustainable supply.
SpartanOS separates three concepts that should not be confused: capital flow, protocol accrual, and token holder value accrual.
SpartanOS is not accurately described as a simple traditional fund-allocation model where, for example, a user deposits $100 and a fixed X% automatically becomes protocol revenue while Y% automatically becomes token-holder income. The more accurate approach is to analyze both the asset side and the RM supply side.
When capital enters SpartanOS, depending on the specific product and its economic rules, that capital contributes to the protocol asset structure, including functions such as liquidity, treasury, POL, and other protocol assets. Different products can have different asset paths. A specific product can therefore be analyzed in terms of how much capital contributes to LP, treasury/POL, or other protocol functions. However, a product-specific asset allocation should not be presented as a universal revenue-distribution percentage for the entire SpartanOS ecosystem.
At the same time, the protocol determines the corresponding RM minting, locking, and future release obligations according to the rules of that product. This means that when $100 enters the protocol, the relevant economic question is not only "Where was the $100 allocated?" It is also "What protocol asset value was created by that $100, and what corresponding future RM supply or token liability was created against it?" That RM does not necessarily enter the open market immediately. Its economic path can involve: locking → controlled release → 1:1 Turbo demand → buyback → burn → O2 adaptive balancing.
Therefore, what matters economically is not simply "How much of the $100 was distributed?" A more meaningful question is: "What protocol asset value was created by that $100, what future RM supply was created against it, how and when does that RM enter circulation, and how does the market absorb that supply?"
A simplified representation is: capital enters the protocol → protocol assets / treasury / POL / liquidity → RM minting according to protocol rules → RM locking and controlled release → secondary-market supply and demand → O2 monitors market conditions → buyback / burn / protection / liquidity mechanisms respond → the system moves toward a new supply-demand equilibrium. In simple terms: SpartanOS does not simply divide deposits; it manages a token economy.
The second part of the question, what ultimately accrues to token holders, is equally important. Assets accumulated in treasury/POL represent protocol accrual. Liquidity contributes to protocol economics and market depth. Neither should automatically be described as cash income paid directly to token holders. Therefore: treasury ≠ holder dividend; liquidity ≠ holder dividend; token price appreciation ≠ cash-flow distribution.
At present, RM and GD holder value capture should primarily be understood as indirect value accrual rather than a traditional fixed dividend model. For RM, value accrual can occur through 1:1 Turbo market-buy demand, locking, changes in circulating supply, burns, application utility, and application-revenue-linked buyback/burn mechanisms where applicable. For GD, value accrual is associated with its fixed 390,000 maximum supply, governance rights, and expanding application utility.
The next major economic layer is external application revenue. As GoPlay, TempleRaid, and future games, DEXs, cross-chain applications, RWA products, trading infrastructure, and other DApps generate genuine external economic activity, it becomes possible to track how much application revenue enters treasury, how much strengthens liquidity, how much is used for RM buyback/burn, and whether any portion is explicitly distributed to holders. Unless a smart contract or explicit protocol rule states that X% of protocol revenue is directly distributed to RM/GD holders, protocol assets should not be represented as direct holder cash flow.
Therefore, there is currently no accurate universal formula such as "$100 deposited = X% goes directly to RM/GD holders." A more meaningful due-diligence framework is: for every unit of capital entering SpartanOS, what protocol assets are created or acquired, what corresponding RM supply or future token liability is generated, how is that RM released into circulation, and what mechanisms balance that supply against real market demand and liquidity? And then: how much external application revenue is ultimately captured by treasury, liquidity, buyback/burn, or direct holder distribution?
These distinctions are essential: capital flow ≠ revenue; protocol assets ≠ holder dividend; buyback/burn ≠ direct cash distribution.
4. What actual cash flows move through the ecosystem, and what percentage ultimately accrues to the protocol or token holders?

SpartanOS separates three concepts that should not be confused: capital flow, protocol accrual, and token holder value accrual.

SpartanOS is not accurately described as a simple traditional fund-allocation model where, for example, a user deposits $100 and a fixed X% automatically becomes protocol revenue while Y% automatically becomes token-holder income. The more accurate approach is to analyze both the asset side and the RM supply side.

When capital enters SpartanOS, depending on the specific product and its economic rules, that capital contributes to the protocol asset structure, including functions such as liquidity, treasury, POL, and other protocol assets. Different products can have different asset paths. A specific product can therefore be analyzed in terms of how much capital contributes to LP, treasury/POL, or other protocol functions. However, a product-specific asset allocation should not be presented as a universal revenue-distribution percentage for the entire SpartanOS ecosystem.

At the same time, the protocol determines the corresponding RM minting, locking, and future release obligations according to the rules of that product. This means that when $100 enters the protocol, the relevant economic question is not only "Where was the $100 allocated?" It is also "What protocol asset value was created by that $100, and what corresponding future RM supply or token liability was created against it?" That RM does not necessarily enter the open market immediately. Its economic path can involve: locking → controlled release → 1:1 Turbo demand → buyback → burn → O2 adaptive balancing.

Therefore, what matters economically is not simply "How much of the $100 was distributed?" A more meaningful question is: "What protocol asset value was created by that $100, what future RM supply was created against it, how and when does that RM enter circulation, and how does the market absorb that supply?"

A simplified representation is: capital enters the protocol → protocol assets / treasury / POL / liquidity → RM minting according to protocol rules → RM locking and controlled release → secondary-market supply and demand → O2 monitors market conditions → buyback / burn / protection / liquidity mechanisms respond → the system moves toward a new supply-demand equilibrium. In simple terms: SpartanOS does not simply divide deposits; it manages a token economy.

The second part of the question, what ultimately accrues to token holders, is equally important. Assets accumulated in treasury/POL represent protocol accrual. Liquidity contributes to protocol economics and market depth. Neither should automatically be described as cash income paid directly to token holders. Therefore: treasury ≠ holder dividend; liquidity ≠ holder dividend; token price appreciation ≠ cash-flow distribution.

At present, RM and GD holder value capture should primarily be understood as indirect value accrual rather than a traditional fixed dividend model. For RM, value accrual can occur through 1:1 Turbo market-buy demand, locking, changes in circulating supply, burns, application utility, and application-revenue-linked buyback/burn mechanisms where applicable. For GD, value accrual is associated with its fixed 390,000 maximum supply, governance rights, and expanding application utility.

The next major economic layer is external application revenue. As GoPlay, TempleRaid, and future games, DEXs, cross-chain applications, RWA products, trading infrastructure, and other DApps generate genuine external economic activity, it becomes possible to track how much application revenue enters treasury, how much strengthens liquidity, how much is used for RM buyback/burn, and whether any portion is explicitly distributed to holders. Unless a smart contract or explicit protocol rule states that X% of protocol revenue is directly distributed to RM/GD holders, protocol assets should not be represented as direct holder cash flow.

Therefore, there is currently no accurate universal formula such as "$100 deposited = X% goes directly to RM/GD holders." A more meaningful due-diligence framework is: for every unit of capital entering SpartanOS, what protocol assets are created or acquired, what corresponding RM supply or future token liability is generated, how is that RM released into circulation, and what mechanisms balance that supply against real market demand and liquidity? And then: how much external application revenue is ultimately captured by treasury, liquidity, buyback/burn, or direct holder distribution?

These distinctions are essential: capital flow ≠ revenue; protocol assets ≠ holder dividend; buyback/burn ≠ direct cash distribution.
SpartanOS's moat is not RM alone, GD alone, O2 alone, or a single smart contract. Tokens can be copied. Smart contracts can be forked. Tokenomic parameters can also be replicated. The potential moat comes from the network effect created when multiple economic, application, infrastructure, liquidity, developer, and community layers operate together.
The first layer is the economic layer: RM + GD + O2 + 1:1 Turbo + AICS + Stable Vault + long-term staking + long-term liquidity bonds + Energy + burn + compounding. These mechanisms address different parts of the economic system: supply, demand, liquidity, long-term participation, and network health.
The second layer is the application layer. GoPlay, TempleRaid, and future applications are intended to move RM and GD beyond an internal protocol economy and into real application utility. As applications generate users, transactions, and external revenue, the application economy can begin feeding economic activity back into the RM/GD ecosystem.
The third layer is the AI / intent / execution layer. Intent infrastructure such as dappOS represents an important direction here. Its significance is not simply attaching an "AI" label to Web3. The objective is to reduce the complexity of blockchain interaction. A user expresses an intent; the relevant infrastructure can assist with routing, execution, and DApp interaction, while final asset ownership and settlement return to the blockchain layer. In simple terms: AI handles intelligence and execution assistance; blockchain provides trusted state, assets, and value settlement.
The fourth layer is blockchain infrastructure. SpartanOS uses AnubisChain for smart-contract execution and asset settlement, while the broader ecosystem connects with infrastructure across wallets, bridges, DEXs, explorers, indexing/data infrastructure, and cross-chain systems including areas such as The Graph, Blockscout, and LayerZero.
The fifth layer is ecosystem expansion. From Q3 onward, the ecosystem roadmap includes progressive development across: LayerZero + OFT cross-chain infrastructure, explorer upgrades, RocketSwap V3, Guard multisig, NFT + DID, AI Meme / AI Agent, RWA tokenization, a decentralized contract-trading platform, and contract-trading insurance. These should not all be represented as already-live revenue-generating products. Live products should be evaluated through product usage and on-chain data. Integrations under development should be evaluated through technical progress and official announcements. Future products should be verified through contracts, transactions, users, and revenue once deployed.
Major crypto networks demonstrate why this distinction matters. Ethereum's moat is not simply the EVM source code. Its network effect comes from developers, liquidity, wallets, applications, infrastructure, standards, and users interacting with one another. Likewise, an AMM formula itself can be forked; recreating the liquidity, integrations, users, developer tooling, and network effects around a mature DEX is significantly harder.
The network SpartanOS is attempting to build is therefore: token economy + liquidity + AI/intent + applications + blockchain infrastructure + developers + users + global community. It would be premature to describe this as an absolute, uncopyable moat. A more accurate description is that SpartanOS is building a network moat, whose strength must ultimately be demonstrated through liquidity depth, active users, application adoption, developer activity, external revenue, and cross-ecosystem integrations.
5. What is SpartanOS's crypto-native moat?

SpartanOS's moat is not RM alone, GD alone, O2 alone, or a single smart contract. Tokens can be copied. Smart contracts can be forked. Tokenomic parameters can also be replicated. The potential moat comes from the network effect created when multiple economic, application, infrastructure, liquidity, developer, and community layers operate together.

The first layer is the economic layer: RM + GD + O2 + 1:1 Turbo + AICS + Stable Vault + long-term staking + long-term liquidity bonds + Energy + burn + compounding. These mechanisms address different parts of the economic system: supply, demand, liquidity, long-term participation, and network health.

The second layer is the application layer. GoPlay, TempleRaid, and future applications are intended to move RM and GD beyond an internal protocol economy and into real application utility. As applications generate users, transactions, and external revenue, the application economy can begin feeding economic activity back into the RM/GD ecosystem.

The third layer is the AI / intent / execution layer. Intent infrastructure such as dappOS represents an important direction here. Its significance is not simply attaching an "AI" label to Web3. The objective is to reduce the complexity of blockchain interaction. A user expresses an intent; the relevant infrastructure can assist with routing, execution, and DApp interaction, while final asset ownership and settlement return to the blockchain layer. In simple terms: AI handles intelligence and execution assistance; blockchain provides trusted state, assets, and value settlement.

The fourth layer is blockchain infrastructure. SpartanOS uses AnubisChain for smart-contract execution and asset settlement, while the broader ecosystem connects with infrastructure across wallets, bridges, DEXs, explorers, indexing/data infrastructure, and cross-chain systems including areas such as The Graph, Blockscout, and LayerZero.

The fifth layer is ecosystem expansion. From Q3 onward, the ecosystem roadmap includes progressive development across: LayerZero + OFT cross-chain infrastructure, explorer upgrades, RocketSwap V3, Guard multisig, NFT + DID, AI Meme / AI Agent, RWA tokenization, a decentralized contract-trading platform, and contract-trading insurance. These should not all be represented as already-live revenue-generating products. Live products should be evaluated through product usage and on-chain data. Integrations under development should be evaluated through technical progress and official announcements. Future products should be verified through contracts, transactions, users, and revenue once deployed.

Major crypto networks demonstrate why this distinction matters. Ethereum's moat is not simply the EVM source code. Its network effect comes from developers, liquidity, wallets, applications, infrastructure, standards, and users interacting with one another. Likewise, an AMM formula itself can be forked; recreating the liquidity, integrations, users, developer tooling, and network effects around a mature DEX is significantly harder.

The network SpartanOS is attempting to build is therefore: token economy + liquidity + AI/intent + applications + blockchain infrastructure + developers + users + global community. It would be premature to describe this as an absolute, uncopyable moat. A more accurate description is that SpartanOS is building a network moat, whose strength must ultimately be demonstrated through liquidity depth, active users, application adoption, developer activity, external revenue, and cross-ecosystem integrations.
SpartanOS makes a clear distinction between on-chain state and off-chain computation.
Information that can be independently verified on-chain includes: wallet addresses, token contracts, RM/GD transfers, swaps, liquidity changes, burns, smart-contract interactions, transaction hashes, and final asset settlement. These facts do not require a user to trust what the SpartanOS frontend says. They can be independently checked against the relevant blockchain state through explorers and, where supported, third-party blockchain data/indexing infrastructure. That is one of the core properties of blockchain: users should be able to independently verify critical asset and transaction states rather than relying solely on the protocol's own interface.
However, not every component of the system is automatically on-chain. Elements such as portions of AICS scoring computation, intent interpretation, external-data analysis, API calls, agent decision-making, and other off-chain computation must be treated separately. If an off-chain system performs a calculation and then submits a transaction to the blockchain, the blockchain can prove that the final transaction occurred. It does not automatically prove that every preceding off-chain computation was correct. Therefore: result on-chain ≠ entire computation on-chain.
The trust boundary is more accurately described as: AI / off-chain infrastructure handles intelligence, analysis, and execution logic; blockchain verifies trusted state, assets, transactions, and final value settlement.
If off-chain computation itself needs to become cryptographically verifiable, additional technologies may be required, depending on the implementation, including public algorithms, oracles, TEEs, ZK proofs, cryptographic signatures, validator networks, or other verifiable-computation systems.
We therefore distinguish between on-chain facts, independently verifiable through blockchain state, and off-chain computation, requiring its own verification mechanism. A result being written to the blockchain should not be presented as proof that the entire off-chain computation was itself performed or verified on-chain.
6. What exactly is verified on-chain, and what is merely asserted by off-chain AI infrastructure?

SpartanOS makes a clear distinction between on-chain state and off-chain computation.

Information that can be independently verified on-chain includes: wallet addresses, token contracts, RM/GD transfers, swaps, liquidity changes, burns, smart-contract interactions, transaction hashes, and final asset settlement. These facts do not require a user to trust what the SpartanOS frontend says. They can be independently checked against the relevant blockchain state through explorers and, where supported, third-party blockchain data/indexing infrastructure. That is one of the core properties of blockchain: users should be able to independently verify critical asset and transaction states rather than relying solely on the protocol's own interface.

However, not every component of the system is automatically on-chain. Elements such as portions of AICS scoring computation, intent interpretation, external-data analysis, API calls, agent decision-making, and other off-chain computation must be treated separately. If an off-chain system performs a calculation and then submits a transaction to the blockchain, the blockchain can prove that the final transaction occurred. It does not automatically prove that every preceding off-chain computation was correct. Therefore: result on-chain ≠ entire computation on-chain.

The trust boundary is more accurately described as: AI / off-chain infrastructure handles intelligence, analysis, and execution logic; blockchain verifies trusted state, assets, transactions, and final value settlement.

If off-chain computation itself needs to become cryptographically verifiable, additional technologies may be required, depending on the implementation, including public algorithms, oracles, TEEs, ZK proofs, cryptographic signatures, validator networks, or other verifiable-computation systems.

We therefore distinguish between on-chain facts, independently verifiable through blockchain state, and off-chain computation, requiring its own verification mechanism. A result being written to the blockchain should not be presented as proof that the entire off-chain computation was itself performed or verified on-chain.
There are two separate levels of proof: execution result verification and computation verification.
If an agent claims that it completed a transfer, swap, stake, or smart-contract interaction, the user should not have to trust a frontend message saying "Completed." The primary proof should be the blockchain. A user should be able to verify the transaction hash, contract call, input assets, output assets, wallet-state changes, and final settlement.
For example, if an agent claims "I swapped Asset A into Asset B for you," the relevant proof is not the agent's own statement. The user should be able to verify whether the transaction actually exists, which smart contract was called, how much Asset A left the wallet, how much Asset B was received, and whether the transaction successfully settled. That is execution result verification. Blockchain is particularly effective at proving that an asset-related action actually occurred.
However, a transaction hash does not automatically prove why the agent made a particular decision, whether every input was accurate, or whether every internal reasoning step was correct. That is a separate problem: computation verification. If the objective is to cryptographically verify the agent's internal computation, additional mechanisms may be required, such as TEEs, ZK proofs, oracle systems, validator networks, cryptographic signatures, or other forms of verifiable computation.
We therefore do not make the technically inaccurate claim that "because the transaction is on-chain, every AI computation behind it is automatically trustworthy." The more accurate model is: AI understands intent, performs analysis, and assists execution; blockchain verifies asset state and final execution.
Intent infrastructure such as dappOS illustrates the broader direction: users do not necessarily need to manually understand every blockchain operation involved in fulfilling an intent. The intent/execution layer can simplify routing and execution, while critical asset outcomes should still return to blockchain-verifiable settlement.
The principle is straightforward: do not rely only on an agent saying "I completed the task." Verify whether the blockchain proves that the task was actually completed. If the requirement goes further, to prove why the agent made the decision or that its internal computation was correct, then that requires a separate cryptographic or verifiable-computation layer, and should be evaluated according to the actual verification technology deployed.
7. How does SpartanOS prove an AI agent actually performed the service it claims to have performed?

There are two separate levels of proof: execution result verification and computation verification.

If an agent claims that it completed a transfer, swap, stake, or smart-contract interaction, the user should not have to trust a frontend message saying "Completed." The primary proof should be the blockchain. A user should be able to verify the transaction hash, contract call, input assets, output assets, wallet-state changes, and final settlement.

For example, if an agent claims "I swapped Asset A into Asset B for you," the relevant proof is not the agent's own statement. The user should be able to verify whether the transaction actually exists, which smart contract was called, how much Asset A left the wallet, how much Asset B was received, and whether the transaction successfully settled. That is execution result verification. Blockchain is particularly effective at proving that an asset-related action actually occurred.

However, a transaction hash does not automatically prove why the agent made a particular decision, whether every input was accurate, or whether every internal reasoning step was correct. That is a separate problem: computation verification. If the objective is to cryptographically verify the agent's internal computation, additional mechanisms may be required, such as TEEs, ZK proofs, oracle systems, validator networks, cryptographic signatures, or other forms of verifiable computation.

We therefore do not make the technically inaccurate claim that "because the transaction is on-chain, every AI computation behind it is automatically trustworthy." The more accurate model is: AI understands intent, performs analysis, and assists execution; blockchain verifies asset state and final execution.

Intent infrastructure such as dappOS illustrates the broader direction: users do not necessarily need to manually understand every blockchain operation involved in fulfilling an intent. The intent/execution layer can simplify routing and execution, while critical asset outcomes should still return to blockchain-verifiable settlement.

The principle is straightforward: do not rely only on an agent saying "I completed the task." Verify whether the blockchain proves that the task was actually completed. If the requirement goes further, to prove why the agent made the decision or that its internal computation was correct, then that requires a separate cryptographic or verifiable-computation layer, and should be evaluated according to the actual verification technology deployed.
Spartan OS · Response to Seven Due Diligence Questions · received 24 September 2026

1. What specific economic purpose does GD serve that could not be achieved with a conventional governance token or stablecoin?

GD serves as the scarce governance and long-term ecosystem-rights layer of SpartanOS. It is deliberately separated from both stablecoins and RM because these assets perform fundamentally different economic functions.

Stablecoins primarily provide pricing, capital entry, and settlement. RM is the higher-frequency economic asset used across incentives, staking, bonds, liquidity, compounding, burns, and application participation. GD, by contrast, is designed to represent scarce governance rights and longer-term ecosystem participation.

GD has a fixed maximum supply of 390,000 tokens. Its maximum supply does not expand simply because SpartanOS gains more users, TVL, or applications.

Access to GD is also constrained by the original tokenomics. Relevant channels include rights allocated to early NFT holders, predefined governance and ecosystem allocations, GD governance rights associated with the RM Stable Vault, and secondary-market circulation.

An important distinction concerns the GD associated with the RM Stable Vault. Those GD rights are released linearly over 30 weeks, but they are not newly minted because the Stable Vault exists. They come from GD that was already allocated under the original tokenomics, including the original 25% liquidity-incentive allocation. The original allocation structure also includes a 5% protocol-treasury risk reserve. Therefore, the Stable Vault does not change GD's 390,000 maximum-supply logic.

The reason SpartanOS does not use RM for everything is that RM itself is designed to circulate through a much higher-frequency economic cycle: incentives → staking → bonds → liquidity → applications → release → market demand → burn. Combining that role with the ecosystem's scarcest long-term governance rights would place two different economic objectives into the same asset.

Stablecoins cannot fully perform this role either. Their primary economic purpose is stable denomination and settlement, rather than representing a scarce governance asset whose supply remains fixed while the ecosystem around it expands.

This separation of economic roles is not unusual in crypto. Major protocols have similarly separated settlement or productive assets from governance and ecosystem-rights assets. The comparison does not mean GD is equivalent to those tokens; it illustrates a broader crypto-economic principle: high-frequency economic circulation and scarce governance rights do not necessarily need to be represented by the same asset.

A conventional governance token could theoretically be designed with similar characteristics. Therefore, GD's differentiation is not simply that it is called a governance token. Its long-term differentiation must come from whether SpartanOS can continuously attach meaningful governance rights, application utility, and ecosystem participation to a fixed supply of 390,000 GD. The ecosystem can expand. Applications can expand. The user base can expand. GD's maximum supply does not need to expand with them. That is the core economic purpose of GD.

2. What creates structural demand for GD through actual SpartanOS usage?

Structural demand for GD cannot come from scarcity alone. Scarcity does not automatically create demand. Utility does.

The intended long-term demand structure for GD is: fixed supply + limited acquisition + governance demand + application utility + ecosystem expansion.

GD is beginning to move beyond being purely a governance asset and into actual application utility. For example, applications such as TempleRaid are bringing GD, RM, and other AnubisChain ecosystem assets into application-level use. This represents an important transition from simply holding a governance asset toward using that asset across both governance and applications.

As additional games, DeFi applications, RWA products, DID/NFT systems, trading infrastructure, and other DApps enter the ecosystem, GD can progressively support additional governance participation, application rights, ecosystem permissions, or other utility.

The economic relationship we want to establish is therefore straightforward: the number of applications can increase; the number of users can increase; the amount of utility attached to GD can increase; but the maximum GD supply remains 390,000. This is the important distinction between speculative demand and structural demand.

ETH provides a useful mainstream reference point for the principle, although its economic model is different. ETH demand is not based solely on people choosing to hold ETH; ETH is required for gas, participates in staking, and is used throughout the Ethereum ecosystem. GD must ultimately prove itself through the same broader economic principle: real utility must support long-term demand.

For that reason, GD should not be evaluated only by its market price. More meaningful metrics include the number of active GD addresses, ownership distribution, governance participation, number of applications using GD, application interactions, and actual on-chain usage. If the ecosystem expands while GD usage does not, then structural demand has not been proven. If more applications and users genuinely require GD while maximum supply remains fixed at 390,000, then GD is developing utility-driven structural demand.

3. RM is designed to incentivize users, developers, and community participation. What prevents RM from becoming a pure emission-and-sell-pressure token over time?

RM is not designed around emission control alone. SpartanOS attempts to manage both sides of the equation: how RM enters circulation and what creates demand for RM once it does. If a token's long-term economic path is simply mint → reward → sell, then increasing emission can eventually translate into persistent sell pressure. SpartanOS therefore combines controlled release, long-term locking, market-buy demand, burns, dynamic incentives, application demand, and liquidity balancing.

First, RM being generated does not mean that all RM immediately enters the open market. Long-term staking, 360/540-day long-term liquidity bonds, compounding, and the Energy system affect when and how much RM becomes actual circulating supply. The Energy system also creates an RM consumption path. RM can be burned to obtain 2–6× Energy value, while Energy staking itself follows a 360-day structure. RM therefore has a consumption mechanism in addition to its reward and trading functions.

Second, the 1:1 Turbo Engine introduces corresponding market-buy demand. Under the relevant reward mechanism, the system does not operate only on the reward side. Corresponding rewards require a 1:1 market purchase of RM, creating a demand side against token release. This is an important distinction. The objective is not to prohibit users from selling RM. The economic question is whether RM entering circulation is accompanied by sufficient real market demand. RM purchased through Turbo also enters a 24-hour silent period, while the baseline sell-side tax is 5%, reducing the possibility that the same purchase immediately becomes an equivalent short-term sell order.

Third, SpartanOS uses the O2 Adaptive Balancing Protocol. O2 operates on a three-hour cycle and incorporates TWAP while observing variables including buy/sell volume, average transaction size, buy/sell ratios, liquidity depth, and broader market conditions. When significant short-term supply-demand imbalance appears, sell-side protection can increase. When conditions normalize, the system re-evaluates conditions every three hours and progressively adjusts protection back toward the baseline 5%. The fastest return to baseline conditions within 24 hours still requires the relevant recovery conditions to remain satisfied continuously. O2 therefore addresses liquidity and supply-demand imbalance. It is not a mechanism that dictates what RM's market price should be, nor should it be interpreted as a price guarantee. The underlying principle is simple: price is the result; supply and demand are the cause. When imbalance occurs, protection increases. When balance returns, protection normalizes.

Fourth, SpartanOS uses AICS as a dynamic incentive layer. AICS operates on a rolling 30-day evaluation: Score = 0.2H + 0.4C + 0.2A + 0.2R. It evaluates network-health factors including referral structure, holder addresses, long-term participation, retention, activity, and contribution to the ecosystem. As a result, reaching the same nominal level does not necessarily mean receiving exactly the same incentives. Persistent heavy selling, weak retention, or declining long-term contribution can affect AICS evaluation. In simple terms: AICS evaluates network health; O2 manages market balance.

Long-term staking, 360/540-day bonds, compounding, locking, burns, and growing application demand then add further supply and demand components. The broader DeFi market has already demonstrated why this matters. High-emission liquidity-mining models without sufficient utility, locking, or real demand can eventually convert incentives into sell pressure. Other major crypto systems have responded to similar economic problems through combinations of locking, fee burns, buybacks, or utility demand.

SpartanOS combines: controlled release + 1:1 Turbo demand + long-term locking + burn + AICS + O2 adaptive balancing + application demand. The key long-term metrics are therefore not simply how much RM is generated. They are: new RM supply, actual circulating supply, 1:1 Turbo buy demand, application demand, long-term locked RM, burned RM, and liquidity depth. These mechanisms are designed to improve the supply-demand structure. They do not constitute a guarantee of RM's market price. Ultimately, sustainable demand must grow sufficiently to absorb sustainable supply.

4. What actual cash flows move through the ecosystem, and what percentage ultimately accrues to the protocol or token holders?

SpartanOS separates three concepts that should not be confused: capital flow, protocol accrual, and token holder value accrual.

SpartanOS is not accurately described as a simple traditional fund-allocation model where, for example, a user deposits $100 and a fixed X% automatically becomes protocol revenue while Y% automatically becomes token-holder income. The more accurate approach is to analyze both the asset side and the RM supply side.

When capital enters SpartanOS, depending on the specific product and its economic rules, that capital contributes to the protocol asset structure, including functions such as liquidity, treasury, POL, and other protocol assets. Different products can have different asset paths. A specific product can therefore be analyzed in terms of how much capital contributes to LP, treasury/POL, or other protocol functions. However, a product-specific asset allocation should not be presented as a universal revenue-distribution percentage for the entire SpartanOS ecosystem.

At the same time, the protocol determines the corresponding RM minting, locking, and future release obligations according to the rules of that product. This means that when $100 enters the protocol, the relevant economic question is not only "Where was the $100 allocated?" It is also "What protocol asset value was created by that $100, and what corresponding future RM supply or token liability was created against it?" That RM does not necessarily enter the open market immediately. Its economic path can involve: locking → controlled release → 1:1 Turbo demand → buyback → burn → O2 adaptive balancing.

Therefore, what matters economically is not simply "How much of the $100 was distributed?" A more meaningful question is: "What protocol asset value was created by that $100, what future RM supply was created against it, how and when does that RM enter circulation, and how does the market absorb that supply?"

A simplified representation is: capital enters the protocol → protocol assets / treasury / POL / liquidity → RM minting according to protocol rules → RM locking and controlled release → secondary-market supply and demand → O2 monitors market conditions → buyback / burn / protection / liquidity mechanisms respond → the system moves toward a new supply-demand equilibrium. In simple terms: SpartanOS does not simply divide deposits; it manages a token economy.

The second part of the question, what ultimately accrues to token holders, is equally important. Assets accumulated in treasury/POL represent protocol accrual. Liquidity contributes to protocol economics and market depth. Neither should automatically be described as cash income paid directly to token holders. Therefore: treasury ≠ holder dividend; liquidity ≠ holder dividend; token price appreciation ≠ cash-flow distribution.

At present, RM and GD holder value capture should primarily be understood as indirect value accrual rather than a traditional fixed dividend model. For RM, value accrual can occur through 1:1 Turbo market-buy demand, locking, changes in circulating supply, burns, application utility, and application-revenue-linked buyback/burn mechanisms where applicable. For GD, value accrual is associated with its fixed 390,000 maximum supply, governance rights, and expanding application utility.

The next major economic layer is external application revenue. As GoPlay, TempleRaid, and future games, DEXs, cross-chain applications, RWA products, trading infrastructure, and other DApps generate genuine external economic activity, it becomes possible to track how much application revenue enters treasury, how much strengthens liquidity, how much is used for RM buyback/burn, and whether any portion is explicitly distributed to holders. Unless a smart contract or explicit protocol rule states that X% of protocol revenue is directly distributed to RM/GD holders, protocol assets should not be represented as direct holder cash flow.

Therefore, there is currently no accurate universal formula such as "$100 deposited = X% goes directly to RM/GD holders." A more meaningful due-diligence framework is: for every unit of capital entering SpartanOS, what protocol assets are created or acquired, what corresponding RM supply or future token liability is generated, how is that RM released into circulation, and what mechanisms balance that supply against real market demand and liquidity? And then: how much external application revenue is ultimately captured by treasury, liquidity, buyback/burn, or direct holder distribution?

These distinctions are essential: capital flow ≠ revenue; protocol assets ≠ holder dividend; buyback/burn ≠ direct cash distribution.

5. What is SpartanOS's crypto-native moat?

SpartanOS's moat is not RM alone, GD alone, O2 alone, or a single smart contract. Tokens can be copied. Smart contracts can be forked. Tokenomic parameters can also be replicated. The potential moat comes from the network effect created when multiple economic, application, infrastructure, liquidity, developer, and community layers operate together.

The first layer is the economic layer: RM + GD + O2 + 1:1 Turbo + AICS + Stable Vault + long-term staking + long-term liquidity bonds + Energy + burn + compounding. These mechanisms address different parts of the economic system: supply, demand, liquidity, long-term participation, and network health.

The second layer is the application layer. GoPlay, TempleRaid, and future applications are intended to move RM and GD beyond an internal protocol economy and into real application utility. As applications generate users, transactions, and external revenue, the application economy can begin feeding economic activity back into the RM/GD ecosystem.

The third layer is the AI / intent / execution layer. Intent infrastructure such as dappOS represents an important direction here. Its significance is not simply attaching an "AI" label to Web3. The objective is to reduce the complexity of blockchain interaction. A user expresses an intent; the relevant infrastructure can assist with routing, execution, and DApp interaction, while final asset ownership and settlement return to the blockchain layer. In simple terms: AI handles intelligence and execution assistance; blockchain provides trusted state, assets, and value settlement.

The fourth layer is blockchain infrastructure. SpartanOS uses AnubisChain for smart-contract execution and asset settlement, while the broader ecosystem connects with infrastructure across wallets, bridges, DEXs, explorers, indexing/data infrastructure, and cross-chain systems including areas such as The Graph, Blockscout, and LayerZero.

The fifth layer is ecosystem expansion. From Q3 onward, the ecosystem roadmap includes progressive development across: LayerZero + OFT cross-chain infrastructure, explorer upgrades, RocketSwap V3, Guard multisig, NFT + DID, AI Meme / AI Agent, RWA tokenization, a decentralized contract-trading platform, and contract-trading insurance. These should not all be represented as already-live revenue-generating products. Live products should be evaluated through product usage and on-chain data. Integrations under development should be evaluated through technical progress and official announcements. Future products should be verified through contracts, transactions, users, and revenue once deployed.

Major crypto networks demonstrate why this distinction matters. Ethereum's moat is not simply the EVM source code. Its network effect comes from developers, liquidity, wallets, applications, infrastructure, standards, and users interacting with one another. Likewise, an AMM formula itself can be forked; recreating the liquidity, integrations, users, developer tooling, and network effects around a mature DEX is significantly harder.

The network SpartanOS is attempting to build is therefore: token economy + liquidity + AI/intent + applications + blockchain infrastructure + developers + users + global community. It would be premature to describe this as an absolute, uncopyable moat. A more accurate description is that SpartanOS is building a network moat, whose strength must ultimately be demonstrated through liquidity depth, active users, application adoption, developer activity, external revenue, and cross-ecosystem integrations.

6. What exactly is verified on-chain, and what is merely asserted by off-chain AI infrastructure?

SpartanOS makes a clear distinction between on-chain state and off-chain computation.

Information that can be independently verified on-chain includes: wallet addresses, token contracts, RM/GD transfers, swaps, liquidity changes, burns, smart-contract interactions, transaction hashes, and final asset settlement. These facts do not require a user to trust what the SpartanOS frontend says. They can be independently checked against the relevant blockchain state through explorers and, where supported, third-party blockchain data/indexing infrastructure. That is one of the core properties of blockchain: users should be able to independently verify critical asset and transaction states rather than relying solely on the protocol's own interface.

However, not every component of the system is automatically on-chain. Elements such as portions of AICS scoring computation, intent interpretation, external-data analysis, API calls, agent decision-making, and other off-chain computation must be treated separately. If an off-chain system performs a calculation and then submits a transaction to the blockchain, the blockchain can prove that the final transaction occurred. It does not automatically prove that every preceding off-chain computation was correct. Therefore: result on-chain ≠ entire computation on-chain.

The trust boundary is more accurately described as: AI / off-chain infrastructure handles intelligence, analysis, and execution logic; blockchain verifies trusted state, assets, transactions, and final value settlement.

If off-chain computation itself needs to become cryptographically verifiable, additional technologies may be required, depending on the implementation, including public algorithms, oracles, TEEs, ZK proofs, cryptographic signatures, validator networks, or other verifiable-computation systems.

We therefore distinguish between on-chain facts, independently verifiable through blockchain state, and off-chain computation, requiring its own verification mechanism. A result being written to the blockchain should not be presented as proof that the entire off-chain computation was itself performed or verified on-chain.

7. How does SpartanOS prove an AI agent actually performed the service it claims to have performed?

There are two separate levels of proof: execution result verification and computation verification.

If an agent claims that it completed a transfer, swap, stake, or smart-contract interaction, the user should not have to trust a frontend message saying "Completed." The primary proof should be the blockchain. A user should be able to verify the transaction hash, contract call, input assets, output assets, wallet-state changes, and final settlement.

For example, if an agent claims "I swapped Asset A into Asset B for you," the relevant proof is not the agent's own statement. The user should be able to verify whether the transaction actually exists, which smart contract was called, how much Asset A left the wallet, how much Asset B was received, and whether the transaction successfully settled. That is execution result verification. Blockchain is particularly effective at proving that an asset-related action actually occurred.

However, a transaction hash does not automatically prove why the agent made a particular decision, whether every input was accurate, or whether every internal reasoning step was correct. That is a separate problem: computation verification. If the objective is to cryptographically verify the agent's internal computation, additional mechanisms may be required, such as TEEs, ZK proofs, oracle systems, validator networks, cryptographic signatures, or other forms of verifiable computation.

We therefore do not make the technically inaccurate claim that "because the transaction is on-chain, every AI computation behind it is automatically trustworthy." The more accurate model is: AI understands intent, performs analysis, and assists execution; blockchain verifies asset state and final execution.

Intent infrastructure such as dappOS illustrates the broader direction: users do not necessarily need to manually understand every blockchain operation involved in fulfilling an intent. The intent/execution layer can simplify routing and execution, while critical asset outcomes should still return to blockchain-verifiable settlement.

The principle is straightforward: do not rely only on an agent saying "I completed the task." Verify whether the blockchain proves that the task was actually completed. If the requirement goes further, to prove why the agent made the decision or that its internal computation was correct, then that requires a separate cryptographic or verifiable-computation layer, and should be evaluated according to the actual verification technology deployed.
Quote an answer whole, or send the link to this section, rather than a sentence from it. Each answer carries its own limits in its own words: the mechanisms guarantee no price, treasury is not a dividend, a transaction on the chain does not prove the computation behind it, roadmap items are not live products, and the energy multiples are dynamic parameters read from the dApp on the day. A promoter who leaves those limits out is no longer quoting the project.
15 objections a promoter hears in the first week. Each has a short answer to say out loud, a longer one for when they push, and the line not to say. Copy the short answer into a chat; open the section it points to for the evidence.
Ask what they mean, then answer the mechanism. A Ponzi pays old money with new money and hides it. Here every payout is a purchase: the turbine makes each claim buy the same amount of RM on the DEX before it is released, the treasury, the liquidity and the fund addresses are on a public explorer, and every long-term position has a cap fixed in dollars the day it opens.
The honest version has three parts. First, what is verifiable today: the bridge reserves on Etherscan, the treasury and liquidity figures on the dApp dashboard, RM trades and TempleRaid rounds on browser.anubispace.org, the CertiK assessment of the Spartan OS contracts (zero critical, zero major, three medium resolved). Second, what is the project's own statement rather than a fact you can check: the rates, the roadmap, the user numbers. Third, the risk: rates float, the price moves, the sell tax rises on the way down, and a cap means a position ends. Someone who hears all three from you will trust the rest.
Do not say 'it cannot be'. Do not compare it to a bank. Do not quote the annualised figure.
They are high, they float, and they are capped. 1.1% to 1.3% a day on a long-term position is the stated rate on the day; the cap is 4× to 5× of what went in, fixed in USDT; the flexible pool pays around 0.3% per twelve hours and can move. Say the cap in the same breath as the rate, every time.
Explain where the payout comes from as the project describes it: the RM emission, the sell fee split (0.5% platform, 1.2% buyback, 1.3% community, 2.0% ecosystem), the extra sell tax on the way down, and the turbine that turns every claim into a purchase. Then explain what limits it: the cap on every long-term position, the rebase snapshot, and the O² protocol that slows selling when the price falls. High and unlimited is a story. High, capped and dated is a term sheet.
Never say 'guaranteed'. Never project a month's income as if the rate were fixed.
Anubis Foundation, which built Origin (LGNS), WebKey and Melos, and now its own chain. Anubis Labs is the funding arm; Spartan OS is its first application. The team publishes under the foundation's name rather than personal names, which is common in this part of the industry and is a fair thing to dislike. What you can check is the work: the chain has been live since April 2026 with over 100 million transactions, and the contracts were assessed by CertiK.
The foundation's footprint is public: two years, five continents, a hundred projects, and Origin's snapshot of 2.5 million holders and a $1.4 billion market cap at its peak. Company management runs Spartan OS with a stated plan to run it for years, and to run it bigger and better than Origin. The Dubai office and the leader meetings are where people meet them in person. Say plainly that founders are not public by name, and that the person deciding should weigh a public codebase, a public chain and an audit against that.
Do not invent a founder's name or nationality. Do not claim to have met anyone you have not met.
Yes. RM is a traded token; the dollar value of every payout depends on the price on the day. Selling into a fall carries a tax that rises with the fall. TempleRaid is a game of chance. A long-term position cannot be unwound early. Anyone who tells you otherwise is not describing the programme.
Then describe what the project has built to reduce the damage, without turning it into a floor: caps fixed at entry so a position cannot chase, the turbine that converts claims into purchases, O² that raises the sell tax and protects liquidity when the price falls 5% or more against the three-hour average, the buyback fund, and the Price Stability Fund of 1,000,000 USDT at a published address. None of these is a guarantee. All of them are on the dApp or the explorer.
Do not say 'you cannot lose'. Do not say the price 'always comes back'.
You can, after one step. Every claim goes into the turbine: you buy the same amount of RM on RocketSwap, the claim unlocks after 24 hours, and the purchased RM is yours as well. Level income needs energy on top, one unit per RM, from a 360-day stake or from burning RM.
The turbine is the mechanism the project points to when asked how a token paying daily returns has stayed above $30 for months: the returns themselves are buy pressure. It also means every payout costs a matching purchase before it can be sold, which a promoter should say out loud. Energy applies only to the 8%, 4% and 2% level income, not to personal staking, bonds or rank rewards.
Do not describe the turbine as a fee. Do not skip the 24 hours.
Spartan OS completed a CertiK assessment on 2 August 2026: governance multisig, treasury, staking, reward distribution and core token contracts, with zero critical and zero major findings and three medium findings resolved. GaleBridge was audited by CertiK in October 2025. Anubis Chain states 137 core contracts verified with CertiK and Armor. Every bridged asset is minted one to one against assets locked in bridge contracts you can read on Etherscan.
Safety on the way in is mostly the user's own: chain ID 6714, addresses typed from this page, the first four and last four characters checked, a small test first, the seed phrase on paper. Two current notices matter: there is no official 'Anubischat' app, and CertiK warns about malicious code repackaged into iOS apps. Forward both. An audit covers the code. It does not cover a phishing link.
Do not say 'audited' without saying by whom and when. Do not send links from chats.
Then you already know the two questions that matter: what limits the payout, and what happens on the way down. Spartan OS answers the first with a cap fixed at entry and the second with O², the sell tax and the buyback fund. Origin required three legs; Spartan OS requires two. The codebase is the one Origin ran, on a chain the same foundation now owns.
Do not argue about the past. Ask what went wrong for them: usually an uncapped rate, an exit that was closed, or a promise from a promoter. Show the cap, show the turbine, show the sell tax table, and show the explorer. Then let them decide the size, and suggest a small position first. About $55 million remains in Origin's pool on Polygon two years on; that is a fact about longevity, not a promise about this one.
Do not disparage other projects by name. Do not promise this one is different; show what is different.
The programme pays for building a community, in the open: 8%, 4% and 2% of the ROI on three levels, then twelve ranks paid from the DAO pool on the smaller leg. The referral link is how the dApp knows who introduced whom. Nobody earns from a recruit's deposit; the level income is a share of what that person's own position earns.
Say what the rank structure demands before saying what it pays: your own position, a number of directs from 100 USDT, and volume in two legs, with the larger leg qualifying and the smaller one paying. Most people will sit at V1 to V3. Use the rank calculator with their real numbers rather than the top of the table. The referral link is theirs to use or not; the staking products pay the same either way.
Do not sell the ladder above V5 to someone who has not opened a first position. Do not call it 'passive'.
It stops paying. A 540-day position that took $1,000 has paid out $5,000 of RM value, principal included (confirmed 26 September 2026: the capital counts inside the cap and is not paid on top). If the cap arrives before day 540, the capital not yet released is frozen until you open a new 540-day order larger than that remainder; then it resumes its release on the original schedule (as stated 16 October 2026). If day 540 arrives first, rewards stop that day, cap reached or not. Either way you open a new order if you want to continue. Flexible staking has no cap and no term; the principal can be withdrawn at any time.
At the stated rates the 360 and 540-day positions reach their ceiling in about ten to eleven months, before the term ends; the 180-day position reaches the end of its term first, at about 3× of the entry, below its cap. The burning bond releases 250% of the order in about five and a half months at 1.5% a day. Say which one applies, and that all of this is arithmetic on today's stated rate, which floats.
Do not describe the cap as a loss. Do not promise a renewal on the same terms. Do not say the frozen capital is lost: it is released once the new order is active.
Because the foundation is, and because its community was built there first: Origin's 2.5 million holders, the Melos and WebKey users, the launch events in Kuala Lumpur and the region. The English material exists because that community is now being built here. The chain, the contracts and the explorer do not have a language.
This library exists for that reason: the official documents translated or reproduced as issued, the announcements in plain English with the date, the tutorials with English captions, and one place to check a figure. If a person's concern is really about accountability rather than language, answer it with the audit, the public chain and the meetings in Dubai.
Do not make it about nationality. Do not translate a number you have not checked.
You can. Do not. Start with an amount you would not miss, run one full cycle (stake, claim, turbine, release), then decide. The programme rewards long-term positions, and a long-term position cannot be unwound early, so the second decision should be made with the first one behind you.
A leader who tells a new person to start small is the leader that person stays with. Show the minimums: 1 USDT for staking and bonds, 500 USDT for the stability vault, 200 USDT for the extra-reward bucket on 360 and 540-day positions. Then show what each product pays at their number on the calculator, cap and date attached.
Do not set a target. Do not stack products for a stranger.
None, because that is not the model. Spartan OS says capital entering the protocol goes to the asset side, liquidity, treasury and protocol-owned liquidity, while RM is minted against it under the protocol's rules, locked, released in a controlled way and balanced by O². A percentage would describe a fund that splits deposits, which the project says it does not run.
Give the two sides in one breath: what protocol assets the money creates, and what future RM supply is created against it and how it reaches the market. Then hand over the project's own due-diligence question: for every unit of capital, what assets are created, what RM supply or future liability is generated, how it is released, and what balances it against real demand and liquidity. Point at the data that answers it: net RM issuance, buyback and burn volumes, POL and liquidity depth, retention, and the 13 September fall and recovery.
Do not invent a percentage to satisfy the question. Do not say the mechanisms guarantee anything; the statement says they cannot control behaviour.
That is the risk the design is built around, and the project says so in its own due-diligence answers. RM does not reach the market when it is minted: long-term staking, the 360 and 540-day bonds and compounding hold it back; every Turbo claim needs a purchase of the same size, which then sits in a 24-hour silent period; RM burned for Energy leaves supply for good; O² raises the sell-side protection when selling runs ahead of buying; and the applications are meant to consume it. None of that guarantees a price.
Give them the numbers to watch instead of an argument: new RM supply against circulating supply, Turbo buy demand, RM locked long term, RM burned, and liquidity depth. Those are the project's own metrics, and all of them are on the dashboard or the explorer. The one line to keep: the mechanisms improve the structure of supply and demand; whether demand grows enough to absorb supply is what the data will show, and nobody can promise it.
Do not say RM cannot fall. Do not say O² stops selling; it slows a cascade and gives liquidity time.
It is a game of chance with money at stake, on chain, with provable randomness and sixty-second rounds, and a player can lose what they enter. It is one application on Spartan OS, not the programme. Nobody needs to play it to stake.
The project describes an insurance mechanism behind it and the rounds are readable on the explorer. Say the risk before the feature, every time, and never send the game to someone who asked about staking.
Do not describe TempleRaid as income. Do not send it to anyone under 18 or in a jurisdiction where it is unlawful.
They are the project's numbers, with the project's own label on them. 35 million USDT is the stated total capital foundation on 26 September 2026; on 19 October 2026 the project stated 39 million (35 million in the RM/USDT pool, 4 million in reserve), and on 27 October 2026 40 million (36 million in the pool, 4 million in reserve) with 41 million as the next target. 36 million and 50 million are what the message to the international partners calls development goals, and the same paragraph says they are not guarantees of returns or of the RM price, which is set by supply and demand, liquidity and ecosystem development.
Send the message whole rather than the milestone line. Its argument is the opposite of a promise: the project reached 35 million through a cycle that included a correction and a period when confidence was tested, and it tells new markets that story so they do not mistake growth for a straight line. The reader can check the dashboard figures in Terms today against the 35 million and draw their own conclusion about the distance to 50.
Do not say 'we are going to 50 million'. Do not turn a goal into a date. Do not quote the milestones without the sentence that follows them.
Every answer here repeats what the project has stated or what can be checked on a public page. None of them promises a return, and none of them should be sent with a rate attached that has no cap and no date.
Four tables for the two questions every promoter hears: why this chain, and why this programme. Two are ours, against common designs; two are the project's own, reproduced as issued. Say which one you are quoting.
| Typical EVM chain | Anubis Chain, as described by Anubis | |
|---|---|---|
| Fee unit | The chain's own token; the fee moves with its price | gasDAI, pegged to DAI; the same fee every day, a fraction of a cent |
| Pending transactions | Visible to block producers; front-running and sandwich attacks possible | Encrypted until their place in a block is fixed; front-running prevented by design |
| Privacy | Everything public, or everything hidden on a privacy chain | Public by default; a user can shield identity while the protocol stays auditable |
| Finality | Probabilistic on many chains; reorganisations possible | Final once two thirds of validators sign; no reorganisation |
| Tooling | Varies by chain | Ethereum tooling unchanged: MetaMask, Solidity, Hardhat, Remix |
| Who owns it | A separate team from the applications on it | The foundation that built the first application also built the chain |
| Where to check | Varies | browser.anubispace.org, chainlist.org/chain/6714, etherscan.io for the bridges |
Left column describes common designs, not any one named chain. Right column as described by Anubis Chain in its documentation and the technical guide; the fee unit and chain ID are verifiable on chainlist.org.
| Traditional public blockchains, as Anubis describes them | AnubisChain, in its own words | |
|---|---|---|
| Positioning | General transaction network or high-performance execution network | AGI privacy public chain |
| Privacy | Full basic transparency, limited privacy functions | Zero-knowledge proofs with selective privacy protection |
| Intelligence | Centred on smart-contract execution only | AGI, AI agents, intelligent analytics and automated services integrated |
| Assets | Circulation of on-chain assets only | On-chain assets, RWA, DeFi and digital capital together |
| Data trust | Basic on-chain traceability | Verifiability across transparent assets, cross-chain records and reserve relationships |
| Ecosystem | Isolated applications developed in parallel | Applications, assets, traffic, AI, tooling and developers coordinated |
| Developer support | Limited underlying deployment support | Toolkits, incubation, AI integration, global collaboration |
| Scalability | Optimised for single standalone businesses | Built for long-term growth of intelligent ecosystem systems |
Reproduced from the infographic 'AnubisChain × Spartan OS' issued by the Spartan OS team in July 2026. Both columns are Anubis Chain's own description; the left column names no specific chain. Treat it as the project's positioning, not as an independent benchmark.
| Other Olympus-style programmes, in general | Spartan OS, as stated on 7 and 14 September 2026 | |
|---|---|---|
| Principal | Held until the term ends | Released in daily portions from day one, together with interest and extra rewards, all of it inside the cap |
| Cap on payout | Often none | 4×, 4.5× or 5× of entry value, fixed in USDT at entry |
| Team structure | Three legs (Origin: three teams at $50,000) | Two legs; V1 at $500, three directs and $10,000 a leg |
| What a payout does | Sits in the wallet, ready to sell | Passes through the turbine: an equal purchase, then a 24-hour wait |
| Selling into a fall | Same cost as any other sale | Tax climbs from 5% towards 30% as the price falls against its three-hour average |
| Same rank, same pay | Usually | AICS score moves pay within the band: the active leader earns more than the passive one |
| The chain | Rented | Owned by the foundation that built the programme |
As stated by Spartan OS; rates float and caps are fixed at entry. Not a promise of return.
| Olympus DAO | O² Adaptive Balancing Protocol | |
|---|---|---|
| Liquidity | Protocol-controlled liquidity (POL) | POL plus dynamic liquidity adjustment (AI and strategy layer) |
| Yield model | High APY, rebase-driven | Revenue cap mechanism plus adaptive release |
| Market regulation | Relies on game theory and market self-balancing | Active strategy adjustment (APG × APH) |
| Stability logic | Unanchored value support | Sentiment plus data-driven stabilisation |
| Supply | Primarily rebase expansion | Minting × burning × buyback, three-way balance |
| Risk control | Relies on participant behaviour | Protocol intervention: tax rate, buyback, LP |
| Governance | DAO governance | DAO plus multi-signature plus layered strategy execution |
| Flexibility | Mostly fixed mechanisms | Dynamic parameter adjustment |
Page 29 of the Spartan OS Economic Model Analysis, as issued. A comparison written by one side; the Olympus column is Spartan OS's summary, not Olympus DAO's.
Two A4 documents for anyone, and the Phalanx handbook: the steps, today's terms, every answer and every objection in one file for the phone. The leader document sits in the Leaders area.
Who built it, what runs on the chain, the ninety-day record, the programme in outline, O², the glossary and the official links.
How to start in seven steps, the bond first and staking after, the terms as shown on 9 November 2026 with the twenty-one published contracts checked, every knowledge card by topic, the objection scripts, the eleven due-diligence answers, the message to the international partners and the bond texts, the announcements, the safety rules and the official links. For reading offline and for printing.
Network parameters, architecture, contracts, audits, thirteen step-by-step guides, the safety checklist and troubleshooting.
The whitepaper, the project's own deck, the economic model deck, the chain's hundred questions and the brand manual, from the official Resource Library. Send these when someone asks for the source rather than the summary.
Industry background, platform positioning, the five systems, the six-layer technical architecture, the GD and RM model, security and governance, the five-phase roadmap. The source document for every architecture question.
The project's own presentation: platform foundation, the AI compute engine, the token hub, market context with sources, the builder network, growth indicators, the three-phase roadmap.
GD allocation, the Genesis NFT, staking pools and bonds, AICS, TriZone, the DAO reward pool, energy release, the turbo pool, the fee split, the four-layer stability engine, O² against Olympus DAO. Every page is also viewable below.
The chain's own FAQ: fundamentals, architecture, pegged assets, wallets, transactions, ecosystem, security, future plans, Anubis Labs. Most technical questions a promoter hears are answered here first.
Logo, clear space, colour and typography rules for the Anubis mark. Use it when a poster or a banner carries the Anubis logo.
Pages are pictures of the deck as issued. GD allocation is page 5, the rank table page 16, energy page 17, the fee split page 20, O² against Olympus DAO page 29.
For Telegram, WhatsApp and X. The image is for chat; the PDF is for print or an attachment. Six pages, all for anyone; the leader edition sits in the Leaders area.
The chain in one page: what runs on it, what the explorer shows, who built it.
Two tokens, five income streams, the rank ladder. The page to send first.
Anubis Foundation, the chain, the bridge, the DEX, TempleRaid and Spartan OS as one stack.
The first application: how RM and GD flow into the game, and what a player does.
Where every token goes: staking, bonds, the turbine, the sell tax, O².
Seven steps from a wallet to the first bond, with the five official links as scan codes. Staking comes after.
Twelve slides from Spartan OS on how O² reads the market and when it acts. This is the deck for the question that comes after the price question: what happens on the way down. Slide 11 of the promoter deck is the short version; this is the long one, as issued.
Olympus DAO as the starting point, the four-layer stabilisation engine, the market signals O² reads, dynamic tax and liquidity protection, the three-hour monitoring and rollback cycle, the sentiment engine, supply contraction in extreme conditions, the execution safety loop, and the flywheel. The slides are pictures: present them, do not retype them.
Click a slide to view it full size. O² is a balancing mechanism, as described by Spartan OS; it is not a price guarantee, and nothing on these slides is one.
The official one-picture explanations, posted by the Spartan OS team between June and July 2026. Open one to read it; use the arrows to move through the set; save the full-size file to send it in a chat.
The V1 to V4 'profit maximisation' layout images that circulate in Chinese are not included: they are income projections, and this library carries no projection of return.
Recorded by the Phalanx team on the real apps, English voice and captions, two to four minutes each. Pick your wallet once and every lesson shows the film for it: Bitget Wallet and AstraCore for the whole path, TokenPocket for the wallet lessons. Each lesson links to its written version in Get in, and the chain settings and token addresses the films point to are in section 20, Links.
Install the wallet from the store, make a new wallet, back up the seed phrase on paper, switch to Anubis Chain.
No separate film for this wallet: the steps inside the dApp are the same, so the Bitget film is shown.
Import the two Spartan OS tokens by contract address so the wallet shows them. The addresses are in section 20, Links.
No separate film for this wallet: the steps inside the dApp are the same, so the Bitget film is shown.
Buy USDT on an exchange, withdraw it to the wallet on BNB Chain (BEP-20), with a little BNB for gas there.
No separate film for this wallet: the steps inside the dApp are the same, so the Bitget film is shown.
The bridge, typed by hand: USDT from BNB Chain to Anubis, and BNB swapped and bridged into the gasDAI that pays every fee. Covers B2, B3 and B4.
No separate film for this wallet: the steps inside the dApp are the same, so the Bitget film is shown.
Open the dApp through the referral link or enter the code, connect the wallet on Anubis, let it synchronise. The referrer binds once.
No separate film for this wallet: the steps inside the dApp are the same, so the Bitget film is shown.
What every line on the dashboard means: balances, the live rates and caps, the products, the invite page. One film for every wallet.
No separate film for this wallet: the steps inside the dApp are the same, so the Bitget film is shown.
The swap from USDT into RM on the chain's DEX, one to one with the turbine in mind. Also the move the turbine asks for after every claim.
No separate film for this wallet: the steps inside the dApp are the same, so the Bitget film is shown.
The flexible product: enter, read the rate on the screen, leave when you want. Staking comes after the bond, once you are in the system and hold RM bought from your leader.
No separate film for this wallet: the steps inside the dApp are the same, so the Bitget film is shown.
The long staking product and the activation the dashboard asks for. The bond comes first (C6); staking follows once you are in and hold RM bought from your leader. This film is for that stage.
No separate film for this wallet: the steps inside the dApp are the same, so the Bitget film is shown.
The 540-day bond: RM at the bond price, released daily, cap 5× fixed at entry. Read price, discount and cap on the screen before confirming.
No separate film for this wallet: the steps inside the dApp are the same, so the Bitget film is shown.
The stable vault product: what it holds, how it releases, where it sits on the dashboard. Read the terms on the screen; they float.
No separate film for this wallet: the steps inside the dApp are the same, so the Bitget film is shown.
Every release is claimed through the turbine: the one-to-one purchase on RocketSwap, the 24 hours, RM and GD in the wallet. One film for every wallet.
No separate film for this wallet: the steps inside the dApp are the same, so the Bitget film is shown.
Bridging back from Anubis to BNB Chain and from there to an exchange. Never send Anubis assets straight to an exchange. One film for every wallet.
No separate film for this wallet: the steps inside the dApp are the same, so the Bitget film is shown.
A1 the wallet, A3 the tokens, B1 funds on BNB Chain, B2 the bridge and the gasDAI, C1 join, C2 read the dashboard, then the products (C3 to C7), D1 the claim. B5, the way out, is at the end because it is the one film everyone should have watched before they need it.
The films show the wallets and the dApp as they were at the end of September 2026; screens change, the parameters do not: chain ID 6714, RPC rpc.anubispace.org, fees in gasDAI. Where a film shows a rate, it is the rate on the day of recording. Nothing in a film is a promise of return.
The official Spartan OS and Anubis Chain films from the Resource Library, for a status, a story or the first minute of a call. Compressed for the web; ask your team lead for the full-resolution originals if you need them for a screen.
These are the project's own productions; the claims in them are the project's. Nothing in a film is a promise of return, and none of them should be sent with a rate attached.
The same five as slide 15 and one-pager 06, then the six channels added in September: Anubis Chain's new primary account on X, Anubis Labs, the official Resource Library, AC Wallet, the launchpad and the developer docs; then the four official libraries in other languages. They open on click and scan from a phone.
Type them or copy them from here; never from a chat. Compare the first four and the last four characters before you save. The full list of twenty-one contracts, each checked on the explorer, is in Terms today.
| Network name | Anubis | |
| RPC URL | https://rpc.anubispace.org | |
| Chain ID | 6714 | |
| Currency symbol (shown as gasDAI) | DAI | |
| Block explorer | https://browser.anubispace.org |
Anubis Chain · network settings
Network name: Anubis
RPC URL: https://rpc.anubispace.org
Chain ID: 6714
Currency symbol (shown as gasDAI): DAI
Block explorer: https://browser.anubispace.org

Token contract addresses on Anubis
RM token (Rome): 0x2e045e1380f5f5b6e7550328910a7377c9fce59d
GD token (Gladiator): 0x21b6b0b3fab224921d3054d187e324a673411b4c
USDT (pegged): 0xDfb6a28BC6DC51fed17c27C880F2c66cDd040A3e
DAI (pegged): 0x83fd06F0846d9D90B3016bF670Efe2E0B11cDe14

Compare the first four and the last four characters before you save an address. Source: Spartan OS service account list of 25 and 26 September 2026, each address checked on browser.anubispace.org.
 Anubis ChainOfficial siteanubischain.ai
 Spartan OSOfficial account on Xx.com/Spartan_Arena_
 Anubis ChainPrimary account on X since 9 October 2026x.com/AnubisLayer1
 Anubis BridgeMove USDT or DAI onto the chainapp.anubisbridge.com
 ExplorerEvery figure, checkablebrowser.anubispace.org
 Anubis ChainEcosystem account on X; primary from 16 September to 9 October 2026x.com/AnubisChainL1
 Anubis LabsOfficial account on Xx.com/Anubis_Labs
 Anubis ChainEarlier account on X; the June to September 2026 announcementsx.com/ANUBISCHAIN_
 Resource LibraryOfficial English library on Telegramt.me/SpartanOSLibrary
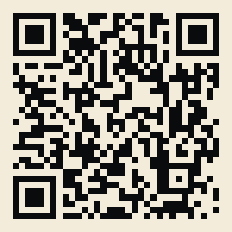 AC WalletAstraCore wallet, iOS and Androidapi.astracorewallet.app
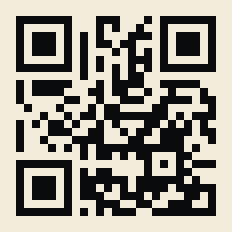 Capybara LaunchOfficial launchpadcapybaralaunch.com
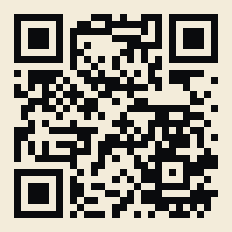 Developer docsAnubis Chain documentation on GitHubgithub.com/anubis-chain/docs
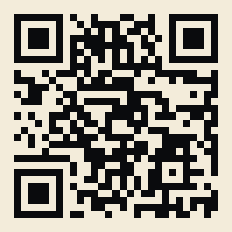 Chinese librarySpartanOS华语资料库 · Telegramt.me/SpartanOSResourceLibraryCN
 Korean librarySpartanOS 데이터베이스 · Telegramt.me/SpartanOSKoreanLibrary
 Japanese librarySpartanOSデータベース · Telegramt.me/SpartanOSJapaneseLibrary
 Vietnamese libraryCơ sở dữ liệu SpartanOS · Telegramt.me/SpartanOSVietnameseLibrary
Each address opened and checked on 26 September 2026. Send a member the library in their own language rather than a translation of this one. The English library is the reference for India until the Hindi materials the project promised on 25 September are published.
 RocketSwapThe DEX on Anubis Chainrocketswap.org
 Hurricane bridgeCross-chain bridge, GaleBridgegalebridge.net
 BridgersThird-party cross-chain bridgeapp.bridgers.xyz
Verify the first four and the last four characters of every address before approving. Take links only from anubischain.ai. Keep the seed phrase offline. No official account will ever ask for it.
These six pages are run by third parties and were listed by Anubis Chain on 20 September 2026. They opened at the time of publishing; what they show is theirs, not Spartan OS's.
Fifteen Spartan OS stickers with English captions, and the twenty Anubis stickers the chain's team published on 18 September 2026. One tap adds a set to Telegram; the files are here for WhatsApp and other apps.
Scan from a phone, or tap the button. The set installs in a second.
Fifteen files, 512 × 512, WebP. Tap one to save it for WhatsApp or any other app.
 Let's go!
 Unbeatable!
 Guard the consensus!
 Well done!
 Rally!
 Onward, together!
 Seize it!
 Compounding!
 Only up!
 Copy that!
 300 warriors, assemble!
 Spartan OS, unstoppable!
 Fearless, to the summit!
 Shield up, mission delivered!
 Spartan OS, building the future!
Scan from a phone, or tap the button. The set installs in a second; the stickers are animated.
Twenty animated previews below; tap one to save the original WebM (512 × 512, Telegram's video-sticker format). The zip holds all twenty.
One hundred pieces for TOKEN2049 and after: 80 black, 20 bone; 72 tees, 28 hoodies; ten themes, from the god of the chain to Singapore. The lookbook shows every piece; the print files are ready for any DTG or DTF printer at 300 dpi, with the placement in the spec sheet.
Top edge of a front print 7 cm below the collar seam; 30 cm wide on M and up, 27 cm on S. Hoodie backs 36 cm wide, left-chest hits 9 cm. White underbase on black garments. Two designs, 007 and 024, have a v2 file with the print height capped; the spec sheet says which.
The Spartan OS one-colour emblem (the helmet inside the ring, 28 September 2026), the office and environment brand book, the roll-ups for print, the stand and office renders, and the Phalanx avatar. Use the files as issued; the official full-colour marks stay as the project supplies them.
Black ground, brass marks, one lime line. The one-colour emblem is for cut vinyl, etched brass, door plates and one-colour print; the official full-colour emblem stays for screens and the merchandise. The emblem, the room names and the quote sentence are proposals to the Spartan OS team until confirmed; nothing is fabricated before that.
Most conversations are won or lost by what arrives first and how much of it there is. Send less, in the right order.
The promoter deck is the whole story in fifteen slides, from the Anubis Foundation to the official links. Send the PDF with the first message below and nothing else.
For someone new to all of this, send the plain guide instead: one page, large type, the same figures with their dates, four steps. spartanphalanx.app/start. Added 9 October 2026.
Two days later, one-pager 06, Getting started, and the two sticker sets. One page answers the practical questions; the stickers make the group feel like a team.
The leader document, the presenter kit for Zoom, one-pager 07, the meeting policy, the rules confirmed and the rules still open, and how a leader's week runs. Open to every leader; use it in calls and in the team, not on public channels.
Staking, bonds, energy, the turbine, level income, the ladder, O², how to present. Not for public posting.
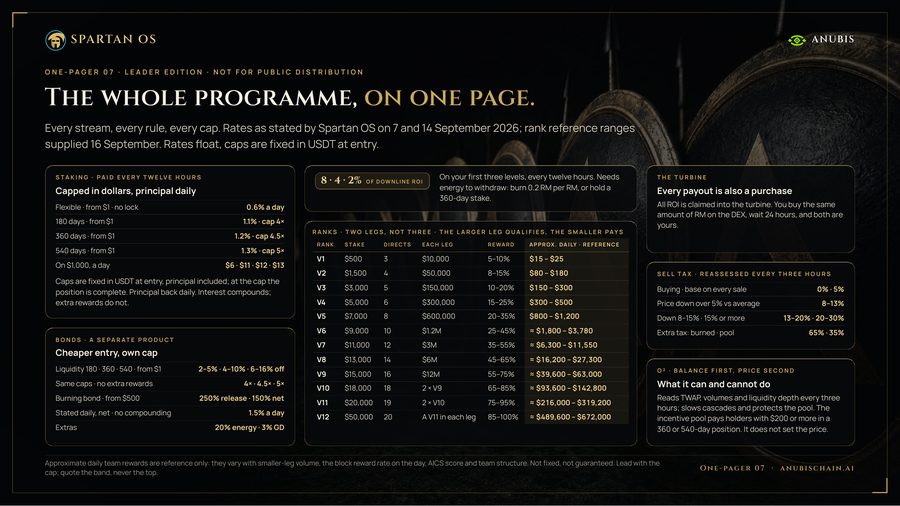
The fifteen slides with what to say on each, the timings, the objections and the close.
A community with the required qualification applies in advance with a fee by size: 500 USD for 30 people, 800 USD for 50, 1,500 USD for 100. Online or in a community group, hosted by local leaders with core team members present. If performance after the event reaches at least 150% of the fee, the excess is paid back; if not, the host community covers half the cost. Apply three to five days ahead, pay electronically, get approval before the event, keep screenshots and the link. As published in the Resource Library; confirm current terms with the operations team.
Confirmed on 24 September 2026: the differential is the difference in percentage between two ranks, paid to the higher rank (V7 at 60% and V8 at 70% gives the V8 10%); V10 to V12 need two legs each holding the rank below, not a volume; the small zone is the combined smaller legs. Confirmed on 26 September 2026: the same-rank bonus is 10% to 15% of the applicable earnings of the nearest same-rank position under you, once, and the override (overtaking) reward follows the same nearest-position principle; the V12 personal stake is 50,000 USDT and the 25,000 on one page is not to be used; the energy multiples are whatever the dApp shows on the day (260% staking, 557% burning on 26 September, both dynamic), and the 150%/200% and 2 to 6 times figures in older material should not override them; the capital sits inside the 4×, 4.5× and 5× cap and is not paid on top. Still open: where inside 10% to 15% a given bonus lands, and whether two same-rank positions in two different legs both pay. The calculator applies the confirmed rules on estimated bases and says which part is estimate.
Lead with the bond at this stage rather than regular staking: the project's answer on 25 September, on the grounds that the bond carries a discount (10.64% and 14.79% below market for 360 and 540 days that day, floating) and that principal and rewards release daily. Send the message to the international partners before the numbers when a person has time to read it; it is the project's own account of the correction and the recovery, and it carries the disclaimer on the 36M and 50M milestones. Hindi PDFs and tutorials were promised by the project on 25 September; until they arrive the English library is the reference for India. An Indian consultant and community leader may join team sessions on a fixed schedule rather than daily; agree the slots through Alex. The twenty-one contract addresses are tabled in Terms today with the explorer check; the charge incentive pool address is unconfirmed and members should send nothing to it.
The library is the database. A question goes to the assistant first, then to the Knowledge cards, then through the feedback button at the bottom of the screen, which sends it to the Phalanx team. What is missing is added in the next edition. Nobody answers questions one by one in private.
Before any call. The News section, newest first. Forward every security notice the day it appears.
Rates, bond prices and the vault cap on spartanar.org. If a figure differs from Terms today, the dApp wins; leave a note through the feedback button so the page is updated.
The calculators, with the person's own amount and structure. Never the top of the table.
Any question this page could not answer goes through the feedback button at the bottom of the screen. The next edition carries it.
Leader material, open to every leader on this page. Use it in calls and in the team; do not post it on public channels.
Short, plain, and true to the material. Copy, change the bracketed parts, send.
Quick one. I am sending you the Spartan OS deck. It runs on Anubis Chain, live since April, with its own explorer, so every number in it can be checked tonight. Staking pays daily in RM, bonds are separate, and the rank ladder is published. Fifteen slides, ten minutes. Tell me which slide you stop on and I will answer that one first.
Did the deck land? The page most people ask about is the staking table: one rate per period, each with its cap and its date, nothing guaranteed. If you want the one-page version, I will send it. If you want the numbers walked through, I have a Zoom slot tomorrow evening.
Spartan OS walk-through, tomorrow at [time], forty minutes. I present the deck, then we open the explorer together and check the figures live. Bring one question you want answered before you would put anything in. Link: [Zoom link].
One more thing before any figures. The project wrote a message for people joining from outside China: how it reached 35 million USDT since April, with the correction in the middle and the recovery after it, and the six lines of discipline the early communities took from it. It is the best answer I have to 'why should I trust this'. Ten minutes: [link to the Official section]. Read it before the deck if you can.
Two things, in this order. The Phalanx channel, where the material and the announcements go first: t.me/spartanos_phalanx. Then, only when you have decided, the registration link: spartanar.org/myinvite?code=0x83659d0BDF57ac8550060E869fC5926e52E2e5Fe. The dApp binds the account to the person whose link it first connects through, so use this one and not one from a public chat. Start with a small amount.
Every figure on this page carries its own date and source. When something changes on spartanar.org or in an official statement, the page is rebuilt and this line moves.
Tap the film for the controls · Esc or × closes
Ten posts, two formats, three voices
Each card is a square for feeds and a story for vertical screens, with the text written for X, for Telegram and for Instagram or TikTok. Copy the text, save the card, post them together. No rate appears on any card; the cap and the date travel in the text.
Every long-term position in Spartan OS has a cap fixed in USDT on the day it opens: 4×, 4.5× or 5×. The rate floats. The cap does not. Rates as stated by Spartan OS, September 2026. Not advice.
Every payout in Spartan OS is a purchase. Claim, buy the same RM on RocketSwap, wait 24 hours, release. That is the turbine. It is why the returns are also the buy pressure.
Most projects rent a chain. Spartan OS runs on one its foundation built: Anubis Chain, mainnet since April 2026, chain ID 6714, fees in dollar-pegged gasDAI, 100 million transactions by September. Check it on browser.anubispace.org.
From nothing to the first bond in seven steps: wallet, network 6714, gasDAI, USDT, the referral link, the 540-day bond, the first claim. One evening, a small amount first. Ask me for the guide.
Two legs, not three. In Spartan OS the larger leg qualifies your rank and the smaller leg pays the reward. V1 takes 500 USDT of your own, three directs from 100 USDT, and 10,000 in each zone. Rules as published; rewards move within a band.
Ask any project what happens on the way down. Spartan OS answers with O²: a sell tax in bands when the price falls 5% or more against the three-hour average, buybacks, liquidity protection, reassessed every three hours. Not a floor. A mechanism.
Check it, do not believe it. Bridge reserves: Etherscan. Contracts and trades: browser.anubispace.org. Audits: skynet.certik.com. Rates: the dApp. Everything else a promoter says is a statement, including mine.
No official account will ever ask for your seed phrase. Type addresses, do not click them. Check chain ID 6714. Verify the first four and last four characters. Test with a small amount. There is no official 'Anubischat' app. Forward this.
Start with an amount you would not miss. A bond from one dollar. Run one full cycle: bond, claim, turbine, release. Decide the second amount with the first one behind you. A leader who says this is a leader you keep.
Phalanx Community, for people building Spartan OS on Anubis Chain in English. Every figure with its cap and its date. No promises of return. Links from official pages only. Ask a question, get the source.
One line, the film, no rate. Example: 'Ninety seconds on what Spartan OS is, from the project itself. Built on Anubis Chain.' Tag @Spartan_Arena_ and @AnubisLayer1. Never add a rate to a film.
Post the film with two lines above it: what it shows and why it matters this week. Pin the security notice above every film. Files under 20 MB go as video, not as a document.
Vertical films only (the tutorial recordings). Caption: what the viewer will be able to do after watching, one sentence, then #SpartanOS #AnubisChain #Phalanx. No income figures on camera or in text.
One film a day at most. Text on the status: one sentence and the question 'want the guide?'. Follow with one-pager 06, never the deck, in a status.